



PW Consulting: Piston Connecting Rod Unit Market Set to Reach USD 6,207.38 Million by 2032, New Insight Report Says

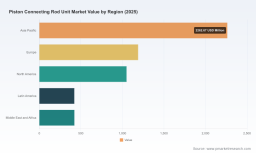
Piston Connecting Rod Unit Market — Strategic Intelligence Briefing for 2026 Decision‑Makers
PW Consulting’s newest market study on the Piston Connecting Rod Unit market (base year 2025, historical window 2020–2025, forecast 2026–2032) presents an evidence‑based roadmap for executive teams preparing strategy and capital allocation choices in 2026. Our firm-level models show the market stabilizing around USD 5.35 billion in 2025 and tracking a modest compound annual growth rate (CAGR) of ~2.15% across the 2026–2032 forecast window. The near‑term profile is characterized by a flat to slightly choppy transition from 2025 into 2026 before recovery and segmentation‑specific expansion later in the decade — a pattern that has important implications for suppliers, OEMs, and investors.
Piston Connecting Rod Unit Market
Why this report matters for 2026
- Actionability under uncertainty: The report blends empirical trend‑fitting with scenario analysis tailored to plausible 2026 shocks (raw material volatility, OEM production oscillations, regulatory updates), enabling teams to stress‑test supplier strategies and capital plans without relying on one narrative.
- Cost & margin pressure visibility: With global steel benchmarks remaining a salient input to manufacturing economics, PW’s analysis quantifies the pass‑through dynamics and margin sensitivity to sustained steel price weakness or recovery — a critical short‑term lever for procurement and pricing teams.
- Competitive concentration and negotiation posture: The industry displays a moderate level of supplier concentration (three‑firm and five‑firm concentration metrics are material inputs in our bargaining models), which alters bargaining power across segments and should shape supplier diversification plans in 2026.
- Technology and product roadmaps: Our engineering‑led assessment identifies which material and process investments (advanced forging, novel alloys, powder‑metal processes, precision machining) are most likely to deliver step‑change improvements in strength‑to‑weight and cost tradeoffs through 2032.
High‑level market characteristics to orient 2026 strategy
- Scale and trajectory: After a cyclical recovery through the early 2020s, market size in 2025 sits near USD 5.35 billion. PW’s baseline forecast projects a measured expansion through the forecast window, with upside tied to commercial vehicle activity and performance‑segment adoption of premium materials.
- Cost environment: Steel remains the dominant raw material input for connecting rods. Benchmarks indicate global steel references near 3,163 CNY per tonne as of April 2026, and most market participants expect limited price recovery in 2026 amid subdued demand and persistent overcapacity. This dynamic compresses near‑term margins for suppliers that cannot convert price movements into contractual pass‑throughs.
- Technology imperatives: Manufacturers are increasing investment in advanced forging and precision engineering, with a clear focus on improving strength‑to‑weight ratios. These capabilities are central to capturing growth in higher‑performance applications and in segments where emissions and efficiency requirements raise the bar on component design.
- Quality and standards: Compliance with ISO 9001:2015 and strict OEM material/dimensional requirements remains table stakes across the supply chain. Certification and traceability protocols are differentiators in tender processes and aftermarket acceptance.
What the PW Consulting report delivers (practical, decision‑ready content)
- Market model & scenarios — forward‑looking volume and value projections under three stressed macro scenarios (baseline, downside demand shock, and accelerated electrification mix), with sensitivity dashboards you can drop into financial models.
- Cost build‑ups — raw material, processing, and finishing cost stacks for the principal manufacturing routes, with breakeven curves and margin levers to support procurement negotiations and price‑setting.
- Supply chain maps — supplier concentration overlays, tier‑1 and tier‑2 exposure matrices, and logistics risk heatmaps that identify single‑point failures and re‑routing opportunities.
- Technology radar & investment playbook — evaluation of forging vs powder‑metal vs cast routes, alloy roadmaps, expected CAPEX and yield curves, and recommended R&D priorities to achieve targeted strength‑to‑weight and cost outcomes by 2028 and 2032.
- Commercial playbooks — go‑to‑market strategies for aftermarket, OEM, and performance channels; pricing architectures; and templates for strategic partnerships and licensing agreements.
- Competitor intelligence — structured company profiles, capability benchmarking, and M&A opportunity screening to support acquisitive consolidation or targeted JV strategies.
- Implementation checklists — procurement hedging strategies, quality control upgrade sequences (for ISO recertification and digital traceability), and integration timelines for plant upgrades.
Competitive landscape — what to watch in 2026
- Global full‑system suppliers: Firms that supply across pistons and connecting rods (and can offer integrated piston‑connecting rod assemblies) retain strategic advantage with OEMs because they simplify qualification and logistics. These players are investing in modular offerings and system performance verification to deepen OEM relationships.
- Forging specialists: Established forged‑component groups are doubling down on scale and process control, optimizing cycle time and metallurgical consistency to sustain margins when steel price passes are limited. Expect continued automation investments and selective regional capacity additions aligned with OEM footprints.
- Performance and niche manufacturers: High‑performance and racing suppliers (those working with titanium, billet aluminium, and premium forged steels) remain structurally attractive despite smaller absolute volumes. Their nimbleness in materials and tolerancing allows them to command premium pricing and to participate in co‑development arrangements with OEMs and motorsport partners.
- Aftermarket and regional producers: Large regional manufacturers with broad product ranges and export capabilities will be key suppliers for replacement and industrial applications. Their value proposition is serviceability, availability, and cost competitiveness rather than engineering exclusivity.
Across these archetypes, recent market moves underscore tactical priorities for 2026. Strategic partnerships and product launches in late 2025–early 2026 highlight a two‑track industry response: consolidation of engineering capabilities at the high end, and targeted product portfolio updates for legacy engines and industrial use cases. Service instruction updates and product releases affecting component interfaces indicate ongoing OEM and engine‑builder activity to improve field serviceability and component longevity — areas that create aftermarket and retrofit opportunities.
Piston Connecting Rod Unit Market
Company positioning snapshot (implications, not raw scores)
- Mahle GmbH — Deep OEM relationships and a system‑component footprint give Mahle leverage to negotiate longer qualification cycles and to promote integrated assemblies. For competitors, this means prioritizing differentiated technical offers or faster time‑to‑qualification where Mahle is the incumbent.
- thyssenkrupp Forged Technologies — Forging scale and multi‑segment capability align the company for contracts across light and heavy duty engines; its strategic posture will be to protect volume contracts while selectively upgrading process capabilities for higher‑margin segments.
- CP‑Carrillo, Pankl, Oliver Racing, GRP, MGP, Pauter — These high‑performance specialists will continue to capture premium margins in racing and performance niches. Partnerships and co‑branded product launches increase their appeal to OEMs seeking rapid validation for high‑stress applications.
- AECO (Arrow Engine Parts), Chorng Ko (TOP Rod), Shriram Pistons and Rings — Regional manufacturing scale and export orientation position these firms well for aftermarket and industrial engines. Their challenge in 2026 will be managing raw material cost volatility while defending price‑sensitive segments.
- Motorservice (Kolbenschmidt) — Market access via aftermarket channels and replacement parts breadth is a durable advantage; scale in logistics and aftermarket certification will be central to retaining share as service patterns evolve.
Strategic implications and recommended actions for 2026
- Prioritize procurement resilience: Lock in multi‑source supply, explore hedging instruments for critical steel inputs, and negotiate formula‑based contracts that maintain margin visibility if steel prices remain depressed or volatile.
- Accelerate process automation and metallurgy upgrades selectively: Invest where incremental unit cost reductions or performance gains drive measurable ROI for targeted segments (performance and commercial vehicles).
- Refine channel strategies: Differentiate product lines between OEM system suppliers, aftermarket cost leaders, and performance premium players — and align commercial terms to the cadence of each channel’s purchasing cycles.
- Use targeted M&A and partnerships to buy capabilities: For firms lacking forging scale or premium alloy expertise, consider bolt‑on deals or technical partnerships rather than greenfield builds, especially in regions with material cost advantages or near‑OEM clusters.
- Institutionalize certification and traceability: Elevate quality management and digital traceability to shorten aftermarket acceptance cycles and to meet tightening OEM material traceability expectations.
- Embed scenario planning into capital allocation: Run at least two downside demand scenarios in 2026 capital reviews to avoid over‑committing on capacity while preserving agility to scale when recovery signals firm up.
Why PW Consulting’s market study is the pragmatic choice for 2026 planning
Our analysis combines a full epidemiology of market activity (past performance and near‑term inflections), rigorous cost modeling keyed to live raw material benchmarks, and an executable playbook that translates market intelligence into procurement, product, and M&A actions. Rather than offering a single forecast, the study provides decision tissues — sensitivity matrices, supplier negotiation scripts, and CAPEX phasing templates — that operational teams can adopt immediately.
Piston Connecting Rod Unit Market
Next steps — where to get the full intelligence
This briefing highlights the primary strategic signals from PW Consulting’s Piston Connecting Rod Unit market study and how they should inform 2026 decisions. To access our full data tables, interactive scenario dashboards, company benchmarking sheets, and the confidential segmentation detail that underpins the recommendations above, please visit the report landing page. The full dataset includes the discrete regional, material, and application splits, as well as downloadable modeling files that corporate strategy, procurement, and engineering teams will find essential to finalize 2026 roadmaps.
For detailed analysis of this topic, please visit the official page: Piston Connecting Rod Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


