



PW Consulting: Paper Laminates Market to Reach USD 23,934.05 Million by 2032, Growing at a 5.48% CAGR

Paper Laminates Market: Strategic Preview for 2026 — What's at Stake and What Your Board Needs to Decide
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our full Paper Laminates Market report (base year 2025, forecast 2026–2032). This briefing synthesizes macro trends, regulatory inflection points, raw-material pressure, and competitive moves that will shape strategic choices in 2026. Our aim is to give executives the line-of-sight required to set priorities, while directing tactical teams to the full report for granular segmentation and action plans.
Paper Laminates Market
Executive snapshot
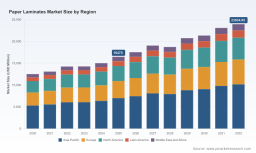
The paper laminates market completed 2025 as a mature but dynamic sector, with an estimated market size approaching USD 16.5 billion and a compound annual growth rate (CAGR) of approximately 5.48% through the 2026–2032 forecast window. Market concentration remains moderate: the top three firms account for roughly 22% of the market, and the top five for about 32.4% — a structure that favors nimble innovation and targeted scale plays rather than outright monopoly strategies.
Paper Laminates Market
Why 2026 is a pivotal year
- Regulatory acceleration: Binding mandates and producer responsibility schemes that take effect or ramp up in 2025–2030 are converting sustainability preferences into commercial requirements.
- Raw material volatility: Pulp and polymer price swings are compressing margin cushions and forcing reengineering of laminate formulations and sourcing strategies.
- Product differentiation: Advances in recyclable and mass-balanced laminates are creating new shelf and supply-chain value that commands premium contracts.
Market dynamics that will guide corporate choices
Four converging forces will dominate boardroom debates in 2026:
Paper Laminates Market
- Regulatory push for recyclability and recycled content. Legislations such as an EU-level packaging waste reform that mandates minimum recycled content, and state-level extended producer responsibility (EPR) programs, are moving paper laminates from optional sustainability narratives to compliance line-items. These rules will influence material specs, supplier selection, and end-of-life cost allocation.
- Cost signals from pulp and polymers. Bleached hardwood kraft pulp and lamination-grade polyolefin prices continue to oscillate at levels that materially affect product economics. Recent indices show pulp averaging in the high hundreds of USD per metric ton late in 2025 and LDPE at elevated levels in early 2026, warranting immediate procurement hedging and substitution assessments.
- Customer preference and brand risk. Retailers and CPG brands are accelerating sourcing policies that prioritize recyclability and lower-carbon feedstocks; suppliers unable to demonstrate credible pathways to recyclability or recycled-content will face margin pressure or disqualification from tenders.
- Consolidation and capability plays. With moderate market concentration, strategic M&A (bolt-on capacity for barrier coatings, extrusion-lamination capabilities, or recycling feedstock) remains an efficient route for capability scaling without the cost of greenfield builds.
What this means for strategic planning in 2026
Executives must translate macro pressure into three core imperatives for 2026 action plans:
- Fix supply-side economics now. Implement multi-year offtake and raw-material contracts, explore co-located compounding/lamination to reduce freight and conversion cost, and evaluate alternative barrier technologies to reduce reliance on volatile polymers.
- De-risk regulatory compliance. Build an explicit roadmap for recycled-content certification and EPR cost pass-through — including pilot programs with customers to validate collection and recycling loops that preserve margin.
- Invest in differentiating capabilities. Prioritize investments in recyclable and mass-balanced laminates, digital quality assurance, and barrier performance improvements that preserve shelf-life without sacrificing recyclability.
Competitive landscape — who’s setting the agenda
The market is shaped by a mix of global paper and packaging integrators and specialized laminate developers. Our analysis focuses on firms that matter to sourcing, benchmarking, and potential partnership/M&A strategies:
- Mondi Group (Vienna, Austria): A global leader in paper-based packaging, Mondi has recently launched a PEEL & SEAL paper-based laminate positioned for recyclable flexible packaging. The product launch signals a use-case-first approach to replacing conventional multilayer films.
- WestRock Company (Atlanta, USA): Known for folding cartons and extrusion-coating capabilities, WestRock’s recent exhibition of fiber-based laminates with high barrier performance highlights an effort to reconcile barrier requirements with fiber-based recyclability.
- Smurfit Kappa Group (Dublin, Ireland): Certification wins for recycled content indicate the company is advancing upstream feedstock credibility — a differentiator in tenders requiring documented recycled inputs.
- International Paper Company (Memphis, USA): With emphasis on corrugated packaging and specialty laminates, International Paper remains relevant for industrial and institutional packaging formats where durability and barrier properties are essential.
- DS Smith plc (London, UK): DS Smith’s focus on sustainable e-commerce and food-sector laminates underscores the growing intersection of logistics performance and recyclability.
- Tetra Laval (Tetra Pak) (Pully, Switzerland): As the leading aseptic carton supplier, Tetra Pak continues to push multi-layer laminate innovations — balancing aluminum/foil and polymer elements for sterilization and shelf stability.
- Stora Enso Oyj (Helsinki, Finland): Investment in mass-balanced paper laminates and commercial-scale production lines reflects a strategic bet on renewable barriers as plastic alternatives.
Recent corporate moves — product launches, trade show showcases, certification achievements, and new production lines — reveal two tactical truths: incumbents are betting on both technology and claims verification (certifications); and first movers on credible recyclable laminates can secure preferential positioning with brand customers.
Report scope and practical outputs (what’s inside the full PW Consulting report)
The full report is structured to support operational and strategic decisions, and includes:
- Market sizing (historical 2020–2025 and detailed forecasts 2026–2032) and a calibrated CAGR assumption to stress-test planning scenarios.
- Scenario-based forecasts that quantify upside/downside outcomes under alternative regulatory and raw-material trajectories.
- Commercial playbooks for procurement (hedging and supplier contracts), R&D prioritization (barrier vs. recyclability trade-offs), and go-to-market (value-selling to brand owners and converters).
- Competitor profiles and capability matrices that benchmark barrier technologies, certification status, and geographic manufacturing footprints.
- Practical checklists for compliance with EPR schemes and recycled-content reporting, plus a vendor shortlist for pilot partnerships.
- Financial sensitivities (margin-at-risk analysis) linked to pulp and polymer price bands and to potential compliance cost pass-throughs.
Examples of board-level questions the report helps answer
- Should we accelerate capital allocation to retrofit lamination lines for recyclable structures, or buy capability via acquisition?
- How do varying pulp and LDPE price scenarios affect our product mix profitability through 2028?
- What is the optimal commercial model to recover EPR costs without losing share to less transparent competitors?
- Which strategic partnerships — fillers, recyclers, certification bodies — deliver the fastest path to demonstrable compliance?
Recommended 90-day playbook for 2026
- Operational: Run a procurement stress-test on pulp and LDPE exposure; secure staggered supplier contracts to smooth cost volatility.
- Regulatory/compliance: Complete a gap analysis against regional recycled-content and EPR mandates; initiate certification pilots where shortfalls exist.
- Commercial: Launch two customer pilots that co-develop recyclable laminate SKUs with anchor CPG partners to secure early wins and reference cases.
- Strategic: Shortlist two capability targets for potential bolt-on M&A (coating expertise; recycling feedstock access) and begin nondisclosure discussions.
Why our granular segmentation is deliberately withheld here
This communication follows a “trailer” approach: our goal is to establish confidence in the report’s strategic value while preserving restricted, high-action segmentation and contract-level insights for subscribers. The full report contains the detailed regional, type and application splits, supplier share movements, and contract-level pricing intelligence necessary to execute or defend market positions — information we withhold here to ensure competitive integrity and to invite stakeholders to the full analysis.
Final perspective
As the paper laminates market transitions from optional sustainability to regulatory imperative, the 2026 planning cycle will reward firms that translate compliance into product premium — and penalize those that view recyclability as a marketing exercise. PW Consulting’s full report equips executives with the data, scenarios, and tactical playbooks needed to preserve margin, capture growth, and reduce regulatory and raw-material exposure. For boards and strategy teams, this is not an incremental planning exercise; it is a portfolio re-underwriting moment.
Next steps
- Access the full report to obtain the detailed regional and application segmentation, contract-level pricing models, and supplier scorecards needed to operationalize the recommendations above.
- Contact PW Consulting to schedule a bespoke executive briefing and a 90-day implementation workshop aligned to your footprint and risk profile.
PW Consulting — translating market complexity into actionable advantage for the paper laminates value chain.
For detailed analysis of this topic, please visit the official page: Paper Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


