



PW Consulting: High-Performance Fibers for Defense Market Valued at USD 2,056.35 Million in 2025, Poised for Robust Growth

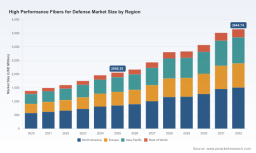
High Performance Fibers For Defense Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting today publishes an executive briefing drawn from our forthcoming market research report, High Performance Fibers For Defense Market (base year 2025; forecast 2026–2032). This briefing highlights why the market’s medium‑term trajectory and structural dynamics should be a central consideration for C‑suite strategy, procurement, and R&D roadmaps through 2026. We present actionable, decision‑grade perspectives while preserving the report’s proprietary segmented intelligence — the granular tables, region/application splits and supplier scorecards remain available in full through our report portal.
High Performance Fibers For Defense Market
Executive snapshot: a market expanding under sustained strategic demand
After a steady recovery and expansion during 2020–2025, the global market for high performance fibers for defense rose from approximately USD 1.39 billion in 2020 to an estimated USD 2.06 billion in 2025. Our forecast anticipates continued growth, with the market reaching roughly USD 2.17 billion in 2026 and expanding to an estimated USD 3.64 billion by 2032. That trajectory reflects a compound annual growth rate (CAGR) of approximately 8.52% across the 2026–2032 forecast period — a rate driven by accelerating defense modernisation programs, lightweighting priorities in aerospace and platforms, and sustained demand for personal protection systems.
High Performance Fibers For Defense Market
Why 2026 is a strategic inflection point
-
Qualification timelines compressing: Defense procurement cycles and fielding windows are tightening. Qualification and certification for new fiber systems still commonly require multi‑year ballistic testing and supplier audits, so choices made in 2026 will often determine program supply chains through the early 2030s.
High Performance Fibers For Defense Market -
Supply chain resilience vs. cost pressure: Producers face dual pressures — raw material volatility (notably petrochemical precursors for para‑aramid and capital‑intensive gel‑spinning for UHMWPE) and the need to insure supply against export controls and trade restrictions. Strategic sourcing decisions and localised capacity investments initiated in 2026 can materially alter lifecycle cost and availability for prime contractors.
-
Technology convergence driving premium capture: Advances in carbon fiber grades, new aramid variants, and UHMWPE processing are creating displacement opportunities across vehicle armor, aircraft structures, and personal protective equipment. Early adopters of next‑generation fiber grades can capture weight and performance premiums while increasing barriers to entry for competitors.
What the PW Consulting report delivers (practical, executable content)
Our research is designed for executives who need to convert market insight into executable strategy. The full report package includes:
-
Macro market model (2020–2032) with downloadable time series and scenario options that allow you to run your own revenue and margin sensitivities under differing demand, price, and trade‑policy assumptions.
-
Supplier scorecards that assess technical capability, qualification footprint, production capacity elasticity, and supply‑chain risk for the leading producers.
-
Qualification timeline playbooks that map testing/regulatory gates, average timelines, and mitigation strategies for accelerating supplier approval.
-
Raw‑material exposure matrices that quantify cost sensitivity to petrochemical and solvent price swings and outline hedging and vertical integration levers.
-
Commercial frameworks for negotiating long‑term supply agreements, offtake structures, and shared investment in localized processing (e.g., solvent recovery units for UHMWPE gel‑spinning).
-
Target lists and M&A screening filters identifying mid‑market assets that accelerate market entry, add qualification credentials, or provide complementary processing capabilities.
Competitive landscape: positioning and recent moves
The industry remains moderately concentrated: our competitive analysis finds the top three producers account for nearly half of market revenue, while the five largest players approach just over sixty percent market share — a structure that supports strategic collaboration while leaving room for challengers with focused technical or geographic strengths.
Key incumbent profiles and strategic implications:
-
DuPont de Nemours, Inc. (Wilmington, Delaware, USA) — a global leader in para‑aramid fibers with a well‑established Kevlar franchise. DuPont’s expanded portfolio and ongoing qualification activity signal continued emphasis on ballistic protection for personal and vehicle armor. For customers, DuPont represents a de‑risked, broadly qualified supply source; for competitors, it sets benchmark performance and compliance standards.
-
Teijin Limited (Tokyo, Japan) — major para‑aramid and carbon fiber producer with a balanced defense offering. Teijin’s mix of ballistic and composite capabilities makes it an attractive partner for integrators seeking integrated material solutions for both protection and structural applications.
-
Honeywell International Inc. (Charlotte, North Carolina, USA) — with UHMWPE fibers (Spectra) and ballistic systems (Spectra Shield), Honeywell plays to the lightweight, high‑stopping‑power segment. Its strength is in consolidated ballistic systems rather than raw fiber commoditization, making it a preferred supplier for turnkey armor solutions.
-
Toray Industries, Inc. (Tokyo, Japan) — dominant in high‑performance carbon fibers; recent supply agreements and new grades (e.g., TORAYCA M46X) sharpen its edge for weight‑sensitive aerospace and defense platforms. Strategic customers should monitor Toray’s capacity allocations as its Decatur, Alabama presence grows.
-
Avient Corporation (formerly DSM Dyneema, Cleveland, Ohio, USA) — UHMWPE specialty producer with strengths in high‑strength, ultra‑light fibers. Dyneema‑derived solutions are central for applications where weight and mobility confer tactical advantage.
-
Regional and specialist players — Kolon, Hyosung Advanced Materials, Hexcel, Mitsubishi Chemical, and SGL Carbon each occupy important niches: aramid variants, advanced yarns, carbon fiber prepregs and composites, and semi‑finished components. These firms often act as strategic partners for localized manufacturing and systems integration.
Recent industry developments to watch
-
Supply agreements and capacity reinforcement (e.g., Toray’s multi‑year contracts and facility emphasis) indicate OEMs are seeking supply certainty for defense programs with extended life cycles.
-
New product introductions (e.g., Hexcel’s HexTow IM9 grade and Toray’s high‑modulus TORAYCA lines) are raising the technical bar for weight‑critical composite components — offering designers options to trade cost for dramatic weight savings.
-
Portfolio expansions among legacy aramid and UHMWPE vendors reflect ongoing efforts to shorten qualification cycles and bundle material + systems offerings for defense primes.
Market dynamics that will drive supplier and buyer behavior
-
Raw material volatility: Para‑aramid production depends on petrochemical precursors (PPD, TPC) whose pricing follows benzene/xylene derivatives; UHMWPE manufacture relies on capital‑intensive gel‑spinning and solvent recovery. These inputs create earnings cyclicality and favour suppliers with scale or vertical integration.
-
Trade and export controls: High‑performance fibers for defense remain sensitive to export regulation. Buyers should model geopolitical scenarios when selecting global versus local suppliers and consider qualification paths that mitigate cross‑border risk.
-
Qualification friction: Expect 2–5 year qualification windows for many military systems. Program managers must couple procurement timing with supplier selection early to avoid retrofit costs and program delays.
Strategic imperatives for 2026
Our analysis yields seven imperatives for organizations that need to translate market dynamics into competitive advantage:
-
Embed supply qualification into program schedules — start supplier testing and regulatory engagement early to avoid downstream schedule slippage.
-
Diversify material exposure — evaluate a blended material strategy (aramid, UHMWPE, carbon fibers) as a hedge against raw‑material and policy shocks while preserving platform performance objectives.
-
Invest in localised processing where strategic — co‑investments in solvent recovery or prepreg capacity can reduce lifecycle costs and improve qualification speed for priority programs.
-
Use long‑term commercial structures — offtake, price‑volume collars, and shared capex agreements can align incentives between primes and fiber producers and reduce cost volatility.
-
Pursue selective M&A or JVs — target assets that deliver immediate qualification credentials or fill capability gaps versus building capability organically under constrained timelines.
-
Monitor emerging grades and material substitution risk — track carbon fiber modulus/strength improvements and next‑generation aramid/UHMWPE variants to capture structural or weight‑savings opportunities early.
-
Prioritise compliance and export strategy — build a regulatory playbook and verify alternate sourcing routes for critical programs.
How PW Consulting can accelerate your 2026 planning
This briefing is a preview of our full report, which contains the complete datasets, supplier granularities, and executable playbooks referenced above. For procurement teams, program managers, investors, and R&D leaders, the report functions as both a market map and a tactical toolkit: it prescribes when to lock supply, where to invest in qualification, and how to structure commercial arrangements that protect programs against material and policy shocks.
Contact PW Consulting to request the full report package, access the interactive market model, or commission a tailored decision workshop that applies these findings directly to your program portfolio. The full intelligence suite contains the detailed regional and application segmentation, supplier scorecards, and scenario models that many organizations require to make binding 2026 commitments.
For detailed analysis of this topic, please visit the official page: High Performance Fibers For Defense Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


