



PW Consulting: Waste Paper Reuse Market Poised for 5.2% CAGR in 2026–2032, Signaling Strong Upswing in Recycling Sector

Waste Paper Reuse Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
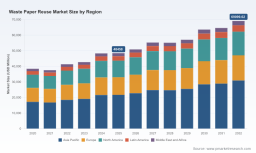
PW Consulting’s latest Waste Paper Reuse Market report — base year 2025, forecast period 2026–2032 — frames a turning point for companies operating across the recovered-fiber value chain. The global waste paper reuse market reached USD 48,458 Million in 2025 and, under the central case, is projected to expand at a 5.2% CAGR through the forecast window. By 2032 the market is expected to approach the USD 69 billion range, driven by policy acceleration, packaging demand dynamics, and structural shifts in trade and processing capacity.
Waste Paper Reuse Market
Why this report matters for 2026 corporate decision-making
-
Timing: 2026 is the inflection year when regulatory tightening, capital investments and a recovering demand base converge. Companies that align procurement, processing capability and commercial contracts in 2026 will lock in margin and supply advantages for the rest of the decade.
Waste Paper Reuse Market -
Practicality: The report goes beyond high-level forecasts — it contains executable playbooks, ROI models and scenario toolkits that translate the macro trajectory (5.2% CAGR) into boardroom-ready investment decisions and operational KPIs.
Waste Paper Reuse Market -
Risk-to-opportunity mapping: With the market expanding but remaining relatively fragmented (CR3 ≈ 18.5%, CR5 ≈ 24.2%), there is room for consolidators and service innovators. The strategic choices are therefore clear: scale selectively, pursue vertical integration where feedstock security matters, or specialize in premium recycled grades and value-added services.
Market dynamics shaping 2026 strategies
Three structural forces create the near-term playbook for 2026:
-
Policy acceleration and materials stewardship — Extended Producer Responsibility (EPR) rules are being implemented across major jurisdictions; several U.S. states phased in fee obligations and reporting requirements in 2025–2026, while European recycling systems continue to deliver high collection rates. These regulatory shifts reallocate costs along the value chain and elevate supply-chain transparency requirements. Companies must redesign commercial terms and data systems to internalize EPR liabilities and exploit compliance-driven demand for audited recycled content.
-
Trade and feedstock quality constraints — Import restrictions and contamination thresholds in many Asian markets are permanently reshaping global recovered paper flows. Procurers and converters must now optimize for onshore processing and invest in upstream sorting/cleaning to maintain consistent fiber quality, rather than rely on low-cost cross-border arbitrage.
-
Capacity realignment and pricing gravity — 2024–2026 saw meaningful capacity additions and plant modernizations in recycling and containerboard processing, with several large-scale facility projects commissioned or announced. These supply-side investments are gradually absorbing incremental recovered fiber demand, producing an environment where price swings are more closely linked to operational uptime and feedstock quality than to simple supply/demand imbalances.
Operational levers for 2026
Executives and procurement leads should prioritize the following actions immediately:
-
Secure feedstock through diversified channels: blend long-term offtakes with local procurement and strategic partnerships with collection networks to mitigate contamination and logistics risk.
-
Invest in quality capture: incremental CapEx in sorting/optical systems, contamination screening, and baling standards can yield outsized improvements in mill yield and pricing power.
-
Negotiate EPR-aware contracts: renegotiate supplier and customer contracts to crystallize who bears EPR fees, documentation costs, and liability for non-compliant material streams.
-
Adopt agile pricing mechanisms: incorporate quality, tonnage bands and index-linked adjustments to protect margins amid feedstock PPI volatility.
Competitive landscape — what the majors are doing (and why it matters)
The market remains fragmented but strategically active. Several established players are executing clear, differentiated strategies that set reference points for 2026 planning.
-
Integrated paper and packaging leaders such as International Paper, Smurfit Westrock, DS Smith, Mondi, UPM and Stora Enso are leveraging scale in recovered-fiber procurement to secure containerboard and packaging feedstock. Their models emphasize vertical integration, procurement control, and closed-loop partnerships with brand owners seeking recycled content assurances.
-
Waste-to-material specialists — Waste Management, Republic Services, Veolia and Sonoco have doubled down on MRF capacity and downstream sorting to supply mills with cleaner bales. Recent plant openings and upgrades indicate a push to capture higher-margin secondary material flows, partnering directly with mills and converters.
-
Regional champions and 100% recycled players — Companies such as Nine Dragons, Pratt Industries, Cascades and Sappi demonstrate that regional sourcing footprints and dedicated recycled-fiber mills continue to be a viable route to scale. Their operations show how proximity, trade-adaptive strategies and tailored product mixes mitigate contamination and trade restriction risks.
-
Innovation signals — Firms are investing in process automation, advanced sorting sensors, and fibre-restoration techniques to raise the value of lower-grade streams. These tech investments are a competitive differentiator for converters targeting premium recycled-content applications.
Recent public moves underscore these trends — large recycling network expansions, multi-million-pound facility launches, and industry statistics pointing to robust recycled consumption all indicate an industry in structured growth and operational upgrade. PW Consulting’s report synthesizes these company-level actions into strategic options for buyers, processors and investors.
What’s inside the PW Consulting report (practical deliverables)
This is a working intelligence product, built to convert market foresight into executable change across 2026 programs:
-
Scenario models (fast/medium/slow adoption) with sensitivity to policy, trade disruption and feedstock price shocks — each scenario includes P&L impact, balance-sheet sensitivity and decision triggers for capex or M&A.
-
Supply chain maps and feedstock flow visualizations — granular network views highlighting choke points, logistics cost pools and onshore processing opportunities (interactive maps available in the full report).
-
Operational playbooks — step-by-step guidance for MRF upgrades, bale specification standards, contamination mitigation, and yield improvement programs with expected payback periods.
-
Commercial templates and EPR compliance checklists — contract language, fee allocation models and reporting frameworks aligned with emerging EPR regimes to reduce legal and cost uncertainty.
-
Investment assessment tools — CapEx calculators, ROI models and post-merger integration checklists tailored to recycling and secondary-fiber assets.
-
Market intelligence appendices — time-series market size by year (2020–2025 historical, 2026–2032 forecast), price indices and a vendor matrix with capabilities assessment (note: detailed segmentation tables are available in the full report portal).
Implications by stakeholder
-
Paper and packaging converters: Redefine procurement around quality-adjusted cost-per-ton rather than headline price. Invest selectively in upstream sorting partnerships to protect production continuity and recycled-content claims.
-
Waste management and MRF operators: Pursue strategic alliances with mills and converters; prioritize automation and certify bale quality to capture greater downstream share.
-
Brand owners and retailers: Use EPR timelines to lock recycled-content procurement, consider shared investment in collection infrastructure, and align packaging design to maximize recyclability and post-consumer reclamation.
-
Investors and private equity: Look for consolidation targets that unlock scale synergies in feedstock procurement and offer immediate yield improvements via operational upgrades.
Near-term watchlist for boards and CEOs (2026 priorities)
-
Finalize EPR exposure analyses and update commercial terms by Q2–Q3 2026.
-
Allocate capital to purification and sorting (optical sorters, deinking, contamination removal) in markets constrained by import quality limits.
-
Pursue targeted partnerships with waste collectors and MRFs to secure quality streams and reduce logistics cost per recoverable ton.
-
Run a one-quarter sprint to certify bale specifications and traceability to support premium recycled-content contracts.
Conclusion — the 2026 strategic moment
2026 is not merely another year of growth for the waste paper reuse market; it is the year in which policy, processing capacity and commercial frameworks crystallize into durable structural advantages for first movers. With the market base at roughly USD 48.5 billion in 2025 and a forecast CAGR of 5.2% to 2032, firms that convert insight into operational certainty — by securing feedstock, investing in quality capture, and renegotiating commercial models for EPR — will outperform peers.
PW Consulting’s Waste Paper Reuse Market report equips leaders with the models, playbooks and scenario-tested recommendations required to act decisively in 2026. For detailed segmentation, interactive models, company scorecards, and downloadable Excel toolkits, access the full report on our portal — the data and executable templates behind this brief are available to subscribers and corporate clients.
For detailed analysis of this topic, please visit the official page: Waste Paper Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


