



PW Consulting Forecast: Packaged Baked Goods Market to Expand at a 5.15% CAGR During 2026–2032

Packaged Baked Goods Market 2026 Outlook — Strategic Imperatives for Growth and Resilience
Executive snapshot
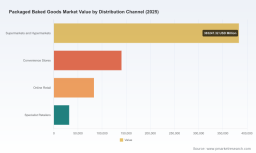
Our latest Packaged Baked Goods Market study (base year 2025, historical 2020–2025, forecast 2026–2032) positions the sector squarely in a moderate-growth, structurally shifting phase. The global market reached approximately 638,600 USD Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 5.15% through 2032, with total market value approaching 907,600 USD Million by the end of the forecast window. These headline figures conceal a more nuanced story: an industry that is simultaneously fragmented, margin-compressed and rich in discrete pockets of premiumization, convenience-driven innovation and regulatory-driven reformulation.
Packaged Baked Goods Market
Why this report matters for 2026 decision-makers
2026 will be a pivotal year for packaged bakery players. Rising input volatility, emergent labeling rules, new product-safety expectations and accelerating retail-channel bifurcation mean firms without a clear, operationally executable strategy will concede shelf space and growth to faster-moving rivals. This report is designed as an executive-grade decision tool: it synthesizes macro drivers and scenario-tested plays into pragmatic roadmaps that translate to board-level priorities, capital-allocation decisions and commercial execution plans for the coming 12–36 months.
Packaged Baked Goods Market
What the report delivers — actionable, not academic
- Strategic dashboards: consolidated KPIs that link revenue scenarios to margin outcomes under alternative raw-material and tariff regimes.
- Scenario modelling: three plausible 2026–2028 trajectories (base, upside, stress) that quantify the impact of input shocks, labeling and packaging EPR adoption on net margin and working capital.
- Go-to-market playbooks: channel-specific growth templates (retailer co-innovation, private-label hedges, direct-to-consumer rapid testbeds) with implementation milestones and resource estimates.
- Supply-chain risk heatmaps: vulnerability scoring across procurement, co-manufacturing and distribution networks, with mitigation protocols and supplier segmentation guidance.
- SKU rationalization & portfolio fit tools: practical checklists and a decision matrix to prioritize SKUs by profitability, strategic fit and retailer economics.
- Pricing and promotion toolkit: elasticities, pass-through scenarios and promotional ROI calculators tailored to baked-goods buying patterns.
- Regulatory compliance timeline and impact assessment: an actionable path to compliance with evolving front-of-pack nutrition labeling and packaging EPR regimes.
- M&A and partnership playbook: target archetypes, valuation levers and integration checklists for inorganic growth or capability access.
Market dynamics shaping strategy in 2026
Three systemic dynamics will determine winners and losers next year.
Packaged Baked Goods Market
- Input-cost volatility and procurement sophistication. Wheat-flour pricing and soft-wheat contract dynamics remain a leading margin swing factor; industry intelligence pointed to material regional price spreads and a modest upward bias into 2026. Successful players will move from linear procurement to layered hedging, supplier segmentation and formula-level cost-to-serve analytics.
- Regulatory and packaging pressure. Regulatory initiatives — notably proposed front-of-package nutrition frameworks and state-level packaging Extended Producer Responsibility (EPR) laws — will force reformulation, labeling redesigns and supply-chain traceability investments on multi-year compliance timelines. Early investments in label architecture and recyclable packaging will reduce transition costs and protect retail acceptance.
- Channel and consumer fragmentation. Retail consolidation in some markets sits alongside rapid growth in convenience formats and online retail experimentation. Consumers are trading across channels more frequently, seeking convenience, perceived health attributes and provenance. This requires nimble assortment strategies and retailer-first commercial plans that capture both everyday consumption and occasion-led premiumization.
Competitive landscape — reading the signals
The sector remains fragmented at the top — the combined market shares of the largest three and five players indicate a low-to-moderate concentration environment — which creates both competitive intensity and M&A opportunity. Leading global and regional manufacturers maintain differentiated defenses that matter in 2026 strategy:
- Grupo Bimbo — leverages unmatched distribution density and scale in fresh and packaged lines. Its global reach makes it a natural aggregator in emerging markets and a benchmark for logistics-led margin playbooks.
- Mondelēz International — portfolios skewed toward sweet baked snacks and biscuits give the company strong shelf-share in global sweet-snack occasions; platform power in branding and shopper-marketing remains a competitive moat.
- Flowers Foods — a U.S.-centric bread and snack-cakes leader that continues to extend portfolio breadth via product-line innovation (for example, low-carb and organic extensions) and incremental private-label manufacturing leverage.
- General Mills & Nestlé — both bring scale in multisector retail relationships and co-manufacturing partnerships, enabling rapid rollouts across retail banners and international corridors.
- Yamazaki, Warburtons, Associated British Foods, Aryzta — regional champions with strong home-market positions that combine bakery heritage with export potential; these players are often acquisition targets or consolidation anchors.
- Hostess, McKee Foods, Britanna — brand-led snack specialists whose consumer affinity and channel penetration allow premium pricing in targeted occasions.
- Rich Products & other ingredient/frozen suppliers — important to bakers looking to outsource complexity, extend shelf-life or enter foodservice channels.
Recent industry developments reinforce these strategic themes: established players continue to launch targeted innovations (e.g., functional or specialty-bread lines and organic extensions), niche innovators push convenience and frozen ready-to-bake offerings into mainstream retail, and product-safety incidents and allergy recalls have sharpened retailer and regulator tolerance for risk. These events underscore the operational premium for traceability, supplier qualification and crisis playbooks.
Regulatory, tariff and input-cost headwinds — practical implications
2026 will see regulatory enforcement catch up with proposals issued in prior years. Proposed front-of-package nutrition labeling will reshape formulation and marketing claims over a 3–4 year compliance window for many companies. Simultaneously, packaging EPR schemes and municipal restrictions on certain packaging substrates will raise per-unit packaging costs and operational complexity. Tariff-induced cost increases in 2025 have already demonstrated how trade policy can lift input costs and compress margins even for domestically oriented bakers.
Immediate actions that materially reduce execution risk include: instituting a label-redesign sprint tied to SKU profitability thresholds; deploying a packaging roadmap that prioritizes recyclable and mono-material formats; and stress-testing supplier agreements against tariff scenarios to protect gross margins.
Operational playbook for 2026 — prioritized moves
- Short-term (0–6 months): conduct SKU profitability triage; re-negotiate supplier contracts with indexed passthrough clauses; launch a rapid compliance audit for labeling and packaging obligations.
- Medium-term (6–18 months): invest in pilot automation in high-labor SKUs; co-develop retailer-exclusive SKUs to defend shelf position; implement a layered hedging program for key commodity exposures.
- Longer-term (18–36 months): restructure the channel portfolio to reflect digital and convenience growth; pursue capability M&A for frozen/ready-to-bake and clean-label technologies; optimize manufacturing footprint to reduce carbon and compliance-related costs.
- Cross-cutting: embed a consumer-occasion taxonomy into category management, align R&D sprints with retail promotional calendars and embed recall/crisis playbooks into distributor agreements.
What success looks like — measurable outcomes for 2026
Companies that follow the playbook can expect to preserve or expand retail distribution while improving gross-margin resilience versus peers. Specifically, success will be measured by: improvement in promotional ROI, lower recall and non-compliance incident rates, faster SKU-to-shelf cycle times for test-and-learn innovation, and demonstrable reductions in packaging costs per unit through design and supplier consolidation.
How PW Consulting supports your 2026 roadmap
As the lead author of this study, PW Consulting combines industry-specific data models, proprietary scenario engines and operational playbooks to help executives translate macro forecasts into executable 12–36 month plans. Our advisory services span rapid diagnostic sprints, full go-to-market transformations, procurement and hedging program design, and M&A due diligence tailored to bakery and adjacent categories.
This press release is a curated preview of the intelligence contained in the full Packaged Baked Goods Market report. To access the complete datasets, granular scenario outputs, supply-chain heatmaps and the actionable playbooks described here, please visit our report landing page where clients can license the full research and schedule a strategy briefing with PW Consulting’s sector team.
For detailed analysis of this topic, please visit the official page: Packaged Baked Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


