



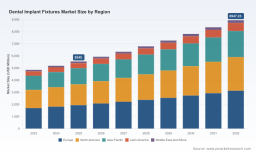
PW Consulting Forecast: Dental Implant Fixtures Market to Hit USD 8,947.23 Million by 2032

Dental Implant Fixtures Market: Strategic Imperatives for 2026 — PW Consulting Insights
As the dental implant fixtures market moves into its next growth chapter, 2026 represents a pivotal planning horizon for manufacturers, distributors, investors and clinical stakeholders. PW Consulting’s latest market study—anchored on a 2025 base year and a seven-year forecast through 2032—shows a resilient expansion trajectory (7.01% CAGR) from a mid‑single‑billion USD market in 2025 toward an almost USD 9.0 billion opportunity by the end of the forecast. This briefing distills the report’s strategic value for executive decision-making in 2026 while preserving the detailed sub‑segment intelligence available in the full report.
Dental Implant Fixtures Market
Why this report matters for 2026 planning
-
Actionable growth timing: The market’s steady compound growth rate provides a predictable environment for investment in product innovation, geographical expansion and channel scaling without assuming speculative volatility.
Dental Implant Fixtures Market -
Concentration dynamics: Market concentration remains meaningful, with the top three and top five firms accounting for a substantial share of the market. This raises both competitive pressures and partnership opportunities—important considerations when evaluating M&A, licensing or co‑development strategies.
Dental Implant Fixtures Market -
Regulatory and reimbursement interplay: Converging regulatory expectations and established reimbursement pathways create a favorable backdrop for higher‑value clinical solutions, but they also require disciplined clinical evidence generation and regulatory planning to unlock payer engagement.
What PW Consulting’s report delivers (practical, executable content)
-
Market sizing and growth scenarios calibrated to 2025 base data and a 2026–2032 forecast horizon that stress‑tests demand under multiple economic and clinical adoption trajectories.
-
Commercial due diligence toolkits: pricing elasticities, channel margin models, payor contracting templates and distributor partnership scorecards designed for rapid deployment.
-
Regulatory roadmap and clinical evidence playbook: step‑by‑step planning aligned with ISO 14801 fatigue testing requirements and regional submission strategies, plus sample statistical endpoints for 1‑, 3‑ and 5‑year outcome studies.
-
Manufacturing and quality controls: guidance on sterilization standards and process validation (gamma irradiation, ethylene oxide, EN 556‑1), plus supplier risk matrices for critical raw materials such as Grade 4 titanium and Ti‑Zr alloys.
-
Competitive benchmarking and playbooks: capability matrices covering design features (e.g., tapered vs parallel, connection interfaces), material mix decisions, and go‑to‑market approaches for premium vs value segments.
-
Deal and investment templates: valuation frameworks that incorporate market concentration metrics and clinical success probabilities, enabling faster yet disciplined decision cycles for M&A or strategic partnerships.
Competitive landscape—what to watch in 2026
The supplier landscape blends global leaders with regional specialists. Several incumbent firms are actively reshaping product portfolios and distribution footprints; their recent moves underscore how competition will be fought in 2026.
-
Straumann Group (Basel, Switzerland) — continues to invest in material science and immediate‑loading platforms, recently extending its BLX family with esthetic enhancements. Their emphasis on differentiated alloys and implant geometry sustains a strong premium position. ( https://www.straumann.com)
-
Nobel Biocare (Danaher) (Zurich, Switzerland) — remains focused on platform breadth and regulatory clearances, including recent 510(k) approvals that broaden clinician choice for parallel and tapered solutions. ( https://www.nobelbiocare.com)
-
Dentsply Sirona (Charlotte, NC, USA) — leverages longitudinal clinical evidence to defend premium conical‑connection offerings; recently published multi‑year outcome data that strengthens adoption in evidence‑sensitive markets. ( https://www.dentsplysirona.com)
-
Zimmer Biomet (Warsaw, IN, USA) — focuses on macro‑porous and trabecular surfaces to accelerate osseointegration, supported by updated regulatory certifications in key geographies. ( https://www.zimmerbiomet.com)
-
OSSTEM Implant (Seoul, South Korea) and Henry Schein (Melville, NY, USA) — examples of how distribution partnerships can accelerate market access, particularly for scalable mid‑market fixtures. ( https://osstem.com; https://www.henryschein.com)
-
Smaller and regional players — continue to compete on cost, targeted clinical niches and rapid distribution execution; their agility is an important consideration for incumbents pursuing cost containment or localized growth strategies.
PW Consulting’s full report includes a granular competitive matrix and product-level value maps that map R&D focus areas to likely share shifts across our forecast horizon.
Regulatory, clinical and reimbursement context that will shape 2026 outcomes
-
Regulation and testing: ISO 14801:2016 remains the benchmark for dynamic fatigue testing; manufacturers that proactively align product development to these mechanical and clinical robustness standards reduce time‑to‑market risk.
-
Material choices: Grade 4 titanium and Ti‑Zr alloys (e.g., Roxolid) continue to be primary materials; material selection materially impacts clinical positioning, cost of goods and sterilization considerations.
-
Reimbursement dynamics: Established reimbursement codes and case‑level reimbursements in mature markets create a predictable commercial calculus for higher‑value implant solutions—if backed by compelling clinical and economic evidence.
-
Safety and quality: As of early 2025 there were no active Class I recalls for major fixtures, but vigilance around implant traceability and sterilization validation remains non‑negotiable.
Top strategic plays for 2026 — a prioritized playbook
-
Double down on clinical differentiation: Prioritize 3‑ and 5‑year outcome studies for platforms that enable immediate loading or improved soft‑tissue esthetics. Evidence reduces payer friction and accelerates adoption among key opinion leaders.
-
Optimize material and cost architecture: Create parallel SKUs where premium alloys support differentiated pricing while cost‑optimized titanium fixtures protect volume segments. Ensure supply contracts for Ti and Ti‑Zr alloys include quality and capacity clauses to mitigate shortages.
-
Channel and distribution strategy: For 2026, pairing direct sales in high‑value clinics with distributor partnerships in volume markets will balance margin and coverage. Use distributor scorecards to drive performance and enforce post‑launch clinical training.
-
Regulatory preparedness: Map product development to ISO mechanical testing windows and pre‑empt submission questions with targeted bench and clinical datasets. If seeking rapid entry, prepare de novo or 510(k) pathways in parallel with CE/other regional filings.
-
Value‑based pricing models: Work with payers and large dental groups to pilot bundled pricing for multi‑tooth and immediate‑loading cases, supported by outcomes‑linked contract terms.
-
Supply‑chain resilience: Invest in dual sourcing for critical components, validate sterilization workflows (gamma/EtO) against EN 556‑1 and set up inventory buffers timed to regulatory approvals and new product launches.
What we intentionally withhold (and why)
This briefing highlights the macro drivers, competitive dynamics and playbooks that PW Consulting believes will be decisive in 2026. To preserve the strategic integrity of our clients’ decisions—and to provide an incentive for deeper engagement—the report intentionally withholds certain granular sub‑segment revenue splits and region/application percentage breakdowns from this press summary. The full report provides those detailed cross‑tabulations, sensitivity analyses and downloadable model files that executives use to build financial forecasts and transaction memos.
Next steps for leaders preparing 2026 budgets
-
Download the full PW Consulting report to access the detailed segment matrices and the financial model exports that underlie our headline forecasts.
-
Commission a ninety‑day rapid due‑diligence from PW Consulting to stress‑test your product roadmap against our regional adoption scenarios and competitor launch timelines.
-
Use our clinical evidence playbook to accelerate payer conversations and design pilot commercialization programs with high‑volume clinic partners.
In an industry where incremental design changes and regulatory timing can meaningfully shift competitive outcomes, 2026 is the year to translate market visibility into executable advantage. PW Consulting’s Dental Implant Fixtures Market study synthesizes market scale, competitive momentum and practical operational guidance so that leaders can make confident, evidence‑based decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Dental Implant Fixtures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


