



PW Consulting: Glass Fiber Composites Market to Expand at 5.24% CAGR Through 2032, Fueled by Asia-Pacific Demand

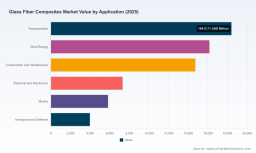
Glass Fiber Composites Market: Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I am pleased to present an executive preview of our Glass Fiber Composites Market report — a practice-oriented intelligence product designed to shape capital allocation, procurement strategy, product roadmaps, and M&A decisions in 2026. The global glass fiber composites market has moved from recovery into a structurally stronger growth phase: our analysis records an increase from a 2020 base through a 2025 market size of USD 66,450 Million (base year 2025) and forecasts expansion to approximately USD 95,008 Million by 2032 at a compounded annual growth rate (CAGR) of 5.24% across the 2026–2032 horizon. This preview highlights why that trajectory matters for corporate leaders next year, what to watch for in supply-side dynamics, and how our report equips practitioners with operational tools — while intentionally withholding core sub‑segment datapoints to encourage direct engagement with the full report for transaction‑grade insights.
Glass Fiber Composites Market
Why 2026 is a Strategic Inflection Point
2026 marks the transition from short‑term patchwork responses to sustained strategic repositioning across the glass fiber value chain. Several converging forces are amplifying the need for deliberate, data‑backed choices:
Glass Fiber Composites Market
- Steady market expansion: The medium‑term CAGR of 5.24% supports disciplined capacity additions and longer payback CAPEX, but timing and location of investments will determine returns.
- Supply‑side realignment: Large incumbent and regional players are executing capacity programs and product upgrades that shift feedstock availability, grade mix and lead times.
- Policy and trade frictions: Tariffs and trade remedies in key markets continue to alter landed costs and sourcing strategies.
- Customer demand evolution: End markets (transportation electrification, wind power, infrastructure modernization, and electronics miniaturization) are changing material specifications and tolerances, favoring specialty grades and integrated supply solutions.
High‑Level Market Trajectory — What the Numbers Imply
The headline growth from USD 66.45 billion in 2025 to roughly USD 95.01 billion by 2032 (CAGR 5.24%) masks important strategic nuances that matter to executives:
Glass Fiber Composites Market
- Growth is broad‑based but not uniform. Some end‑use sectors are maturing faster in demand, while others are reshaping product requirements (for example, thermoplastic versus thermoset formulations and high‑performance specialty fibers).
- Moderate industry concentration (CR3 ~38.5%; CR5 ~45.2%) indicates a market where large players retain meaningful leverage, yet mid‑tier and regional suppliers can still win by specializing, integrating downstream, or pursuing cost leadership in targeted geographies.
- Financial and operating models need to reflect multi‑year timelines: given capital intensity and lead times for new lines, companies that lock favorable feedstock contracts and engineered solutions early will secure competitive advantage.
What Corporate Leaders Must Prioritize in 2026
We translate macro forecasts into a concise set of actionable priorities for CEOs, heads of strategy, procurement, and R&D teams:
- Supply‑chain resilience and hedging: With glass fiber prices showing regionally divergent trajectories (e.g., U.S. prices around 1,458 USD/MT in December 2025 and projected to 1,482 USD/MT in Q1 2026; China prices observed near 1,382 USD/MT in Q4 2025 with a short‑term projection to 1,413 USD/MT), commercial teams must re‑assess indexation clauses, strategic safety stock, and multi‑sourcing to protect margins against price volatility.
- Selective capacity expansion vs asset optimization: Public announcements and brownfield investments (examples highlighted in our data set) indicate that new high‑grade and electronic‑grade capacity is coming online. Corporates should model scenarios comparing incremental ROI from adding capacity versus upgrading yields and throughput at existing plants.
- Portfolio tilt to specialty fibers and value‑added services: Demand for performance grades (semiconductor packaging, aerospace interfaces, high‑strength composites) is rising. Targeted product development and closer customer integration (prepreg, pultruded profiles, hybrid laminates) yield higher margin and lower commoditization risk.
- Regulatory and trade playbooks: Persistent anti‑dumping duties and tariff regimes in key jurisdictions require scenario playbooks that combine local production, bonded warehouses, and tariff engineering to sustain competitiveness.
Competitive Landscape — Who Moves the Needle
The competitive map is a mix of diversified industrial conglomerates, dedicated glass fiber manufacturers, and pultrusion specialists. The companies we profile in the full study include multinational incumbents and regional leaders whose recent moves and strategic postures are consequential for market participants. Representative players include:
- Global reinforcers with integrated manufacturing footprints and broad end‑market exposure — leaders in E‑glass and specialty rovings that can scale to serve construction, wind, and transportation volumes.
- Large Chinese producers executing aggressive capacity rollouts, particularly for electronic‑grade and energy‑grade fibers — a dynamic reshaping regional supply balances.
- Specialty fiber manufacturers and pultruders focused on high‑performance niches — including S‑glass and engineered pultruded systems for infrastructure and advanced composites.
Company profiles in the full report include strategic posture, product portfolios, capex timelines, and scenario impact matrices — enabling buyers, potential JV partners and private equity sponsors to calibrate exposure and identify acquisition targets. For confidentiality and to preserve the “trailer” nature of this preview, we selectively present company characteristics here and reserve granular competitive metrics and valuations for the main report.
Recent Developments That Will Shape 2026 Dynamics
- Capacity and product announcements: Recent investments in specialty capacity — for example, an announced expansion to electronic‑grade glass fiber lines and new microfiberglass production facilities — are indicative of supplier priorities toward higher value applications. Such moves compress lead times for specialty grades while creating new competition in those segments.
- Price signals: Raw material price baselines differ across regions and continue to trend modestly upward into early 2026 — a near‑term input pressure that buyers should bake into contract negotiations and price pass‑through models.
- Policy environment: Trade remedies and duties remain active levers in certain markets, driving regional sourcing adjustments and localized production responses.
What’s Inside the Full Report — Practical, Transaction‑Grade Content
Our full study is built for decision speed and operational relevance. Key deliverables include:
- Market sizing and validated growth curves (historical 2020–2025; detailed forecasting 2026–2032) with sensitivity scenarios under alternate demand and raw‑material price paths.
- Segment playbooks — for resin systems, end markets and geographies — showing where to allocate R&D, where to pursue scale, and where partnerships or buyouts are likely to outperform greenfield investments. (Note: detailed sub‑segment financials and percent splits are intentionally available in the full report only.)
- Supplier maps and capacity overlays at a transactional granularity, including planned expansions and likely impact windows for product availability and pricing.
- Procurement templates: contract clauses, indexation strategies, and stock policies calibrated to short‑term price trajectories and long‑term strategic supply alignment.
- M&A playbook and target screening criteria, with scorecards for strategic fit, synergies, and integration risk.
- Regulatory and trade readiness matrix: tailored responses to common duty regimes and environmental product declarations that affect specification and tender outcomes.
Signals to Monitor in 2026 — Early Warning and Opportunity Triggers
- Feedstock and price momentum: Quarterly moves in regional glass fiber pricing and volatility in freight will be the first lever for margin compression or expansion.
- Commissioning of announced lines: The timing and ramp rates of recently announced capacity projects will affect tightness in specialty grades and opportunity windows for premium pricing.
- Policy shifts: Any changes in anti‑dumping measures or tariff rulings in key markets will materially alter trade flows and should trigger immediate sourcing reassessments.
- Customer specification shifts: Accelerated adoption of thermoplastic composites in specific transportation applications or increased use of higher‑performance glass in wind blades will change mix and profitability for producers and converters.
How PW Consulting’s Report Supports Immediate 2026 Actions
For executive teams pursuing quick wins in 2026, the report functions as an operational toolkit: it enables rapid supplier re‑scoping, short‑list generation for targeted acquisitions, CAPEX prioritization models, and procurement negotiation playbooks. For boards and investors, it supplies stress‑tested scenarios that inform valuation multiples and downside protections in transaction documents.
Next Steps — Accessing the Full Intelligence
This release is intentionally framed as a strategic “trailer:” it demonstrates the depth and applicability of our analysis while withholding detailed sub‑segment tables, regional/application splits, and company‑level financials that are included in the licensed report. To obtain the full dataset, proprietary models, supplier maps and the transaction playbook required for 2026 decision execution, please access the complete Glass Fiber Composites Market report from PW Consulting.
Our team stands ready to run bespoke scenario workshops, tailor the procurement templates to your commercial contracts, or provide due‑diligence briefs for potential M&A targets identified in the report. In a market moving at the pace of regulatory change, trade intervention and targeted capacity expansion, timely, operational intelligence will determine who captures the step‑change in value during 2026–2032.
For detailed analysis of this topic, please visit the official page: Glass Fiber Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


