



PW Consulting Forecasts Low‑Powered Electric Motorcycle & Scooter Market to Reach USD 60.92 Billion by 2032

Low Powered Electric Motorcycle and Scooter Market — Strategic Briefing for 2026 Decisions
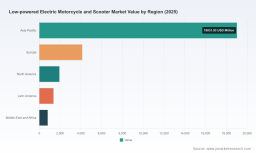
PW Consulting’s latest market research on the Low Powered Electric Motorcycle and Scooter market delivers a forward-looking, execution-focused intelligence package designed to inform board-level strategy and near-term operational choices. Our independent market model shows the global market expanding from roughly USD 27.3 billion in 2025 to approximately USD 60.9 billion by 2032, representing a compound annual growth rate (CAGR) of 12.15% across the 2026–2032 forecast window. This press briefing summarizes the strategic implications for corporate leaders while preserving the granular segment-level tables and company scorecards for subscribers who need transaction-grade detail.
Low Powered Electric Motorcycle And Scooter Market
Why this report matters for 2026
-
Timing: 2026 is a hinge year. Cost declines in key battery components, evolving safety regulation, and the transition of urban mobility policies are converging, creating both runway and risk for incumbents and new entrants.
Low Powered Electric Motorcycle And Scooter Market -
Precision: Executives require models that translate headline CAGR into SKU-level demand, channel economics, and margin sensitivities. Our report couples a transparent market-sizing model with scenario stress-tests calibrated to real commodity and regulatory trajectories.
Low Powered Electric Motorcycle And Scooter Market -
Actionability: Beyond market numbers, the report delivers playbooks on manufacturing footprint optimization, battery strategy (buy vs. build vs. swap), and commercialization roadmaps tailored to fleet, last-mile, and personal-commute use cases.
Market trajectory and macro drivers
The mid-2020s market landscape is shaped by three interlocking dynamics. First, adoption momentum remains robust—our model captures a doubling of market value over the forecast horizon driven by increasing urban electrification and substitution of conventional low-powered two-wheelers. Second, input-cost dynamics are materially supportive: lithium-ion battery pack prices fell by an estimated 20% in 2024, and lithium prices similarly eased, improving supplier margins and lowering breakeven points for new models. Third, regulatory tightening on safety and battery handling—in multiple jurisdictions—raises the bar for product certification and after-sales processes in 2026.
These forces create a dual mandate for companies: accelerate Go-to-Market investments to capture expanding demand while hardening compliance, quality control, and warranty provisioning to avoid reputational and regulatory setbacks.
Competitive landscape — concentrated yet contestable
The market remains moderately concentrated at the top: the three largest groups account for a meaningful share of revenue, and the top five expand that footprint further. This structure produces a competitive field where scale advantages coexist with differentiated opportunities for nimble, software-first newcomers and regionally dominant manufacturers.
-
Yadea Group Holdings Ltd. (China) — a high-volume global producer focused on affordable urban two-wheelers and scale manufacturing. Its cost and distribution advantages make it a defensive leader in mass-market segments.
-
NIU Technologies (China) — focused on smart, connected scooters with IoT integration and battery-swapping propositions; a leader in digital services monetization and urban telematics.
-
AIMA Technology Group (China) — strong play in entry-level models with export orientation and manufacturing breadth.
-
Indian OEMs (Hero Electric, Ather Energy, Ola Electric, TVS, Bajaj) — collectively shaping the region’s rapid electrification with distinct strategies: from premium connected models to rapid-volume, low-cost platforms.
-
Gogoro (Taiwan) — notable for its battery-swapping ecosystem, offering an alternative ownership and infrastructure model that remains attractive in dense urban cores.
-
Global OEMs and specialists (Piaggio/Vespa, Honda, Vmoto Soco, Zero Motorcycles, Sunra) — representing a mix of legacy brand electrification and specialist entries into new price-performance bands.
Recent market signals illustrate shifting competitive playbooks. Zero Motorcycles’ November 2025 unveiling of the LS1 scooter at EICMA signals performance-brand moves into more accessible scooter segments. Sunra’s December 2025 strategic summit emphasized flagship models with Bosch drivetrains and removable lithium-ion batteries—underscoring partnerships between OEMs and tier-1 system suppliers.
Segment dynamics and emerging hotspots
We observe durable demand bifurcation along three axes—product form (scooters vs. motorcycles), battery architecture (removable and swappable packs vs. fixed lithium-ion systems), and end-use (personal commuting vs. commercial/last-mile). Each axis creates distinct margin pools and route-to-market requirements. Importantly, falling battery pack costs are compressing crossover points where higher-spec models become viable at mass-market price points.
Strategic hotspots to watch in 2026 include:
-
Battery ecosystems: Swapping infrastructure versus fast-charging and managed BaaS (Battery-as-a-Service) models; commercial operators and urban municipalities are experimenting with hybrid approaches.
-
Software and telematics monetization: IoT features, OTA updates, and subscription services are a differentiator for margin expansion and fleet management contracts.
-
Fleet electrification and last-mile logistics: While personal commuting continues to dominate unit demand, rapid growth in delivery fleets creates concentrated volume contracts—requiring tailored durability and service models.
-
Compliance and safety engineering: Stricter safety rules for batteries and vehicle classification in 2026 make certification pathways and supplier audits a board-level priority.
What the PW Consulting report contains (practical deliverables)
-
Transparent market model with historical series (2020–2025) and base-year calibration (2025), plus scenario-driven forecasts to 2032. The model is provided in Excel with adjustable levers for battery price, urban penetration, and regulatory tightening.
-
Competitive scorecards for >50 OEMs and strategic supplier maps identifying tier‑1 battery and motor partners, including trade-offs for in-house vs. outsourced battery management systems.
-
Go-to-market playbooks for three archetypes—scale-volume OEMs, premium connected brands, and fleet-focused suppliers—covering pricing, distribution, warranty, and service network design.
-
Regulatory and certification matrix mapping key standards (including applicable NHTSA vehicle rules and UL 2850 safety outlines) across primary markets and the likely 2026–2028 compliance timeline.
-
Supply-chain stress-test suite assessing raw material volatility, logistics disruptions, and component lead-time scenarios, with recommended hedging and nearshoring approaches.
-
Merger & acquisition playbook and valuation benchmarks for strategic buyers and private equity, based on EBITDA multiples adjusted for scale, software revenue share, and BaaS exposure.
Strategic recommendations for 2026
For executive teams planning resource allocation this year, our research supports the following prioritized moves:
-
Revisit battery strategy now. With downward pressure on pack costs, firms that secure flexible supply (mixture of spot purchases, long-term offtakes, and strategic swaps) will sustain margin expansion while reducing time-to-market for higher-spec models.
-
Invest in product safety and certification pipelines. Expect regulators to require stricter battery and vehicle testing; allocate engineering bandwidth and third-party certification budget to avoid market-entry delays.
-
Differentiate via software and fleet solutions. Prioritize connected services that lock in recurring revenue—fleet telematics, predictive maintenance contracts, and BaaS subscriptions materially improve unit economics.
-
Optimize manufacturing footprint for modularity. Adopt platform architectures that allow rapid SKU differentiation while controlling fixed costs; consider contract partnerships in regions with favorable input-cost trends.
-
Target selective partnerships and buyouts. Use the next 12–18 months to pursue small tuck-ins for software firms or battery-ecosystem partners rather than large scale M&A, unless clear synergies in distribution or technology exist.
How to use this intelligence
Leaders should treat the core report as both a predictive tool and an operational playbook. Use the model to run “what-if” scenarios against your product plan, feeding bespoke assumptions on pricing, service costs, and battery economics. Leverage the supplier maps to run accelerated due diligence schedules, and adopt the regulatory matrix to construct a certification roadmap aligned with planned launches.
Because this briefing omits the full segment-level tables and confidential company scorecards, we encourage decision-makers to consult the full PW Consulting report for transaction-level inputs—detailed regional demand splits, SKU-specific margins, and the downloadable forecast model that underpins our public numbers.
Closing
PW Consulting’s Low Powered Electric Motorcycle and Scooter market study combines rigorous macro modeling with hands-on operational advice intended to reduce execution risk in 2026. The market’s projected growth—supported by favorable battery-cost trends but complicated by tightening safety regimes—creates a landscape where the right strategic moves this year can determine winners for the next decade.
For enterprise access to the full data model, company scorecards, and bespoke scenario workshops, please visit the PW Consulting report page or contact our strategy team directly to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


