



PW Consulting: Infrared Light Therapy Devices Market to Grow at a 7.15% CAGR, New Report Forecasts

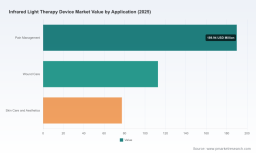
Infrared Light Therapy Device Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Infrared Light Therapy Device Market summarizes the commercial, clinical, and operational intelligence that leaders must act upon in 2026. Built on a 2020–2025 historical base and a detailed 2026–2032 forecast, the report models the market’s trajectory from a 2025 base of USD 380.0 Million to a projected USD 616.32 Million by 2032, representing a compound annual growth rate (CAGR) of 7.15%. This briefing distills the report’s strategic value while intentionally withholding segment-level figures — a preview designed to show analytical depth and operational utility, and to guide you to the full dossier for transaction-grade detail.
Infrared Light Therapy Device Market
Why 2026 Is a Pivotal Year
-
Transition from consumer wellness to clinical adoption: 2026 marks an inflection in buyer sophistication. Devices are moving beyond lifestyle claims toward regulated clinical indications, clinical partnerships, and reimbursement visibility.
Infrared Light Therapy Device Market -
Regulatory clarity and reimbursement mechanics are converging: ongoing Class II device pathways and CPT-level coverage create practical go/no-go tests for new products entering the market.
Infrared Light Therapy Device Market -
Component economics and scale effects will determine margin winners: LED sourcing and BOM structure materially influence unit economics and strategic positioning in the mid-term.
What the Report Contains — Practical, Transaction-Ready Output
-
Comprehensive market sizing and trend model (2020–2032) with scenario variants (base, upside, downside) for planning and valuation.
-
Go-to-market playbooks tailored to product archetypes (portable, wearable, full-body, clinical bed) covering channel selection, pricing frameworks, and service models.
-
Regulatory roadmap templates for 510(k)/Class II clearances and label strategy aligned to claims (pain, wound care, dermatology), including timelines and evidence requirements.
-
Reimbursement impact analysis, mapping CPT codes and payer levers to revenue paths for clinics and outpatient providers.
-
Supplier and cost model with transparency on key BOM drivers (including LED unit costs and their share of manufacturing cost), plus alternative sourcing options and risk mitigants.
-
Competitive benchmarking and company scorecards that synthesize capability in product engineering, regulatory evidence, go-to-market strength, and partnership potential.
-
M&A and partnership scan with prioritized targets and valuation frameworks for roll-up, distribution partnerships, and OEM strategies.
Market Dynamics & Key Drivers
-
Demand drivers: growing clinical evidence for pain management, wound healing and aesthetic indications; consumer wellness adoption; and integration into athletic recovery and rehab programs.
-
Regulatory environment: non-invasive infrared devices are widely treated as Class II in key markets, with 510(k) pathways required for pain relief indications under applicable device codes. Manufacturers must map device claims to FDA guidance and plan for associated premarket submissions.
-
Reimbursement and utilization: physical therapy billing frameworks (including CPT code 97026 for infrared therapy) offer practical reimbursement pathways in certain care settings; however, capture depends on coding discipline and documented clinical workflows.
-
Cost structure pressures: high-power, medical-grade LEDs — particularly at higher near-infrared wavelengths — continue to represent a significant portion of BOM cost. Our analysis shows these components can account for a substantial single-digit to low double-digit percentage of device manufacturing cost and remain a primary lever for margin improvement.
-
Concentration and competitive dynamics: the market remains fragmented with modest top-tier concentration (our market concentration metrics indicate relatively low CR3 and CR5 shares), creating runway for differentiated entrants and consolidation plays.
Competitive Landscape — Strategic Implications
The competitive field blends fast-moving consumer-focused brands, medically oriented device makers, and clinical-system suppliers. Several archetypes stand out:
-
Direct-to-consumer innovators with clinical aspirations — companies offering modular or portable panels and wearables focused on recovery and wellness. These players leverage strong marketing, modular design, and emerging FDA engagement to accelerate adoption in home and semi-clinical settings.
-
Clinically oriented solution providers — manufacturers of whole-body beds and professional devices that partner with hospitals and sports medicine networks, emphasizing certified workflows and institutional procurement processes.
-
Hybrid manufacturers that combine strong engineering (high-power LEDs, optimized wavelengths) with regulatory clearances and clinical studies to target both consumer and clinical channels.
Representative company moves and their strategic signals:
-
Product innovation at higher wavelengths: recent launches increasing near-infrared output indicate a R&D focus on tissue penetration and therapeutic efficacy. Firms amplifying output are effectively targeting clinical endpoints where penetration depth matters.
-
Regulatory momentum: FDA Class II clearances for portable OTC devices highlight a pathway for scaling consumer adoption while maintaining clinical credibility; expect more product clearances to shape channel economics in 2026–2027.
-
Clinical evidence investment: published studies demonstrating significant symptom reduction in targeted populations materially support payor conversations and clinician adoption; companies with defensible study programs gain pricing leverage.
-
Distribution partnerships with hospital systems signal a push into institutional channels and a move to secure recurring consumption and higher ASPs (average selling prices).
Strategic Playbook for 2026 Decision-Makers
-
Prioritize regulatory-first product roadmaps. For any new device launch in 2026, build the 510(k) pathway and associated clinical endpoints into product development timelines from day one; post-market evidence plans should be budgeted as core GTM spend, not optional.
-
Invest selectively in clinical evidence that unlocks reimbursement. Targeted single-indication, well-powered clinical trials (e.g., for arthritis or wound adjunct therapy) deliver the fastest ROI in payer and institutional procurement discussions.
-
Optimize BOM by locking preferred LED suppliers and negotiating volume tiers. Given the outsized role of high-power LEDs in manufacturing cost, secure multi-year agreements or explore vertical integration where economics permit.
-
Adopt hybrid channel strategies. Combine DTC brand momentum with credentialed clinical distribution to capture both consumer wallet-share and institutional reimbursement — structuring offerings by service level (consumer, clinic, hospital).
-
Design service and subscription models. Shift part of the value capture to recurring service (protocol subscriptions, device-as-a-service for clinics) to stabilize revenue and increase LTV.
-
Screen M&A for capability gaps. Acquisitions should be evaluated for regulatory clearance assets, clinical study portfolios, channel reach, or proprietary LED/optical engineering rather than broad market share only.
-
Plan for scenarios: build three-year financial models that stress-test reimbursement rollouts, LED cost inflation, and speed-to-clearance. Use these to set contingency capital buffers and prioritization gates.
Scenario Outlook & Key Sensitivities
Our baseline forecast, reflecting a 7.15% CAGR through 2032, assumes steady clinical adoption, incremental regulatory approvals, and moderated LED cost inflation. Upside scenarios accelerate with faster payer acceptance and wider institutional deployments; downside scenarios arise from restrictive claims enforcement or supply-chain shocks in LED supply.
Key sensitivities to monitor in 2026:
-
Regulatory rulings that tighten or broaden permitted claims.
-
Reimbursement policy shifts, including local payer coverage decisions and utilization limits tied to clinical codes.
-
Raw material pricing volatility for medical-grade LEDs and optics.
-
M&A activity that changes competitive concentration and distribution control.
How Executives Should Use the Full Report
-
Download the full report to access transaction-ready datasets: segment-level forecasts, pricing curves, product archetype P&L, supplier cost breakouts, and company scorecards that underpin the analysis summarized here.
-
Use the included regulatory templates and clinical evidence playbooks to align R&D budgets and commercialization timelines with anticipated 2026 submission windows.
-
Engage PW Consulting for tailored advisory: scenario modeling for specific product proposals, vendor negotiation support for LED procurement, or M&A diligence focused on clinical evidence and regulatory positioning.
Closing thought: the infrared therapy device market is maturing from a fragmented, innovation-led field into a strategically contestable space. Companies that align product design with regulatory pathways, secure cost-advantaged supply, and invest in targeted clinical evidence will capture disproportionate upside as the market scales from 2026 onward.
— PW Consulting, Senior Strategy Consultant & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


