



PW Consulting: Hirschsprung Disease Drug Market to Reach USD 683.08 Million by 2032 — 2026–2032 Forecast at 5.01% CAGR

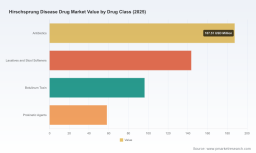
Hirschsprung Disease Drug Market: Strategic Outlook for 2026 — PW Consulting Briefing
As the landscape for Hirschsprung disease therapeutics approaches a pivotal inflection, PW Consulting publishes a focused strategic briefing derived from our full Hirschsprung Disease Drug Market report (base year 2025, forecast 2026–2032). This preview synthesizes the macroeconomic trajectory, competitive inflection points, regulatory dynamics and the commercial imperatives that should shape corporate decisions in 2026. Our purpose here is to establish the analytical frame and the operational questions executives need answered now — while guiding you to the full report for the granular segmentation and modeling that underpins confident action.
Hirschsprung Disease Drug Market
Macro snapshot: a compact market with asymmetric upside
Between 2020 and 2025 the global Hirschsprung disease drug market expanded meaningfully, reflecting an active treatment and post‑surgical management ecosystem. In 2025 PW Consulting’s base valuation places the market at approximately USD 485 million, and our consolidated forecast projects a steady compound annual growth through 2032 (CAGR ~5.01%), reaching roughly USD 683 million by the end of the forecast window. These figures describe a market that is small relative to broad therapeutic areas but large enough to fund specialized R&D and to attract strategic interest from orphan‑disease investors, pediatric specialty biotechs and select large pharma franchises seeking differentiated pediatric assets.
Hirschsprung Disease Drug Market
Two implications flow from the numbers: first, clinical and regulatory milestones — not mass volume alone — will drive valuation and commercial opportunities; second, the market structure supports premium pricing for first‑in‑class disease‑modifying therapies while maintaining ongoing demand for supportive care products. The result is an asymmetric opportunity: modest absolute market size but outsized value creation potential around novel curative or disease‑modifying approaches.
Hirschsprung Disease Drug Market
Why 2026 is a strategic inflection year
2026 represents a calendar in which scientific progress, regulatory momentum and commercial preparations converge. A tangible example: NEU‑001 — a first‑in‑class intrarectal combination therapy in development by Neurenati Therapeutics Inc. — received FDA Orphan Drug and Rare Pediatric Disease designations in March 2025 and EMA Orphan Drug designation in October 2025. NEU‑001’s pathway puts human trials on the horizon in 2026, and a successful entry to clinical development will reframe the competitive narrative.
Importantly, no pharmacologic therapy that modifies the underlying enteric nervous pathology of Hirschsprung disease is currently approved; current drug use remains focused on supportive management of complications such as Hirschsprung‑associated enterocolitis and post‑surgical bowel dysfunction. Standard management protocols continue to reference antibiotics combined with rectal irrigations for HAEC, and laxatives or botulinum toxin injections are routinely used for bowel management. The arrival of a therapy intended to regenerate enteric neurons would therefore shift treatment paradigms — with attendant downstream effects on trial design, payer appraisal and provider adoption.
Report scope — what decision‑makers will find in the full study
- Forward‑looking market sizing and consolidated forecasts (2020–2032) with scenario modeling that isolates base, accelerated and disruption pathways under alternate launch and reimbursement conditions.
- Competitor and pipeline mapping covering clinical stage, mechanism of action, regulatory designations and likely commercial windows — including detailed profiles and strategic options for emerging first movers.
- Regulatory and reimbursement playbooks: analysis of orphan drug incentives, pediatric design considerations, and payer evidence requirements across major jurisdictions.
- Commercial launch readiness tools: segmented go‑to‑market templates, provider engagement roadmaps, hospital procurement dynamics, and channel optimization frameworks.
- Operational checklists for manufacturing scale‑up, pediatric CMC risk mitigation, and clinical supply strategies tailored to small patient populations.
- Transaction and investment diligence modules: valuation sensitivities, M&A comparators, partnership archetypes and a proprietary market concentration assessment.
- Primary research inputs: KOL interviews, hospital pharmacy purchasing patterns, and payer sentiment analysis that anchor quantitative forecasts to on‑the‑ground realities.
To preserve the strategic value of this briefing and to comply with our “trailer” principle, we have intentionally omitted granular regional and product‑class splits here; the full report contains the detailed matrices and downloadable models that enable executable 2026 strategies.
Competitive dynamics and the rise of first‑in‑class entrants
Our concentration analysis reveals a market that is moderately distributed: the top few participants account for a material but not dominant share of the overall market, leaving white space for well‑executed entrants with differentiated clinical profiles. This structure favors innovators that can demonstrate durable clinical benefit and align early with pediatric specialists, surgical centers and payer decision frameworks.
Neurenati Therapeutics Inc., headquartered in Montreal, is illustrative of the new‑era entrant. Their investigational product NEU‑001 is positioned as an intrarectal, neurotrophic growth factor‑based therapy intended to regenerate the enteric nervous system — fundamentally different from current supportive treatments. Regulatory milestones attained in 2025 accelerate the timeline for clinical data generation and create a potential first‑mover advantage if human studies validate safety and efficacy. For incumbent suppliers of antibiotics, laxatives and botulinum toxin therapies, the strategic question becomes one of portfolio diversification: pursue licensing or acquisition of novel assets, partner on evidence generation, or double down on complementary care bundles that will remain necessary during and after any disease‑modifying therapy’s introduction.
Commercial and payer considerations
Orphan and rare pediatric designations reshape commercial dynamics. They typically shorten regulatory timelines, offer market exclusivity advantages and, in some jurisdictions, enable premium pricing environments — but they do not remove payer scrutiny. Payers will demand robust pediatric efficacy data, safety over modest patient cohorts, and health economic models that reconcile upfront therapy costs with avoided long‑term resource utilization (reduced hospitalizations for HAEC, fewer surgical interventions, diminished lifelong bowel management needs).
Channels of care — hospital pharmacies, specialist clinics and evolving online pharmacy models — each present unique contracting, reimbursement and logistics requirements. Manufacturers must prepare differentiated channel strategies that reflect pediatric cold‑chain handling, hospital formulary dynamics, and the need for education and support programs for caregivers. Generating real‑world evidence from registries and payer data will be essential to secure coverage and to manage value‑based contracting conversations.
Priority recommendations for corporate leaders in 2026
- Establish early clinical and regulatory alliances. Engage pediatric surgery and gastroenterology KOLs to co‑design adaptive pediatric protocols that address both efficacy and real‑world applicability.
- Lock in payer evidence plans prior to pivotal trials. Map long‑term cost offsets (hospitalizations, surgical revisions, chronic management) and design HEOR studies that can be delivered alongside clinical development.
- Create an acquisition and partnership shortlist. For incumbents in supportive care, identify 1–3 biotech targets or platform technologies that could accelerate entry into disease‑modifying space.
- Prioritize manufacturing and CMC risk mitigation for pediatric formulations. Early investments in pediatric‑friendly delivery systems and scalable CMC pathways reduce launch friction.
- Design pilot reimbursement constructs. Work with health systems on pilot access programs or outcomes‑based arrangements that de‑risk initial market entry and build utilization evidence.
- Build a cross‑functional launch task force now. Integrate clinical, regulatory, HEOR, commercial and patient advocacy leadership to compress the time from approval to meaningful patient access.
- Allocate capital for post‑launch RWE and registry investments. Lifelong follow‑up data will be decisive in longer‑term payer assessments and guideline updates.
How PW Consulting supports 2026 decision‑making
PW Consulting offers tailored advisory that converts the high‑level insights in this briefing into executable 90‑, 180‑ and 360‑day playbooks. Our services include bespoke market models calibrated to your asset’s profile, due diligence support for licensing and M&A, regulatory strategy workshops focused on pediatric pathways, payer engagement simulations and launch readiness assessments that stress‑test supply, distribution and training plans.
The full Hirschsprung Disease Drug Market report contains the detailed regional and product‑class splits, downloadable financial models in USD (revenue unit: Million), competitive scorecards, and playbooks referenced above. These deliverables are designed to bridge the gap between boardroom strategy and field execution — allowing leaders to act with precision in 2026 while preserving optionality for multiple development and reimbursement scenarios.
Closing: a compact market demanding decisive, evidence‑led moves
The Hirschsprung disease therapeutic arena exemplifies a rare‑disease market where clinical innovation, regulatory incentives and commercial discipline converge. The market’s modest absolute size belies the strategic stakes: a single positive clinical program that demonstrably modifies disease course can reprice the entire landscape. For 2026, the imperative is clear — align clinical design with payer‑oriented evidence generation, prepare operational pathways for pediatric launches, and pursue targeted partnerships that accelerate both science and access.
PW Consulting’s full report delivers the granular segmentation, scenario models and operational playbooks necessary to pursue those paths. Contact our team or visit the report page to access the in‑depth datasets and advisory services that will turn 2026 choices into durable advantage.
For detailed analysis of this topic, please visit the official page: Hirschsprung Disease Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


