



PW Consulting: 14430 Cylindrical Lithium‑Ion Battery Market Poised to Grow at 5.85% CAGR in 2026–2032 with Asia‑Pacific in the Lead

14430 Cylindrical Lithium‑Ion Battery Market — Strategic Insights for 2026 Decision‑Making
Executive summary
PW Consulting’s 14430 Cylindrical Lithium‑Ion Battery Market study (base year 2025) delivers a decision‑grade view for executives preparing strategy and capital allocation plans in 2026. The market, which reached roughly USD 115 million in 2025, is forecast to expand through the 2026–2032 horizon at a 5.85% compound annual growth rate to an estimated USD 171 million by 2032. Market concentration metrics indicate a mid‑to‑highly consolidated supply base (CR3 ≈ 48.5%, CR5 ≈ 62.2%), a structure that favors established suppliers but still leaves room for focused challengers and specialized niche plays.
14430 Cylindrical Lithium Ion Battery Market
Why this report matters for 2026
-
Timely alignment: 2026 will be a pivotal year as raw‑material volatility and regulatory shifts reshape sourcing and pricing. Our report translates those macro shifts into supplier‑level risk and cost implications for 14430 cell users.
14430 Cylindrical Lithium Ion Battery Market -
Actionable risk management: We map short‑term disruptions (tariff adjustments, export controls) into mitigations—dual sourcing, inventory strategies, contractual protections—that procurement and supply‑chain teams can implement within quarters, not years.
14430 Cylindrical Lithium Ion Battery Market -
Product positioning and roadmap: For product, engineering and business‑development leaders, we translate chemistry, form factor and certification differentials into go‑to‑market options and win themes for consumer, industrial and regulated device segments.
-
Deal support: For corporate development and private equity, the report is structured to enable fast screening of acquisition targets and JV partners using standardized scorecards and valuation scenarios tied to realistic market trajectories.
What’s inside — practical, execution‑oriented content
-
Market sizing and forward scenarios: A base forecast with upside/downside scenarios reflecting raw‑material shocks, accelerated LFP adoption and demand elasticity for portable‑power devices.
-
Supplier scorecards and differentiation frameworks: Standardized assessments of technical capability, certification and quality systems, manufacturing footprint sensitivity, and supply reliability.
-
Total cost of ownership (TCO) models: Cell cost, pack integration economics, warranty exposure and end‑of‑life recycling credits are modeled across buyer archetypes.
-
Regulatory and trade impact briefings: Practical checklists and contract clause templates to mitigate tariff and export‑control exposure introduced in 2025–2026 regulatory actions.
-
Go‑to‑market playbooks: Product launch and channel strategies by application archetype, including certification roadmaps and test‑validation timelines for medical and regulated devices.
-
M&A and partnership pipeline: A prioritized shortlist of provider archetypes with valuation multipliers and integration risk flags for deal teams to pursue.
Key market dynamics shaping 2026 strategy
Three industry currents dominate the decision calculus for 14430 cells in 2026:
-
Raw‑material volatility and chemistry mix shifts. Despite a broader decline in pack prices in 2025 driven by manufacturing efficiency and greater LFP adoption, upstream commodity price swings—most notably a late‑2025 rebound in lithium carbonate and ongoing cobalt supply tightness following export controls—raise margin risk for chemistries reliant on nickel/cobalt inputs. Buyers must evaluate chemistry exposures across their product portfolio and quantify sensitivity to commodity scenarios.
-
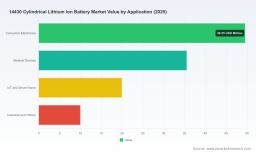
Demand re‑profile and application evolution. Global battery demand surged in 2025, with pronounced growth in LFP and energy storage segments. For the 14430 form factor this means a bifurcation: continued traction in compact, high‑cycle consumer and medical devices, while new use cases (IoT, smart sensors, portable medical units) require tighter safety and cert compliance. Product teams should prioritize cell selection matrices that balance energy density against lifecycle and certification needs.
-
Regulatory and trade headwinds. Recent executive actions adjusting reciprocal tariffs and export quotas introduced late in 2025 materially affect cross‑border sourcing economics and lead times. Buyers need playbooks for tariff pass‑through, origin re‑routing and contingency qualification to avoid single‑sourcing exposure during 2026 procurement cycles.
Competitive landscape — how to read supplier positioning
The 14430 supply base today blends legacy manufacturers and specialized Chinese producers. Instead of naming every product spec, contemplate supplier archetypes and what each brings to a 2026 sourcing strategy:
-
Tier‑A diversified electronics groups: Firms with broad product portfolios and rigorous safety systems tend to command premium pricing and shorter qualification tail risk. Their recent safety documentation updates underscore an emphasis on compliance and differentiated risk management—attributes attractive to medical and other regulated device OEMs.
-
Contract‑manufacturing and pack specialists: Suppliers that focus on custom packs and capacity variants offer agility in tailoring solutions for OEMs that need unique form‑factor or high‑rate variants. For companies aiming to accelerate time‑to‑market, these suppliers reduce integration risk but may require tighter IP and quality governance.
-
Niche commodity players: Producers emphasizing competitive pricing and energy density often target high‑volume consumer and power‑tool segments. Their strengths are cost and scale; their weakness is often slower product certification timelines and greater exposure to commodity swings.
Recent supplier activities are instructive: a handful of firms refreshed product documentation and industry guides in late 2025 and early 2026, signaling a focus on transparency, SDS updates and channel education—an indicator that safety and specification clarity will be competitive levers through 2026.
Strategic recommendations for executives in 2026
-
Quantify chemistry exposure now. Build a short, medium and long‑term P&L sensitivity to lithium carbonate and cobalt price scenarios and stress‑test your product roadmap against LFP migration and density trade‑offs.
-
Dual‑source and localize critical nodes. Where tariffs and export constraints intersect with long lead times, create prioritized dual‑sourcing strategies and assess nearshoring or regional warehousing to blunt transit and customs risk.
-
Prioritize certification and SDS governance for regulated end uses. Medical and other regulated applications increasingly select suppliers with up‑to‑date safety documentation and certification footprints; accelerate vendor audits and naming conventions to compress qualification windows.
-
Use supplier scorecards in procurement negotiations. Shift discussions from price per cell to TCO metrics (cycle life, capacity fade, warranty exposure) to secure contracts that reflect whole‑life economics rather than headline unit price.
-
Monitor consolidation opportunities. The market concentration profile suggests value in targeted M&A for acquiring technical IP or expanding capacity in high‑growth niches; use our valuation templates to rapidly screen targets.
How PW Consulting’s report equips your 2026 roadmap
Our 14430 market study is purpose‑built for executives who require fast, executable intelligence rather than broad generalities. Clients receive:
-
Decision matrices that convert market scenarios into prioritized actions by function (Procurement, R&D, BD, Legal).
-
Supplier scorecards and qualification checklists that compress vendor selection cycles from months to weeks.
-
TCO and NPV tools pre‑loaded with market assumptions and sensitivity levers you can adapt to internal forecasts.
-
A regulatory impact appendix summarizing recent trade and export developments and practical contractual language to mitigate exposure.
Note: the report deliberately keeps certain granular segment tables and supplier price curves gated behind the full report because those are often the most material inputs to commercial negotiation and M&A diligence. Access to the full dataset and downloadable models is available on the report landing page for verified purchasers.
Next steps
For 2026 planning cycles, time and clarity matter. Start with a short engagement: a 2‑week supplier‑risk triage that maps your current buy profile to the market scenarios in this report. For teams preparing larger strategic moves—product launches, capacity investments or deals—we provide deep‑dive workshops that convert our findings into a 12‑month execution plan.
Contact PW Consulting to secure access to the full 14430 report and the accompanying toolset that turns numbers into executable decisions for 2026.
For detailed analysis of this topic, please visit the official page: 14430 Cylindrical Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


