



PW Consulting Report: Smart Transmitter Market Poised to Expand at a 5.4% CAGR Through 2032

Smart Transmitter Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As industrial automation accelerates toward higher degrees of digitalization, the smart transmitter market emerges as a critical enabler of safer, more efficient, and more resilient operations. PW Consulting’s forthcoming Smart Transmitter Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—delivers an actionable intelligence package designed to shape capital allocation, vendor strategy, and product roadmaps for the 2026 decision cycle.
Smart Transmitter Market
Why 2026 is a Pivotal Year for Decision-Makers
After steady expansion through the early 2020s, the global smart transmitter market is positioned for continued, mid-single-digit growth. Our model, calibrated against historical performance through 2025, assesses the market’s structural drivers and projects the trajectory across the forecast period. With an enterprise-level compound annual growth rate (CAGR) of approximately 5.4% from 2026 onward, the market’s scale and momentum will materially influence procurement windows, R&D timing, and M&A windows in 2026. For C-level executives and portfolio managers, the report translates this macro trajectory into timelines for capital deployment and technology refresh cycles.
Smart Transmitter Market
What the Report Contains — Practical, Decision-Ready Content
This report goes beyond headline figures. It is organized to support strategic and operational decisions with granular tools and executable guidance while preserving commercial sensitivity where appropriate. Key practical deliverables include:
Smart Transmitter Market
- Market sizing and directional growth drivers at the market level (base year 2025), with a scenario suite that tests demand elasticity under alternate macro and regulatory outcomes for 2026–2032.
- Supply-chain heatmaps and a risk register that quantify lead-time exposure, critical component bottlenecks (including semiconductor availability), and mitigation options such as dual-sourcing, contract hedging, and onshore buffer strategies.
- Vendor performance scorecards that benchmark product portfolios on digital features, diagnostics, interoperability standards support, and service economics—designed for quick shortlisting in procurement RFx processes.
- Go-to-market playbooks for both incumbent manufacturers and new entrants, with tailored commercial models (capex vs. opex, subscription-based services, and lifecycle services) and channel strategies for 2026 rollout plans.
- Regulatory and standards impact analysis with compliance timelines and an implementation checklist—essential for engineering, QA, and procurement teams planning 2026 upgrades.
- Financial decision tools including TCO models, payback calculators for IIoT-enabled retrofits, and M&A screening matrices to prioritize targets by strategic fit and accretive potential.
Market Structure and Competitive Dynamics — What to Watch
The market shows a moderate degree of concentration: a cluster of established multinational instrument and automation suppliers holds a material share of global revenues. This concentration creates both stability in technology roadmaps and competitive windows for specialized players to capture differentiated segments through verticalization or regional service excellence.
Key competitive observations:
- Legacy automation and instrumentation leaders continue to consolidate value by integrating smart transmitters into broader digital-plant platforms. Their advantages include installed bases, aftermarket service networks, and integration expertise with process control systems.
- Product differentiation is increasingly driven by digital capabilities—advanced diagnostics, native support for fieldbus and industrial Ethernet standards, and secure IIoT connectivity—rather than by hardware precision alone.
- Regional and niche vendors remain important for customers seeking low-cost, high-precision solutions, or rapid local service; these vendors often win in retrofit or non-critical applications.
- Market entry opportunities exist for specialized providers offering lifecycle services (predictive maintenance as a service), retrofit conversion kits, and cybersecurity-hardened field devices tailored to regulated industries.
Company-Level Insights — Strengths and Strategic Postures
The report’s vendor analysis evaluates leading and emergent players across product breadth, digital roadmap, service reach, and operational resilience. Highlights include:
- Emerson Electric Co.: Deep portfolio breadth across pressure, temperature, and level transmitters, with strong support for HART, FOUNDATION Fieldbus, and wireless protocols. Emerson’s installed base and software integration capabilities make it a go-to partner for large-scale modernization programs.
- ABB Ltd.: Strong engineering focus on high-performance pressure measurement and an active product renewal cadence. Recent new-product previews signal continued investment in ultra-accurate transmitters optimized for process optimization and utility applications.
- Yokogawa Electric Corporation: Emphasis on advanced diagnostics and reliability in process industries; well-positioned where uptime and measurement integrity are priority selections.
- Honeywell International Inc. and Siemens AG: Both leverage extensive automation portfolios to drive transmitter adoption as part of broader IIoT and automation projects, with emphasis on predictive maintenance and systems integration.
- Endress+Hauser and WIKA: Pivotal players for customers insisting on instrument-level interoperability and modern fieldbus options such as Ethernet-APL; strong reputations in calibration and lifecycle services.
- Schneider Electric: Brings process-control integration via established brands and offers competitive aftermarket services.
- Specialists and regional vendors (e.g., Duon System, ASCON TECNOLOGIC, BD|SENSORS, GEORGIN): Often agile on customization and price, these firms remain strategic for retrofit programs, regional projects, and OEM partnerships.
For procurement and strategy teams, the competitive mapping in the report includes vendor heatmaps, innovation roadmaps, and supplier risk scores designed to accelerate shortlist formation and contract negotiations in 2026.
Standards, Regulation, and Supply-Chain Headwinds
Regulatory and standardization developments will materially influence certification timelines and integration choices. Among the developments we model and assess are:
- Updated test procedures and verification expectations affecting pressure transmitters, which increase validation workloads for manufacturers and could extend lead times for certified lines.
- Revisions to measurement management system standards impacting calibration regimes and QA practices—requiring suppliers and end-users to re-evaluate maintenance intervals and associated cost models in their 2026 budgets.
- Emerging transducer interface standards that enable richer device descriptions and mixed-mode communications, facilitating plug-and-play capabilities but also imposing new compliance tasks for legacy systems.
- Industry adoption of Ethernet-APL and similar digital fieldbus technologies, which accelerate digital integration but also demand changes in plant network architecture and cybersecurity posture.
- Geopolitical and trade-related pressures on semiconductor supply chains: export controls and constrained advanced-chip availability are modeled as a direct input to lead-time scenarios and inventory strategies.
Our scenario analysis quantifies how different regulatory and supply scenarios alter procurement lead times, TCO, and retrofit economics—critical inputs for 2026 capital planning.
Strategic Recommendations for 2026 (Executive Summary)
Based on our analysis, PW Consulting recommends the following strategic moves for organizations planning product, procurement, or investment decisions in 2026:
- Prioritize interoperability and standards compliance in procurement specs. Devices that natively support next-generation fieldbus standards will reduce integration costs and futureproof systems.
- Adopt a diversifying sourcing strategy for critical components—especially semiconductors—combining strategic stockpiles with dual-sourcing agreements to insulate production from geopolitical shocks.
- Shift commercial models toward lifecycle-oriented contracts that embed predictive-maintenance services; these lower total cost of ownership and create recurring revenue for suppliers.
- Accelerate pilot deployments of Ethernet-enabled field devices with clear ROI checkpoints to build internal capabilities for broader IIoT rollouts in 2027–2028.
- For investors and acquirers: prioritize targets that offer differentiated software services, strong service footprints, or niche product excellence—these are the most likely to unlock synergies with incumbent portfolios.
- Integrate standards and regulatory-update monitoring into procurement and QA functions to avoid certification-related delays and unplanned retrofit costs.
How PW Consulting’s Report Serves 2026 Decisions
This report is deliberately structured as a “strategy-to-execution” kit for 2026. It connects high-level market projections—anchored in a rigorous historical base and a 5.4% modeled CAGR—with practical levers: supplier selection frameworks, risk-mitigated sourcing plans, and operational playbooks for IIoT adoption. The deliverable package includes interactive models and decision-support tools that procurement, product, and corporate development teams can apply directly to their 2026 planning cycles.
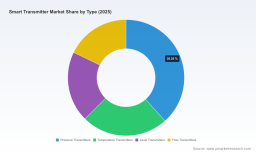
To preserve the competitive value of our primary datasets and scenario outputs, the public summary intentionally omits granular segment-by-segment figures and certain proprietary vendor score details. These are available in full through the report’s subscription and licensing options, which include raw datasets, vendor-level scorecards, and customizable TCO calculators.
Next Steps and Access
For executives preparing 2026 capital plans, procurement cycles, or M&A pipelines, receiving the full report and model packages is the most effective way to convert these insights into operational decisions. PW Consulting’s advisory teams are available for bespoke briefings, supplier shortlists, and deep-dive workshops that translate the report’s findings into implementation roadmaps tailored to your organization.
Contact PW Consulting to schedule an executive briefing and obtain access to the full Smart Transmitter Market report, interactive models, and the complete vendor benchmarking dataset.
For detailed analysis of this topic, please visit the official page: Smart Transmitter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


