



PW Consulting Report: Cartridge Systems Market Poised to Grow at a 5.04% CAGR Through 2032

Cartridge Systems Market: Strategic Imperatives for 2026—A PW Consulting Preview
PW Consulting’s latest industry brief on the global Cartridge Systems Market synthesizes multi-year market dynamics, supplier positioning, commodity pressures, and technological inflection points to deliver actionable intelligence for executives planning 2026 strategies. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study combines rigorous quantitative modeling with playbook-style recommendations to help C-suite and business unit leaders prioritize investments, mitigate risks, and capture growth across pharmaceutical, industrial, and specialty applications.
Cartridge Systems Market
Market trajectory at a glance
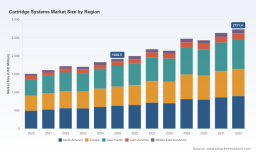
The cartridge systems market has expanded steadily since 2020, recovering from pandemic-era distortions and evolving through incremental product and process innovation. PW Consulting’s modeling shows a market base just under USD 2.0 billion in 2025, and a continued expansion through the forecast window to exceed USD 2.7 billion by 2032. The implied compound annual growth rate for the 2026–2032 forecast period is 5.04%, reflecting a balance of demand drivers across injectable primary packaging, industrial dispensing, and specialty two‑component systems.
Cartridge Systems Market
Noteworthy in the historical series is a phase of volatility rather than secular decline—periods of modest contraction interspersed with renewed expansion—underscoring the sensitivity of cartridge demand to end‑market cycles (pharma launches, construction activity, electronics assembly) and to raw material and processing bottlenecks. That pattern both creates risk and opens tactical windows for incumbents and newcomers who can time capacity, pricing, and innovation correctly.
Cartridge Systems Market
Why this report matters for 2026 decision-making
- Precision under uncertainty: The report translates top-line projections into operational levers—capacity timing, fill/finish automation investment thresholds, and sourcing alternatives—so executives can convert market forecasts into capital and procurement decisions timed to 2026 budget cycles.
- Cost-to-competitiveness mapping: We quantify the seat‑of‑the‑pants impact of raw material swings on unit economics and provide hedging and specification-change scenarios that preserve margin even under sustained resin or elastomer price pressure.
- Regulatory and sustainability readiness: As sustainability requirements become procurement prerequisites—especially in pharma and large industrial OEMs—the report lays out compliance pathways and cost-to-benefit tradeoffs for recycled content, paper-based substrates, and RTU (ready-to-use) formats.
- Dealflow and partnership playbook: The intelligence package includes screens for M&A and JV targets, integration checklists, and commercial due-diligence templates tailored to cartridge-related assets and adjacent packaging capabilities.
Core strategic implications
- Portfolio calibration: Firms should prioritize modular product lines that allow flexible transitions between single-component dispensing and multi-component systems; the report helps identify break-even points where investments in 2K capability or RTU filling deliver disproportionate commercial returns.
- Supply-chain resilience: With plastics PPI and regional resin price differentials creating uneven cost pressure, the practical guidance recommends dual-sourcing strategies, regional inventory buffers, and selective onshoring of critical components to maintain service levels while controlling landed cost.
- Sustainability as a revenue lever: Early movers on PCR/PIR usage, paper-based formats, and low‑carbon supply chains are better positioned to win contracts from sustainability-driven procurement organizations; our scenarios quantify payback windows for such investments under realistic purchase timelines.
- Service and integration: Beyond the component sale, offering RTU filling, sterilization partnerships, or integrated dispensing systems materially increases customer stickiness—our commercial models show how service bundling lifts lifetime value.
Competitive landscape—what the leading players are signaling
The competitive geometry of the cartridge systems market includes legacy pharmaceutical glass specialists, industrial-dispensing innovators, and packaging incumbents expanding into adjacent niches. Market leadership is distributed: a small group of global manufacturers exert meaningful influence over standards and high‑value accounts, while a broader set of regional and specialty suppliers compete on price, customization, or service.
- Stevanato Group (Piombino Dese, Italy): A long-established leader in pharmaceutical glass cartridge systems and parenteral packaging. Stevanato’s decades of glass expertise and investments in drug-delivery formats (including pen and auto-injectors) position it as the primary reference for biologics and high-value drugs. For competitors, collaboration or differentiation will be required—either by targeting non‑sterile industrial applications or by offering superior RTU and secondary packaging solutions.
- SCHOTT AG (Mainz, Germany): A supplier with strong credentials in sterile containment and high-quality primary packaging. SCHOTT’s emphasis on containment and material science makes it a preferred partner for complex biologics; strategy for challengers should focus on niche differentiation (e.g., sustainability, rapid prototyping, or price performance for high-volume industrial uses).
- West Pharmaceutical Services (Exton, Pennsylvania, USA): Strong in containment systems, elastomers, and integrated delivery solutions. West’s systems-oriented approach highlights the commercial premium for end-to-end compatibility and validated supply chains; rivals can compete by offering lower TCO through onshore manufacturing and faster regulatory support.
- Gerresheimer AG (Düsseldorf, Germany): A hybrid player providing both glass and plastic cartridge options, enabling cross‑sell into existing pharma packaging relationships. Their strategy suggests consolidation benefits for players who own both primary packaging and dispensing technologies.
- Nordson EFD (East Providence, Rhode Island, USA): Focused on industrial fluid dispensing, Nordson competes on dispensing precision, ergonomics, and automation-friendly designs—principles that will increasingly matter for high-mix electronics and adhesives applications.
- Sulzer / medmix (Winterthur, Switzerland): Known for two-component Mixpac systems and sustainable greenLine offerings, medmix demonstrates how recycled plastics and circularity claims can be integrated without sacrificing performance—an instructive playbook for incumbents and new entrants alike.
- Fischbach GmbH, AptarGroup, Nipro Corporation, Syntegon and other specialists: These firms round out a landscape of capability—filling technologies, plungers/nozzles, dispensing components, and RTU production lines—creating an ecosystem where partnerships and co‑development accelerate route-to-market.
Dynamics shaping 2026 procurement and innovation choices
Three macro drivers will determine winners and losers next year:
- Raw material price volatility and regional differentials. Recent industry data show meaningful differences in polymer pricing across geographies and feedstocks, generating pressure on manufacturers with tightly integrated, single-source resin exposure. PW Consulting’s scenario analysis models the impact of resin price shifts on SKU profitability and recommends tactical contract structures and targeted conversion to lower-cost polymers where compatibility permits.
- Sustainability and circular-material initiatives. Product launches and pilot programs from OEMs and converters—including paper-based cartridge concepts and PCR/PIR resin platforms—are moving from proof-of-concept toward commercial trials. Manufacturers that can certify lower-carbon options while preserving functional performance will open procurement gates in regulated categories.
- Service and automation. Demand for RTU formats, validated filling, and integrated dispensing systems increases procurement preference for suppliers that minimize customer validation burden. Investments in filling automation or partnerships with RTU-specialists reduce time-to-market for pharma customers and provide defensible margins.
What PW Consulting’s full report delivers (practical, executable content)
- Top‑down and bottom‑up market sizing with sensitivity scenarios for commodity and regulatory shocks.
- Supply‑chain mapping and raw‑material exposure matrix with recommended hedging and specification pathways.
- Company profiles with strategic SWOTs, capability matrices, and potential alliance maps for the leading manufacturers and equipment suppliers.
- Go‑to‑market playbooks for incumbent manufacturers, private equity investors, and new entrants—covering product positioning, channel strategies, and pricing architecture.
- M&A screening tools and integration checklists tuned for cartridge-related assets (manufacturing, filling, and assembly operations).
- Regulatory and sustainability readiness checklist tying product choices to procurement thresholds in pharma and industrial sectors.
Recent industry signals—innovation and competitive moves
The market is already responding to sustainability and material innovation signals. Notable public moves include commercial introductions of paper-based cartridges aimed at adhesive and sealant use-cases, and trade events highlighting nitrocellulose‑free inks and printing technologies relevant to cartridge decoration and traceability. Separately, suppliers are commercializing recycled-plastic cartridge systems to lower lifecycle emissions while maintaining dispensing performance. These developments underscore two practical takeaways: (1) product innovation cycles are shortening; and (2) sustainability is shifting from “nice to have” to procurement criterion.
Recommendations for 2026 action
- Immediate (Q1–Q2 2026): Finalize sourcing contracts with polymer suppliers incorporating flexibility clauses; prioritize investments in validated RTU partnerships for regulated customers.
- Medium term (2026 planning horizon): Pilot low-carbon or recycled-content SKU lines with anchor customers to secure early revenue premiums and capture learnings ahead of tighter regulatory expectations.
- Strategic (18–36 months): Evaluate acquisitions or JVs that pair dispensing hardware with filling/sterilization capabilities to create integrated value propositions that raise switching costs for customers.
Conclusion and access to full intelligence
For executives charting 2026 priorities, the cartridge systems market presents a clear mix of steady growth and strategic inflection points. The market’s expansion trajectory is material—approaching a multi‑billion dollar opportunity over the next decade—yet the winners will be those who convert top‑line growth into defensible margin via materials strategy, service integration, and timely capability investments.
PW Consulting’s full Cartridge Systems Market report provides the granular segmentation, competitive scorecards, and financial models needed to operationalize the recommendations summarized here. To obtain the comprehensive dataset, company-by-company profiles, and the scenario toolset referenced in this preview, visit the official report page.
For detailed analysis of this topic, please visit the official page: Cartridge Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


