



PW Consulting: Client Portal Software Market Tops USD 2.19 Billion in 2025, Poised to Expand at a 14.28% CAGR Through 2032

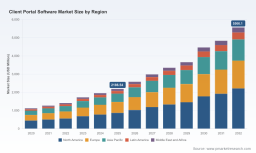
Client Portal Software Market 2026: Strategic Preview from PW Consulting
Executive summary
PW Consulting’s latest market research on Client Portal Software provides a focused, action-oriented roadmap for enterprise decision-makers preparing for 2026 procurement and transformation cycles. The market is maturing rapidly: after a period of accelerated adoption during 2020–2025, our base-year 2025 sizing indicates a market in excess of USD 2.18 billion (USD Million). Under our central forecast the sector continues to expand at a compound annual growth rate of 14.28% through 2032, approaching roughly USD 5.57 billion by the end of the forecast window.
Client Portal Software Market
This briefing highlights the strategic imperatives exposed by the study—where to invest, which vendor archetypes to prioritize, and how to structure TCO, compliance and deployment decisions for 2026—while reserving detailed subsegment metrics and vendor-level share tables for the full report available on our client portal.
Client Portal Software Market
Why this matters in 2026: the decision context
-
Strategic timing: 2026 is the year many enterprises codify post-pandemic service models. Client portals are no longer “nice-to-have” customer conveniences; they are operational backbones for secure collaboration, billing, case management and compliance. The forecast trajectory outlined above means procurement windows and capital plans made in 2026 will determine platform lock-in across the most favorable phase of market expansion.
Client Portal Software Market -
Build vs buy calculus: Rapid vendor feature innovation (AI-driven personalization, low-code page builders, integrated identity stacks) compresses differentiation among categories, changing the ROI math for in‑house builds. Our report provides a structured decision framework to test build-versus-buy hypotheses against TCO, time-to-value and compliance risk.
-
Negotiation leverage: Overall growth masks a fragmented supplier landscape. Leading vendors do not yet control an overwhelming share of the market, which preserves negotiating leverage for strategic buyers with clear procurement playbooks.
Key market dynamics and implications
-
Platform convergence and low-code acceleration: Major cloud and CRM providers are embedding portal capabilities into broader experience suites and low-code page builders. Expect purchasing decisions to be increasingly influenced by existing CRM or ERP footprints and by the vendor’s AI & automation roadmap.
-
Cost composition is shifting: Hosting discounts at scale (e.g., recent reductions in sustained-use instance pricing) and rising API/SSO licensing costs are creating divergent cost curves between platform-led and integration-led implementations. Our TCO models show that hosting savings alone do not offset API and identity licensing unless integration volumes are optimized.
-
Compliance as a primary driver: Privacy and audit requirements—GDPR pseudonymization expectations and SOC 2 Type II for financial data—are material design constraints. Compliance readiness influences vendor shortlists and time-to-production, especially for customer segments handling regulated data.
-
Talent & customization costs: High developer salary baselines and demand for specialist skills (security, API orchestration, identity management) increase the effective cost of bespoke portals. Buyers should quantify the premium for customization vs. adopting configurable vendor platforms.
Competitive landscape: what the major players are doing
The vendor universe ranges from CRM incumbents to vertical specialists and open‑source platforms. The market’s fragmentation persists: the combined share of the leading three suppliers is modest and the top five together capture well under one-third of total market revenue—conditions that favor a differentiated sourcing strategy rather than a single-vendor bet.
-
Salesforce — Experience and ecosystem strength: Salesforce’s Experience Cloud continues to evolve toward AI-driven personalization and deep CRM integration. Its recent enhancements position it as a default choice for enterprises prioritizing extensibility, single-vendor experience stacks, and ecosystem-driven accelerators.
-
Microsoft — Low-code and AI in the stack: Microsoft’s integration of Copilot into Power Pages and Dynamics portals lowers the bar for intelligent search and automation inside client portals, making it attractive to organizations with large Microsoft estates seeking rapid deployment and unified identity.
-
HubSpot, Zendesk, Freshworks — Mid-market and service specialization: These vendors compete on simplicity, integrated ticketing, and packaged workflows. Recent partnerships and product updates emphasize ease of use and ecosystem connectivity, appealing to mid-market service organizations.
-
Zoho & Odoo — Cost-effective integrated suites: Product updates that expand mobile support and e-signature, combined with an integrated ERP/CRM posture, make these suites compelling for organizations seeking predictable pricing and broad functional coverage with less heavy customization.
-
Vertical specialists (Clio, AppFolio, Practice Ignition) — Domain depth: Vendors focused on legal, property management, and accounting deliver deep, out-of-the-box workflows and compliance mapping, reducing integration effort for regulated use-cases.
-
Niche and open-source alternatives (Bitrix24, SugarCRM, Citrix ShareFile) — Flexibility and control: These providers are often chosen where data sovereignty, white-labeling, or bespoke automation is central; they require more integration effort but offer pricing and architectural flexibility.
Recent product moves that change vendor evaluation
-
Salesforce (Sept 2024): AI-driven personalization features expand the value of experience layers, shifting buyer focus to AI governance and data strategy.
-
Microsoft (June 2024): Copilot integration into Power Pages makes intelligent search and automation a checkbox in low-code scenarios.
-
HubSpot (Apr 2024): Workspace partnerships reduce friction for file sync; useful for document-heavy workflows.
-
Zoho (Mar 2024) and ServiceNow (Feb 2024): Mobile-first portal updates and enhanced analytics respectively lower go-live risk for client engagement and measurement.
What PW Consulting’s full report delivers (selected practical tools)
-
Decision frameworks to evaluate build vs buy, including sensitivity analysis on developer wages, identity licensing, and hosting costs.
-
Vendor archetype matrix and procurement playbooks tailored to enterprise, mid-market and regulated verticals (with anonymized scorecards and customization risk flags).
-
Implementation blueprints: phased migration roadmaps, RFP templates, acceptance test suites, and a vendor negotiation checklist that quantifies migration levers.
-
Compliance mapping: practical controls map for GDPR pseudonymization, SOC 2 alignment, and cross-border data flows—aligned to technical design patterns.
-
TCO and ROI models (interactive): hosting scenarios, API call cost sensitivity (including identity/SAML/SSO pricing assumptions), licensing comparators and break-even timelines for customization vs configuration.
-
Benchmarks and KPIs: standardized portal engagement metrics, SLA templates, and vendor performance baselines for security, uptime, and feature velocity.
Strategic recommendations for enterprise leaders in 2026
-
Start with compliance-first architecture. Map data flows and apply pseudonymization and encryption controls at design time—do not defer privacy controls to later sprints. For regulated lines of business, insist on audited SOC 2 Type II evidence before pilot sign-off.
-
Quantify identity costs early. SSO/API licensing can materially shift TCO; model Okta‑style per-user costs and realistic authentication volumes in procurement scenarios.
-
Use a vendor archetype approach to shortlisting. Separate vendors that win on ecosystem integration, low-code velocity, vertical depth, and cost flexibility, then match archetypes to your operational priorities.
-
Favor modular pilots with measurable KPIs. Validate automation, document workflows and AI search in a single line-of-business before full rollout to reduce rework and customization expense.
-
Lock in migration and exit terms. Given the market’s fast pace of feature change, contractually codify data exports, APIs, and portability clauses to protect against vendor lock-in.
-
Revisit resourcing assumptions. If customization is required, budget for specialist engineers and security resources; the current labor market materially increases the cost of bespoke builds.
How to use this preview
This release is intended as a strategic preview: it highlights the market trajectory, competitive behaviors and the practical levers procurement and product leaders should prioritize in 2026. The full PW Consulting Client Portal Software Market Report contains the granular subsegment breakdowns, regional and vertical splits, vendor scorecards, and the interactive TCO models and RFP templates referenced above. Those datasets are intentionally reserved for the full report and the client portal to preserve the actionable advantage for subscribers.
Next steps
If you are preparing a 2026 roadmap—whether deciding between upgrading an incumbent portal, adopting a packaged vendor solution, or building in-house—PW Consulting can provide a tailored briefing that applies our models to your estate and use-cases. Our diagnostics will map vendor fit, compliance gaps, and a 12–24 month implementation plan that aligns with your capital cycles and operational targets.
PW Consulting’s projections and playbooks aim to convert market-scale opportunity into executable decisions. The client portal market’s high growth and fragmented vendor base create windows for strategic buyers to secure favorable commercial terms, accelerate digital services, and reduce long-term TCO—if they act with a compliance-aware, identity-centered, and vendor-archetype driven strategy. For the full dataset, model access, and vendor scorecards, please consult the complete report on the PW Consulting client portal.
For detailed analysis of this topic, please visit the official page: Client Portal Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


