



PW Consulting: Coated Carbon Foil Market to Grow from USD 1,489.37 Million in 2025 to USD 3,925.73 Million by 2032 at a 14.85% CAGR

Coated Carbon Foil Market Outlook 2026: Strategic Imperatives from PW Consulting’s New Market Study
PW Consulting’s latest Coated Carbon Foil Market report (base year 2025; historical scope 2020–2025; forecast 2026–2032) delivers a concise, actionable intelligence package that senior executives and strategy teams must read before setting 2026 investment, sourcing, and capacity plans. The market has evolved from niche technical enhancement to a structural enabler of modern power and stationary storage architectures. Our analysis captures the trajectory of the overall market, the competitive shifts reshaping supply chains, and the practical playbook required to convert technological advantages into commercial resilience.
Coated Carbon Foil Market
Why this report matters for 2026 decision cycles
-
Accelerating adoption: The coated carbon foil market is in a multi-year expansion phase. PW Consulting’s topline model shows the industry expanding at a robust compound annual growth rate (CAGR) of 14.85% through our 2026–2032 forecast horizon. That growth is not linear; it is driven by technology adoption curves in power batteries, cell format transitions, and the roll‑out of next-generation energy storage systems.
Coated Carbon Foil Market -
Timing-sensitive moves: For executives planning CAPEX, M&A, or strategic partnerships in 2026, the difference between a proactive and reactive approach will determine who captures premium margins as demand scales. This report isolates the inflection points and lead indicators that precede capacity tightness and price normalization.
Coated Carbon Foil Market -
De-risking the supply chain: Carbon-coated foils have moved from “value-add” to a production prerequisite for many high-energy cell formats. Our work identifies where supply chain opacity persists and where vertically integrated players are most likely to pull ahead.
Market snapshot: scale and trajectory (what we reveal, and what we intentionally reserve)
PW Consulting’s top-down market model places the global coated carbon foil industry squarely within a steep growth corridor. After consistent expansion through 2020–2025, overall industry receipts reach a material scale in the report’s base year, then continue to rise across the 2026–2032 forecast. The long-term CAGR we model for the forecast window is 14.85% (expressed in million USD), reflecting both rising unit demand for advanced current collectors and incremental value captured via higher‑performance coatings and integrated services.
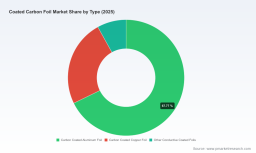
We present a clear, audited view of historical market expansion and the forward curve for total market size. To preserve the strategic value of the proprietary segmentation work—where the highest commercial leverage exists—we intentionally reserve detailed region‑by‑region, type‑by‑type, and application‑level numerical breakdowns for report licensees. The public preview herein is designed to show directional confidence and modeling rigor while encouraging buyer engagement for the full dataset and downloadable models.
Key demand drivers and market dynamics
-
Cell chemistry and format evolution: The pivot to higher-nickel cathodes and silicon‑rich anodes increases the demand for coatings that improve adhesion and enable stable cycle life. In our analysis, coated carbon foils contribute meaningfully to cycle-life gains and manufacturability for advanced cells—converting material innovation into system-level value.
-
Gigafactory proliferation and localization: New cell capacity investments and regional policy incentives are reshaping where and how coated foil capacity is deployed. The report maps strategic corridors where supplier investments are most likely to accelerate, and where counterparty concentration will require long-term sourcing agreements.
-
Upstream raw material dynamics: Conductive carbon slurries—traditionally supplied by specialty chemistries players—represent a margin and supply risk. Our interviews and techno-economic models show a growing tendency among foil producers to internalize slurry production to improve margins and reduce supply volatility.
-
Standardization and mass production: What was once optional for performance cells has become widely adopted for certain power battery formats; this normalization changes procurement levers, lot‑size economics, and qualification cycles for OEMs and cathode makers.
Competitive landscape—who matters and why
The competitive map for coated carbon foil combines legacy foil producers, specialized coating houses, and emerging integrated suppliers. Market concentration is moderate: the top three players account for a meaningful share of industry receipts, while the top five collectively represent an even larger portion—indicating a market that rewards scale but still offers niches for specialized suppliers. PW Consulting’s CR3 and CR5 benchmarks illuminate the balance between consolidation and competitive entry without disclosing proprietary share allocations reserved for report subscribers.
-
Established global players: Companies with long-standing foil and film expertise have adapted by adding conductive primer technologies and lane/dual‑side coating capabilities to serve battery manufacturers. Their competitive advantage is built on metallurgical expertise, established quality systems, and global customer relationships.
-
Specialist coating houses: A subset of firms focuses on ultra-thin conductive primers, protective interlayers, and surface chemistry that improve electrode interfaces. These players are high-value partners for cell designers seeking specific performance outcomes.
-
Regional challengers: Several Asia-based manufacturers are rapidly expanding capacity and closing technology gaps through in‑house slurry development and targeted investments. Their strategies are centered on speed-to-market, cost parity, and localized supply to regional gigafactories.
Representative companies discussed in our competitive review include multi-decade coated films specialists, legacy aluminum foil makers that have expanded into battery priming, and innovators in nano-coating materials. For each player, the report provides an execution profile covering technologies, plant footprints, vertical integration moves, and partnership pipelines—enough to inform supplier selection and M&A scouting without revealing the underlying proprietary market shares included in the full dataset.
Recent industry developments (selected, strategic reads)
-
Cross-border consolidation and international expansion are accelerating as regional suppliers seek access to adjacent markets and customer bases.
-
Capacity expansions and new lines targeting carbon-coated variants are shifting the supply mix from standard foil to value‑added coated solutions; these moves are strategic responses to regional EV demand and stationary storage projects.
-
Suppliers that vertically integrate slurry and coating processes gain asymmetric control over cost and quality—an emerging advantage as buyers shorten supplier lists and accelerate qualification windows.
What the report delivers: practical, transaction-ready content
-
Actionable market model: a validated topline model spanning 2020–2032 with base-year audit and scenario stress-tests designed for CFO and strategy use.
-
Buyer/supplier playbook: supplier scorecards, qualification timelines, and negotiation playbooks tailored to procurement teams seeking to secure capacity and improve cost curves.
-
Investment decision framework: CAPEX prioritization matrices and ROI cases that translate coating technology parameters into factory-level economics.
-
M&A and partnership screening: target prioritization criteria, integration risk checklists, and post-deal value capture mechanisms.
-
Technology deep-dive appendix: a concise primer on coating chemistries, slurry supply dynamics, and manufacturing constraints that influence scale-up timelines.
Executive recommendations for 2026
-
Prioritize dual-track sourcing: secure strategic long‑lead agreements with at least two qualified coated‑foil suppliers—one global player and one regional capacity provider—to mitigate qualification delays and geopolitical supply risks.
-
Assess vertical integration selectively: for OEMs and large cathode makers, evaluate the economics of on-shore slurry or primer partnerships to capture margin and insulate production from specialty chemical shortages.
-
Make capacity optionality investments: design factory expansions or off-take agreements with contractual flexibility (phased ramps, embedded escape clauses) to balance exposure to demand volatility.
-
Embed materials KPIs into cell design cycles: require coated-foil performance metrics as part of early-stage design validation to reduce downstream rework and accelerate time-to-volume.
-
Monitor supplier M&A closely: consolidation among coating specialists or foil producers will alter qualification paths and may create short-term sourcing disruptions when firms prioritize internal customers.
Next steps: how to use this preview
This release is a strategic trailer: it supplies the insights you need to flag immediate priorities for 2026, while reserving the detailed segmentation, supplier share tables, and downloadable financial models for report license holders. PW Consulting clients and qualified purchasers can access full datasets, supplier scorecards, and custom scenario runs that translate the report’s forecast into bespoke decision support.
To obtain the complete Coated Carbon Foil Market report and our proprietary models, or to commission a tailored deep-dive for your procurement, product, or M&A teams, please contact PW Consulting’s industrial materials practice or visit our report page for licensing options and advisory engagements.
PW Consulting remains committed to translating complex materials science and supply-chain shifts into clear, transaction-ready guidance. As coated carbon foils transition from a differentiation lever to a production standard across advanced cell formats, the choices made in 2026 will determine competitive positioning for the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Coated Carbon Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


