



PW Consulting Predicts 5.18% CAGR for Global Rugby Equipment Market, Signaling Strong Growth AheadPW Consulting: Magnesium & Magnesium Alloy Market to Expand at 6.25% CAGR (2026–2032), Growing from USD 5,250 Million in 2025 to USD 8,025.31 Million by 2032

Rugby Equipment Market 2026: Strategic Briefing — Why the Next 12 Months Will Define Winners and Losers
PW Consulting is pleased to release an executive briefing drawn from our full Rugby Equipment Market report (base year 2025). As organizations prepare budgets, product roadmaps, and M&A pipelines for 2026, this analysis identifies the structural drivers, competitor moves, and operational levers that will determine market leadership. The market reached USD 1,142.5 Million in 2025 and is forecast to expand to roughly USD 1,203.6 Million in 2026, continuing to grow at a compound annual growth rate of 5.18% through 2032 to reach approximately USD 1,627.0 Million. This trajectory—moderate, structural, and uneven across channels and product types—creates both predictable challenges and time-sensitive opportunities for equipment manufacturers, retailers, and rights holders.
Rugby Equipment Market
Why this report matters for 2026 decision-makers
- Actionable market sizing and trend signals to calibrate 2026 investment and inventory plans based on a verified market baseline and forward scenarios.
- Regulatory and input-cost risk matrices that translate compliance and raw-material volatility into concrete margin and sourcing implications.
- Competitive positioning playbooks that link product innovation, channel strategy, and licensing to measurable outcomes in share and profitability.
- Rapid-response operational templates (pricing, recall readiness, and certification timelines) designed for a sport where safety standards and supply-chain shocks directly affect commercial continuity.
- A scenario-based view that lets executives stress-test strategies against demand shocks (youth participation swings), material price shocks, and regulatory shifts.
Core market dynamics shaping 2026 strategy
- Participation-led demand: Global registered participation rose to 9.6 million players in 2024, with youth programs driving meaningful uplifts in equipment replacement cycles. Companies that target junior markets with tailored product lifecycles and appropriate price points will capture outsized growth.
- Regulatory tightening and safety as a commercial axis: World Rugby Law 4 (impact-testing requirements introduced/updated since 2023) has elevated certification timelines and product development costs. Organizations that embed compliance into early-stage design shorten time-to-shelf and reduce recall risk.
- Raw-material volatility: Synthetic leather inputs (PVC/PU) experienced notable price pressure in 2024—our supply model flagged an approximate 8% input-price movement that materially altered margin profiles for ball and footwear producers. Hedging and alternative-material strategies are now central procurement priorities.
- Product safety and reputational risk: High-profile quality events (for example, a delamination recall in 2024) underscore the reputational and financial downside of QA lapses. Recall playbooks and third-party certification are non-negotiable in 2026 planning.
- Regulatory complexity in trade/chemicals: Regional restrictions—such as limits on certain phthalates—create compliance differentials between manufacturing bases and selling markets. Traceability and compliance-by-design approaches unlock market access and reduce rework.
- Market structure: Concentration metrics indicate that the top three and five players control a meaningful portion of the market (CR3 ≈ 38.5%, CR5 ≈ 52.4%). This structure favors scaled brands in premium and licensed channels while leaving adjacent spaces available for focused challengers and private-label strategies.
Competitive landscape — what incumbents and challengers are doing
The supply base ranges from global sports giants to specialized niche manufacturers and distributors. Several strategic patterns merit attention:
Rugby Equipment Market
- Global brand leverage: Adidas, with World Rugby partnership activities (including the 2023 match-ball and team kit launches), continues to monetize tournament cycles and brand sponsorships. For 2026, look for an intensified premiumization play tied to global events and training-technology integration.
- Heritage and product leadership: Long-established ball makers (Gilbert, Mitre) are competing on material and manufacturing innovation—recent IRB-certified grip improvements and stricter QA protocols are examples of product differentiation that map to on-field performance and procurement preferences.
- Safety and certification specialists: Companies such as Maddox have moved to broaden their certified headguard portfolios, reflecting the commercialization of safety as a purchase driver. These vendors are incumbents in performance-oriented and elite channels where compliance is a purchasing constraint.
- Training and club equipment specialists: Manufacturers focused on durable training assets (e.g., tackle bags, scrum machines) are expanding into bundle solutions for clubs and academies, creating recurring revenue opportunities via services and after-sales maintenance.
- Mass market footprint and price competition: Retailers and large-format brands (e.g., Decathlon) continue to pressure price-sensitive segments with private-label offerings and broad distribution. Their scale in procurement and distribution constrains margin expansion for smaller brands without clear differentiation.
- Cross-cutting role of World Rugby: As a standards and licensing authority, World Rugby’s specifications and tournament calendars materially affect product cycles and sales windows. Aligning product development with governing-body timelines is a predictable commercial lever.
What the full PW Consulting report delivers (practical, implementation-ready)
- Executive dashboard with verified market sizing and growth scenarios (2020–2032 baseline and 2026-focused scenarios).
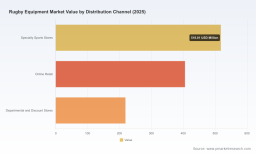
- Demand model by channel and product archetype with sensitivity analysis for participation, pricing, and input-cost shocks.
- Go-to-market playbooks for OEMs, retailers, and rights holders—covering DTC acceleration, wholesale replenishment cadence, licensing monetization, and event-driven inventory strategies.
- Pricing & margin toolkit that converts raw-material indices, certification costs, and channel fees into SKU-level margin targets.
- Supply-chain risk map with mitigation options: dual-sourcing templates, lead-time buffers, and inventory segmentation logic for high-risk SKUs.
- Regulatory compliance blueprint and factory-audit checklist to streamline certifications (Law 4, regional chemical restrictions) and reduce time-to-market.
- M&A and partnership screening framework identifying high-value targets by capability (certification, channel access, manufacturing footprint) and integration playbooks.
- Case studies and competitive benchmarking based on primary interviews with brand leaders, distributors, and federation officials.
Strategic recommendations for players planning 2026 execution
- Prioritize safety-certified, youth-targeted SKUs as a near-term revenue and share-growth lever. Youth programs are the most responsive segment to targeted product launches and community engagement.
- Hedge procurement exposure to PVC/PU price cycles and evaluate validated alternative substrates to protect margin. Short-term hedges combined with mid-term material innovation reduce downside risk.
- Design for compliance: integrate testing and certification costs into early-stage NPD budgets to avoid launch delays and costly redesigns.
- Invest in digital-first DTC capabilities to capture margin and first-party consumer data—use loyalty and localized product assortments to counter mass-market price pressure.
- Pursue selective licensing and tournament-aligned product windows. Tournament cycles remain high-impact commercial levers for brand awareness and premium pricing.
- Adopt a portfolio approach to channels: scale where brand and margin permit; use targeted private-label and mass-market partnerships for coverage and volume.
- Prepare recall and QA rapid-response capabilities. Robust traceability is both a compliance and a brand-protection asset.
- For strategics and PE: target tuck-ins that add certification capability, regional manufacturing presence, or distribution access to accelerate share capture in specific channels.
How PW Consulting supports implementation
Clients can engage PW Consulting for bespoke workstreams ranging from a 6–8 week commercial due diligence to a 100-day go-to-market sprint, or longer-term transformation programs focused on supply-chain resilience and digital channel expansion. Our deliverables include executable roadmaps, KPI-led implementation plans, negotiated supplier term templates, and rapid prototyping support for certified product lines.
Rugby Equipment Market
Trailer: what’s reserved for the full report
This briefing highlights structural drivers, competitor positioning, and practical frameworks for 2026 planning. The full report contains the proprietary dataset, region- and product-level demand models, granular channel economics, and ranked company scorecards used to derive the recommendations above. Those detailed breakdowns—including SKU-level margin projections, regional assortment matrices, and the full list of screened M&A targets—are available exclusively in the paid report and accompanying databases.
For executives preparing 2026 budgets and strategy decks, the coming 12 months will separate operators who reactively manage volatility from those who convert it into sustained advantage. PW Consulting’s Rugby Equipment Market report equips leaders with the market intelligence, risk mitigants, and tactical playbooks needed to win in that environment. To access the full report, proprietary datasets, and to schedule a briefing with our industry leads, please visit the PW Consulting report page or contact our strategy team directly.
For detailed analysis of this topic, please visit the official page: Rugby Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


