



PW Consulting: RF EAS Label Market to Rise from USD 644.11M in 2025 to USD 847.02M by 2032 at a 3.99% CAGR — Europe (USD 213.33M), Deactivatable Labels (USD 448.99M) and Apparel Drive Growth

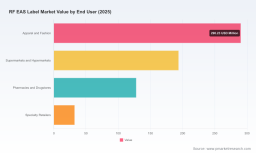
RF EAS Label Market: Strategic Imperatives for 2026 — Executive Brief from PW Consulting
Executive summary
As retailers and brands confront accelerated theft, tighter sustainability mandates and the next wave of checkout automation, RF electronic article surveillance (EAS) labels are shifting from commodity security items to strategic enablers across loss prevention, packaging compliance and omnichannel operations. Our new Rf Eas Label Market report — grounded on a 2020–2025 historical base and forward-looking through 2026–2032 — quantifies this transition and translates it into decision-grade guidance for 2026 investments.
Rf Eas Label Market
Key macro takeaways: the global RF EAS label market reached an estimated USD 644.11 Million in the base year (2025) and is forecast to expand to roughly USD 847.02 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 3.99% over the projection window. Market concentration is material enough to make vendor selection consequential: the top three suppliers account for roughly 41.5% of market revenue and the top five approach 57%, indicating a landscape where a limited set of established providers retain scale advantages while a broad field of regional and specialist players continues to innovate.
Rf Eas Label Market
Why this matters for 2026 decision-makers
- Procurement and vendor strategy: With structural growth but mid-level concentration, procurement teams must balance scale (price, global service) against specialized capabilities (metal-tolerant labels, micro labels, sourcing flexibility). Our report explains how to construct multi-vendor sourcing frameworks that reduce single‑supplier risk while capturing unit-cost benefits.
- Loss prevention & store operations: Recent product premieres integrating RF EAS with checkout and cloud platforms point to a near-term shift: EAS is becoming part of store IT architecture, not merely a peripheral security device. This changes CAPEX/OPEX dynamics and the skills required to manage these systems.
- Sustainability and compliance: Extended Producer Responsibility (EPR) schemes and emerging EU packaging rules are raising the operational cost of packaging components. Labels — their substrates and embedded circuits — are now implicated in compliance and end-of-life reporting. Companies need to align label design and supplier contracts with sustainability KPIs to avoid fee escalations and reporting burdens.
Market trajectory and what the numbers conceal (and reveal)
The market’s steady CAGR of approximately 3.99% signals mature, demand-driven expansion rather than speculative spurts. Growth is being fueled by three intertwined vectors: retailers’ ongoing investments in shrink prevention, the migration of tagging to the point of manufacture (source tagging), and the operationalization of RF technologies into omnichannel flows (from inventory reconciliation to automated checkout). Yet growth is uneven: pockets of accelerated demand emerge in geographies and product categories that prioritize visible tagging, metal-tolerant solutions, or deep RFID integration.
Rf Eas Label Market
Importantly, headline totals do not tell the whole story. Unit economics differ widely by label type, manufacturing technique and value chain placement (in-line factory application versus in-store application). That variance is the strategic lever for both suppliers and buyers: small design or process changes can shift margin and compliance outcomes materially. Our report models these dynamics and provides scenario outputs to stress-test budget plans under alternative price, raw-material and recycling-fee trajectories.
Drivers, constraints and regulatory dynamics
- Organized retail crime (ORC) and shrink: Intensifying theft patterns are prompting retailers to invest in higher-detection and specialized labels (e.g., metal-capable forms, anti-human shielding variants). Suppliers are responding with product-level innovation aimed at detection performance without increasing label profile or cost unduly.
- Checkout and systems integration: The trend toward integrating EAS with RFID and POS — exemplified by recent point-of-sale antenna premieres and cloud management platforms — is changing product specifications, installation practices and service models.
- Materials and supply chain pressure: Typical RF soft labels rely on paper substrates with aluminum or copper conductors. Volatility in these commodity inputs, combined with sustainability requirements, means buyers must now manage upstream risk and recyclability trade-offs as part of label procurement.
- Regulation and EPR: Extended Producer Responsibility frameworks — already present in multiple US states and evolving across the EU — impose new obligations and potential fees tied to packaging components, including labels. The EU’s Packaging and Packaging Waste Regulation and state-level schemes (e.g., recent US state adoptions) are elevating the cost of non-recyclable or mixed-material label constructions.
Competitive landscape — leading players and strategic archetypes
The market is a mix of global incumbents with broad portfolios and regional innovators focused on specialized use cases. Several archetypes stand out:
- Portfolio incumbents with scale and R&D depth: Firms offering broad RF EAS portfolios — spanning grocery, apparel, cosmetics and auto‑apply at source — are positioned to serve global retailers seeking standardized deployments and integrated services. Their advantages include in-house manufacturing, multi-tech product stacks and established service networks.
- Specialist source-tagging and custom providers: Some US and China-based players focus on source tagging for apparel and hard goods, customizable SuperLabels and micro labels for high-shrink items. They compete on customization, time-to-market and tight integrations with garment and packaging processes.
- Technology-driven challengers: Companies introducing metal-detection hybrids, RF + metal systems, and POS-integrated antennae are redefining performance expectations. Recent product launches and trade-show demonstrations show a competitive pivot toward solutions that close the gap between loss prevention and checkout efficiency.
Recent company moves provide a window into tactical priorities. One established global supplier premiered an RFID-capable checkout antenna and, in the prior year, launched a cloud-centered store operations platform — moves that underscore strategy to own both hardware and the software layer that organizes in-store RF devices. A manufacturer from Hangzhou introduced a combined RF + metal detection system and used a major retail technology trade show to highlight product maturity after multi-year development. These events are not isolated: they signal supplier efforts to convert technical differentiation into commercial deployment at scale.
What the PW Consulting report delivers (practical components)
This study is designed as an operational playbook for 2026 decision-making, not merely an academic forecast. Deliverables include:
- Volume and revenue outlooks across 2026–2032 with scenario-based sensitivities that factor raw-material pricing, EPR fee escalations and adoption rates of source tagging and POS-integrated systems.
- Supplier benchmarking and capability heatmaps that evaluate R&D, manufacturing footprint, product breadth (metal-tolerant labels, micro forms, etching craft), systems integration and service models.
- Procurement frameworks and multi-supplier contracting templates that balance total-cost-of-ownership, compliance obligations and supplier innovation roadmaps.
- Technology decision matrices to guide trade-offs between RF, RFID convergence, and hybrid metal-detect solutions, including ROI case models tailored to apparel retailers, grocery chains and pharmacy formats.
- Implementation playbooks and sample RFP language for source‑tagging programs, labeling automation at packhouses and rollout of POS-integrated antannae.
- Regulatory impact analysis mapping EPR/PPWR exposure, likely fee trajectories and label design levers to mitigate costs while improving recyclability.
Strategic recommendations for 2026
- Adopt a layered vendor strategy: Lock core volumes with proven global suppliers for unit cost and supply continuity, while retaining niche vendors for metal-tolerant or micro-label needs. Insist on transparency for raw-material sourcing and recyclability metrics.
- Prioritize integration pilots: Run controlled pilots that combine EAS antennas with RFID checkpoints and cloud device management in a subset of high-shrink stores. Use these pilots to validate operational savings and refine labor flows.
- Embed compliance in specifications: Update technical specs to mandate recycled-content reporting and end-of-life handling terms. Tie a portion of supplier compensation to improved recyclability or EPR fee avoidance metrics.
- Reassess TCO with new product classes: Include software subscription, cloud management and POS integration costs in TCO models — not just label unit price. Recent product launches signal that vendors will increasingly monetize software and service layers.
- Use the report’s scenario outputs for budgeting: Stress-test loss-prevention and packaging budgets against alternative EPR fee scenarios and raw-material shocks; build contingencies into 2026 procurement cycles.
How to use this research — next steps
For strategy teams, loss-prevention leaders and procurement heads planning 2026 budgets, this report functions as both a market map and an operational toolkit. It provides the evidence base for vendor shortlisting, the templates for RFP execution, and the scenario modeling to align capital plans with regulatory and retail reality.
PW Consulting’s Rf Eas Label Market report intentionally presents deep methodological transparency and actionable guidance while reserving granular segment-level revenue and regional splits for the full study. That granular intelligence — including supplier scorecards, price curves and downloadable contracting templates — is available through our research portal for clients and subscribers.
Concluding note
RF EAS labels are no longer only about preventing shoplifting. They sit at the intersection of store operations, packaging sustainability and retail systems integration. For 2026, the companies that win will be those that treat label strategy as a cross-functional investment: aligning procurement, packaging, IT and loss prevention around a unified roadmap that anticipates regulation, leverages supplier innovation and captures the operational upside of integrated RF ecosystems.
For detailed analysis of this topic, please visit the official page: Rf Eas Label Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


