



PW Consulting Forecasts Liquid Hazardous Waste Management Market to Expand at 6.08% CAGR Through 2032

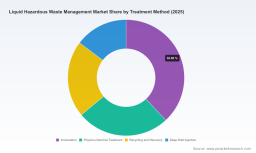
Liquid Hazardous Waste Management Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As corporate boards and public-sector planners finalize budgets and capital allocation for 2026, the liquid hazardous waste management market is emerging as a clear, measurable growth corridor. PW Consulting’s latest market study — built on a five-year historical base (2020–2025) and a forward-looking forecast (2026–2032) — projects sustained expansion at a mid-single-digit compound annual growth rate (6.08% CAGR). The global market, which was assessed at approximately USD 48.5 billion in our 2025 base year, is expected to exceed USD 73 billion by the close of the 2032 forecast window. These headline metrics frame an investment environment where scale, regulatory agility, and technology differentiation will determine winners.
Liquid Hazardous Waste Management Market
Why this report matters to 2026 decision-makers
-
Timing matters: 2026 is the inflection point for several converging dynamics — accelerating regulatory change, capital reallocation toward resilience, and a concentrated wave of capacity investments and acquisitions. Companies that read these signals and align near-term investments will unlock disproportionate optionality through the decade.
Liquid Hazardous Waste Management Market -
Risk management meets growth opportunity: With predictable market growth and an uneven competitive landscape, firms can simultaneously reduce compliance and reputational risk while pursuing accretive revenue streams from liquid hazardous waste handling, treatment, and recovery.
Liquid Hazardous Waste Management Market -
Operational levers are actionable: The economics of liquid waste management are driven by plant throughput, treatment mix, transport logistics, and disposal cost variability. Our report translates macro growth into the practical performance metrics that CFOs and COOs can act on within 12–24 months.
Key market dynamics shaping 2026 strategy
-
Regulatory acceleration. Recent rulemaking efforts and international treaty amendments are raising compliance thresholds and changing cross-border flows of hazardous streams. Notably, federal-level moves toward electronic-only manifest systems and expanded waste category treatment obligations are moving compliance timelines forward — creating both compliance risk for unprepared generators and commercial opportunities for service providers with digital and logistics capabilities.
-
Consolidation and capacity build-out. Strategic M&A and greenfield capacity investments over the last 18 months have reshaped regional footprints. Select vertically integrated players are expanding high-temperature treatment capacity and securing feedstock access through acquisitions and offtake agreements, compressing optionality for smaller regional operators.
-
Technology and circularity. Incineration, physico-chemical processing, solvent recovery, and recycling/recovery methods remain core tools, but the fastest value capture will accrue to operators that combine energy recovery, solvent reclamation, and validated circular pathways with rigorous environmental controls.
-
Fragmented competitive structure. The market retains significant fragmentation: national champions coexist with specialized niche providers (medical, radioactive, industrial solvents), creating pockets of high-margin specialization alongside a low overall concentration across the sector. This fragmentation creates acquisition arbitrage and roll-up potential for scale-minded strategists.
What PW Consulting’s report delivers — practical, executable intelligence
-
Market sizing and forward scenarios. A robust base-case projection anchored in macroeconomic drivers and granular industry indicators, complemented by downside and upside scenarios to stress-test capex and M&A plans.
-
Treatment economics playbook. Comparative cost and throughput models for prevailing treatment methods, including sensitivity analyses for feedstock composition, transport distance, and thermal versus non-thermal treatment choices.
-
Regulatory tracker and compliance impact matrix. Timelines and impact assessments for pending and enacted rules (domestic and international), with recommended compliance levers for generators, processors, and logistics providers.
-
Competitive intelligence dossiers. Company-level profiles, capability maps, and strategic intent signals for major incumbents and fast-scaling challengers — designed to inform M&A screening, partner selection, and threat assessment.
-
Site-level feasibility templates. A step-by-step capital and operating model for new treatment assets, covering permitting risk, environmental controls, community engagement, and expected payback windows under different throughput assumptions.
-
Commercial playbooks. Go-to-market frameworks for corporates and service providers, including contracting structures (volume guarantees, take-or-pay, shared investments), pricing strategies, and digital enablement approaches (e-manifest integration, customer portals, operational telematics).
-
Investor-ready M&A readiness tools. Due-diligence checklists, valuation comparators, and integration risk frameworks tailored to hazardous liquid assets.
Competitive landscape: who to watch and what they signal
-
Global integrated operators. Multinational environmental services leaders are accelerating US and international footprint expansion through strategic acquisitions and large-scale thermal treatment investments. Recent transactions and capacity projects underscore a bet on higher-throughput, high-temperature treatment capacity as a strategic moat for complex liquid streams.
-
North American platform players. Regional champions focused on hazardous liquid streams are reinforcing collection networks and emergency response capabilities, embedding full-service offerings that increase customer switching costs and create bundled revenue opportunities.
-
Specialists and niche players. Firms concentrating on regulated medical, radioactive, or industrial solvent streams are capitalizing on regulatory complexity and high-barrier treatment requirements. Their technical expertise and permit portfolios make them attractive targets for consolidation or long-term partnerships.
-
Energy-from-waste and resource recovery entrants. Operators that combine hazardous treatment with energy recovery or solvent reclamation are differentiating on total lifecycle economics, offering lower net disposal costs for generators and new revenue lines tied to recovered materials or energy credits.
Recent sector moves provide a clear illustration of these dynamics: leading multinationals have announced large-scale acquisitions and capacity expansions; specialty firms have secured major permit upgrades to scale mixed-waste processing; and strategic partnerships are being formed to secure guaranteed treatment capacity. These actions confirm that the market’s next phase will be defined as much by network control and treatment optionality as by traditional price competition.
Regulatory and geopolitical watchlist for 2026
-
Transition to digital manifests. Federal mandates toward electronic-only manifests will accelerate digitization across generators and transporters, changing invoicing, chain-of-custody, and data governance practices.
-
Expanding waste categories and treaty impacts. National rulemaking and international agreements are widening the scope of regulated materials, affecting cross-border logistics and the classification of mixed and electronic waste streams.
-
State-level moratoria and siting restrictions. Localized policy moves can materially delay capacity expansions and raise development costs; effective siting strategies and advanced community engagement are therefore critical for on-time project delivery.
Strategic priorities for executives in 2026
-
Mobilize a two-track M&A strategy: (1) bolt-on acquisitions that extend collection and logistics reach, and (2) selective investments in thermal and recovery capacity to control treatment bottlenecks. Use our valuation toolkit to prioritize targets by integration value and permit defensibility.
-
Fast-track digital compliance. Implement e-manifest readiness and integrate digital chain-of-custody into customer portals to reduce administrative costs and create friction for competitors.
-
Pursue differentiated service bundles. Combine emergency response, vacuum collection, reclamation, and validated destruction certificates to capture higher-margin, compliance-sensitive customers.
-
Underwrite siting risk rigorously. Incorporate state and municipal political risk overlays into CAPEX forecasts; structure development with contingent milestones and community benefit commitments.
-
Deploy scenario-based capacity planning. Align capex phasing to demand corridors revealed by our scenario models to avoid underutilized assets while securing throughput certainty through strategic partnerships.
How PW Consulting’s brief positions you for decisive action
Our report is designed as a decision-focused asset for 2026 planning cycles: not only does it quantify near-term market momentum and mid-term upside, it also equips leaders with the operational metrics, regulatory foresight, and competitive intelligence required to convert market growth into durable value. We surface where scale matters, where specialization pays, and where regulatory timing can be monetized or mitigated.
To preserve the commercial value of our segment-level analyses and proprietary models — and to ensure rigorous use of sensitive operational assumptions in client decision-making — detailed breakdowns of regional/application splits, unit price tables, and drill-down financial models are available through our gated report package and client workshops. For executive summaries, board briefings, or tailored scenario runs, PW Consulting is offering a limited set of bespoke advisory engagements to translate the market view into executable 90–180 day plans.
Contact PW Consulting to request the full Liquid Hazardous Waste Management Market report and to schedule a strategy session with our senior industry analysts. The 2026 planning window is narrow; organizations that act on the right intelligence now will capture the structural advantages that will define the market through 2032.
For detailed analysis of this topic, please visit the official page: Liquid Hazardous Waste Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


