



PW Consulting Forecast: Refractory Bricks Market to Rise from USD 21,450.5M (Base year 2025) to USD 29,426.6M by 2032 at 4.62% CAGR; Asia‑Pacific Leads with USD 10,225.3M

Refractory Bricks Market: Strategic Intelligence for 2026 Decision‑Making
Executive preview
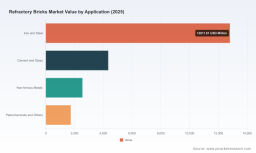
PW Consulting’s latest Refractory Bricks Market report synthesizes hard market metrics, supply‑chain stress testing, regulatory mapping, and competitive playbooks into a single operational guide for executives planning 2026 actions. The shaped‑brick market has moved from roughly USD 17.1 billion in 2020 to an estimated USD 21.45 billion in 2025 and is projected to continue expanding through the forecast horizon — reaching an estimated USD 29.4 billion by 2032. That trajectory corresponds to a 2026–2032 compound annual growth rate (CAGR) of approximately 4.62% and reflects the interplay of industrial growth, raw‑material price dynamics, and accelerating decarbonization pressures.
Refractory Bricks Market
Why this report matters for 2026 planning
-
Actionable foresight, not academic theory: The report translates market forecasts and scenario work into decision levers that procurement, operations, and corporate strategy teams can act on within the coming 12 months.
Refractory Bricks Market -
Span of influence: Coverage crosses the value chain — from raw‑material sourcing and processing economics to kiln operations, shaped brick production, and aftermarket services — enabling cross‑functional alignment on CapEx, sourcing, and service models.
Refractory Bricks Market -
Stress‑tested scenarios: We present three pragmatic scenarios (baseline, price‑shock, and decarbonization acceleration) with quantified P&L and cash‑flow sensitivities so leaders can prioritize hedges and investment phasing in 2026.
-
Competitive playbooks: The analysis identifies where scale wins, where specialization is defensible, and where regional logistics and services form sustainable moats.
Market trajectory and implications
The market’s recent expansion and the forecast path underline two simultaneous dynamics: steady demand driven by foundational industries and episodic supply‑side volatility tied to raw materials and regulation. Our base estimates show the industry recovering and growing post‑pandemic, with an anticipated step‑up in absolute market value through the late 2020s. For 2026, the key implication is simple: demand is neither collapsing nor hyper‑booming — it is growing with structural tailwinds and distinct pockets of stress that can be exploited by well‑positioned players.
For corporate planners this means prioritizing flexibility: investment decisions should favor modular capacity increases, dual‑sourcing strategies for critical feedstocks, and service offerings that capture aftermarket value (installation, predictive maintenance, and refractory recycling). Organizations that treat refractories as a dynamic cost and service channel — rather than a static line item — will preserve margin and open adjacent revenue streams.
Key drivers, risks, and regulatory context
-
Raw‑material exposure: Production economics remain heavily dependent on core inputs — alumina, magnesia, silica — which can represent the majority of production cost. Price volatility in these commodities materially affects both manufacturing margins and buyers’ LCC (lifecycle cost) calculations.
-
Regulatory pressure: Emissions and trade policy are material. Notably, European ETS provisions that treat the firing of ceramic products as a regulated activity and rising import duties in certain producing countries have already re‑shaped supplier economics and trade flows. Procurement teams must incorporate regulatory pass‑through risk into supplier evaluations.
-
End‑market linkage: Global steel production acts as a demand barometer for many refractory types. Changes in steel output, furnace technology adoption, and service life expectations feed directly into refractory demand and composition.
-
Decarbonization dynamics: There is an emerging bifurcation between vendors who invest in low‑carbon inputs/processes and those that aim for cost leadership. Awards and pilot projects in carbon‑capture‑linked refractory initiatives signal that sustainability investments are both reputational assets and potential commercial differentiators.
Competitive landscape — who matters and why
The market structure is characterized by a mix of global integrated producers and nimble regional specialists. Our competitive analysis profiles the strategic posture of major players and identifies the routes they are using to protect or expand value:
-
RHI Magnesita (Vienna): A vertically integrated leader with broad shaped‑brick capabilities and global footprint. Investment in low‑carbon projects and project award wins signal its intent to lead on sustainability as well as scale.
-
Vesuvius PLC (London): Focused on high‑performance solutions for metals and foundry customers; its strength lies in specialized products and applications engineering.
-
Shinagawa and Krosaki Harima (Japan): Technology‑driven producers with strong product breadth and export capabilities, especially in high‑performance alumina and specialty bricks.
-
Saint‑Gobain Performance Ceramics & Refractories (France): Offers advanced ceramic and fused‑cast solutions for the most demanding thermal environments, emphasizing premium product segments.
-
Regional champions (HarbisonWalker, IFGL, Resco, Puyang, Chosun, etc.): These players combine local market knowledge with custom‑shape engineering and responsive aftercare services — a competitive advantage in time‑sensitive furnace operations.
Market concentration is moderate: the top tier of firms captures a meaningful but not overwhelming share of market value, leaving room for specialists and regional consolidators to capture profitable niches. Recent M&A and capacity actions — including targeted acquisitions and brownfield expansions — underscore a market where scale, service reach, and raw‑material access are strategic differentiators.
Recent market moves and what they signal for 2026
-
Acquisitions expanding distribution and regional inventory point to a tactical race for service density in time‑sensitive territories.
-
Capacity investments at monolithic and shaped facilities reflect a dual play: some firms are betting on demand growth while others are aiming to shorten lead times and improve margin capture through vertical integration.
-
Sustainability awards and pilots indicate the early commercial value of low‑carbon refractory systems; buyers and investors will increasingly prize technologies with verifiable carbon credentials.
What the PW Consulting report contains (operationally usable)
-
Validated market model: Annual market size series, demand drivers by end‑use, and a seven‑year forecast framework, calibrated to industry KPIs and plant‑level economics.
-
Scenario playbooks: Three executable scenarios with quantified P&L impacts and recommended tactical responses for procurement, manufacturing, and commercial teams.
-
Supplier risk matrix: A short‑list of critical supplier risk exposures and actionable mitigation levers, including contract clauses, inventory strategies, and supplier development pathways.
-
CapEx and plant optimization guidance: Benchmarks for kiln utilization, refractory yield improvement initiatives, and a roadmap for modular capacity expansion with estimated payback bands.
-
Aftermarket commercialization toolkit: Pricing architecture, service bundling options, and a field‑service playbook to convert short replacement cycles into recurring revenue.
-
Regulatory and trade play sheets: Country‑level regulatory risk profiles, anticipated compliance costs, and trade‑flow sensitivities that should inform sourcing and local‑investment decisions.
Practical recommendations for 2026
-
Make raw‑material exposure a Board item: Establish quarterly stress tests that feed into working capital and pricing decisions.
-
Prioritize dual‑sourcing and strategic inventories for critical minerals in regions with trade volatility.
-
Invest in service density: Expand regional inventories and rapid‑response teams to capture aftermarket margin and shorten furnace downtime.
-
Allocate a small strategic R&D/CapEx bucket to low‑carbon refractory pilots — the technology premium is emerging and will widen with regulatory tightening.
-
Use modular capacity investments for optionality: favor brownfield add‑ons that can be scaled to demand without large initial write‑offs.
How this report functions as a decision tool
PW Consulting’s report is structured to move executives from insight to action within a six‑ to twelve‑month horizon. It translates macro forecasts into procurement actions, capital timing decisions, and commercial tactics. For CFOs and Heads of Procurement, the raw‑material scenarios and supplier risk matrices provide immediate inputs to budget and hedge discussions. For COOs and plant managers, the kiln‑level optimization guidance and aftermarket monetization playbooks are road‑tested templates that can be deployed with limited pilot CAPEX.
Closing note — the trailer principle
The material above highlights the strategic contours and operational levers in the refractory bricks market. To preserve the commercial value of granular segmentation, supplier shares, and proprietary sub‑segment forecasts, the report holds the detailed split tables, plant‑level economics, and vendor scoring matrices for the full report package. PW Consulting clients and report purchasers gain access to those detailed models, downloadable scenario files, and an executive workshop designed to convert insight into a 90‑day tactical plan.
Next steps
-
Download the full report or contact PW Consulting to schedule a bespoke executive briefing and a 90‑day implementation roadmap tailored to your operating footprint.
-
For immediate tactical use, request the supplier risk matrix and the price‑shock scenario worksheet — these are available separately and intended to be integrated into 2026 budget cycles.
For detailed analysis of this topic, please visit the official page: Refractory Bricks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


