



PW Consulting: Battery Nonwoven Diaphragm Market projected to reach USD 1.10 billion by 2032 from USD 620.0 million in 2025 at an 8.5% CAGR

Battery Nonwoven Diaphragm Market: Strategic Signals for 2026 — PW Consulting Intelligence Brief
Executive snapshot
PW Consulting’s new market study on the Battery Nonwoven Diaphragm market synthesizes five years of historical data (2020–2025) and provides a forward-looking forecast through 2032. The sector demonstrated notable growth from an estimated USD 443.0 Million in 2020 to USD 620.0 Million in 2025 (base year), and our forecast work shows acceleration into the forecast period with the market expanding at a compound annual growth rate (CAGR) of 8.5% through 2032, when our model anticipates an overall market size approaching USD 1.10 Billion. For corporate leaders making 2026 investment decisions, this study is designed as a strategic compass — mapping demand momentum, supply-side constraints, regulatory pressure points and competitive moves that will determine winners and losers over the next investment cycle.
Battery Nonwoven Diaphragm Market
Why this market matters to 2026 decision-makers
- Structural growth: The nonwoven diaphragm segment is increasingly central to lithium-based battery value chains as battery designs prioritise thermal performance, mechanical robustness and manufacturing throughput. Our modelling shows sustained expansion from mid-decade demand drivers.
- Margin and supply pressure: Rising feedstock cost volatility and evolving regulatory thresholds are compressing the margin envelope for commodity-based suppliers while creating premium opportunities for differentiated technologies.
- Strategic inflection: 2026 is a make-or-break year for firms planning capacity expansions, vertical integration, or materials substitution strategies to service electric vehicles (EVs), consumer electronics and energy storage systems.
Market trajectory and leading drivers
Our bottom-up model captures material flows, plant utilisation and techno-economic assumptions aggregated across the global footprint. After a recovery and re-rating phase in 2021–2024, the market accelerated into 2025 with structural demand from transportation electrification and grid-scale storage pilots lifting overall volumes. The CAGR of 8.5% in our forecast period reflects a blend of unit growth, higher-value material adoption, and selective premiumisation as OEMs demand separators with improved thermal stability and safety attributes.
Battery Nonwoven Diaphragm Market
Key demand vectors highlighted in the report include:
Battery Nonwoven Diaphragm Market
- EV battery programmes that are re-specifying separator performance for larger cells and higher energy density architectures, driving investment in new nonwoven material systems and processing lines.
- Consumer electronics trends that continue to prioritise thin, high-rate solutions for premium devices.
- Utility-scale and behind-the-meter energy storage systems that require cost-effective, durable separators for long cycle-life applications.
Supply-side dynamics — what keeps CFOs and supply chain chiefs awake at night
The report drills into the supply-side mechanics that will determine pricing, lead times and supplier selection across 2026 planning horizons:
- Raw material volatility: Polypropylene — a core feedstock for many nonwoven diaphragms — shows sharp market swings. In Q4 2025 polypropylene prices rose 12% year-on-year to approximately USD 1,450/ton, driven by upstream supply constraints and logistics bottlenecks. Such movements elevate the importance of multi-sourcing, hedging strategies and material efficiency programs.
- Regulatory overlay: Regulatory thresholds are tightening in major markets. Notably, EU battery regulation imposes minimum ionic conductivity requirements for automotive separators by 2027, while China’s MIIT limits fluorine content in diaphragms to under 100 ppm from January 2025. These standards force reformulation, testing investment and, in some cases, capital expenditure to requalify product lines.
- Trade and tariff considerations: Trade policy can materially reshape sourcing economics — e.g., US measures raised duties on certain Chinese battery material imports, increasing effective costs for some supply routes. Our scenario matrices model the impact of tariffs on landed costs and recommend mitigation options.
Technology evolution and product strategy
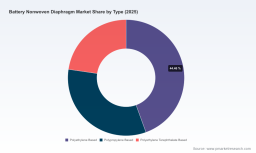
Nonwoven diaphragms are not a monolith. The market is seeing parallel technology tracks — polymer-based solutions optimised for cost and throughput, and engineered nonwovens (including cellulose and composite constructs) targeted at safety and higher-temperature applications. The report offers a technology road map covering:
- Process distinctions (wet-laid vs. dry-laid, coating and lamination options) and their yield, capex and OPEX implications.
- Performance trade-offs — e.g., thermal shrinkage, ionic conductivity, mechanical puncture resistance — and the typical design choices OEMs make by application class.
- Transition pathways from incumbent polyolefins to speciality or hybrid materials, with a focus on qualification timelines, sample-to-production cycles and cost break-even analyses.
Competitive landscape and strategic positioning
Market concentration is moderate: the top three players account for approximately 45% of market share on a capacity-weighted basis, while the top five lift concentration to around 58%. This structure creates room for scale advantages but also selective niches where technology-led or regionally localised players can compete.
Our company benchmarking examines incumbent leaders and fast-moving challengers. Among the firms we profile are long-established producers with global wet-process capabilities, specialist nonwoven innovators pursuing cellulose-based separators, and regional suppliers focused on low-cost, high-volume manufacturing. Recent strategic developments underscore the competitive intensity:
- Capacity moves: One global incumbent announced a mid-2025 capacity expansion targeted at EV demand, illustrating how established players are pre-emptively securing throughput for next-generation cell formats.
- Product innovation: Leading material science players introduced upgraded nonwoven separators in 2025 with improved thermal stability tuned for larger cylindrical cells, signalling OEM engagement on safety and form-factor optimisation.
- Certification and market entry: Specialist developers achieved key certifications in 2025 enabling entry into segments that previously favoured polyolefin solutions, highlighting the potential for disruptive material substitution.
For procurement and corporate development teams, the implication is clear: partnerships and strategic investments should be calibrated to supplier capability maps, intellectual property strength, and route-to-qualification timelines. Our report includes supplier scorecards, capability matrices and a shortlist of acquisition and JV targets consistent with near-term and medium-term strategic outcomes.
Risk scenarios and modelling — what the report gives decision-makers
Rather than single-point forecasts, PW Consulting provides scenario-driven outputs that translate uncertainty into actionable choices. The report includes:
- Three demand scenarios (base, upside and downside) with sensitivity to automotive volumes and ESS adoption rates.
- Raw material price stress-tests showing margin erosion and recommended pass-through strategies at different tariff and feedstock cost points.
- Capex and timeline templates for greenfield and brownfield expansions, including sample IRR and payback analyses under varying utilisation rates.
- Regulatory compliance pathways and cost-of-compliance estimates tied to major jurisdictional changes through 2027.
Actionable recommendations for 2026 planning
- Prioritise supplier qualification tracks for safety-critical materials now: regulatory thresholds and OEM specifications compress the time available for testing and validation. Start multi-tier qualification programs in Q1–Q2 2026 to hit production windows.
- Hedge raw material exposure and diversify feedstock: given recent polypropylene price dynamics, procurement teams should implement a blended strategy of forward contracts, alternative polymers and localized sourcing to stabilise input cost volatility.
- Revisit capex timing against utilisation sensitivity: with a moderate market concentration profile, greenfield expansions should be de-risked by offtake agreements or phased ramp plans tied to cell manufacturer commitments.
- Invest in product premiumisation where margins justify: downstream OEMs are willing to pay for demonstrable gains in thermal stability and safety; prioritise R&D into coated or composite nonwovens where price points permit.
- Monitor trade and compliance levers: tariff changes and regional standards materially alter landed cost and qualification requirements. Keep legal and regulatory teams integrated into sourcing decisions.
What the PW Consulting report contains — practical deliverables
This study blends proprietary primary intelligence with rigorous cost and demand modelling. Deliverables include:
- Full market model (historical and forecast) with configurable scenario toggles.
- Supplier benchmarking and capability heat maps.
- Go-to-market playbooks for suppliers and OEMs, covering pricing strategies, channel selection and qualification timelines.
- Capex calculators and financial templates for brownfield/greenfield decisions.
- Regulatory impact dossiers for key jurisdictions, including mitigation roadmaps.
Steering your 2026 agenda
For executives planning capital allocation, M&A, or strategic sourcing in 2026, the combination of demand growth (CAGR 8.5% through 2032), evolving regulatory constraints and feedstock volatility creates both risk and opportunity. PW Consulting’s Battery Nonwoven Diaphragm report equips leaders with the intelligence to prioritise investments, structure resilient supply chains, and engage in partnerships that secure differentiated value.
Note: This briefing highlights strategic findings and directional data to support executive decision-making. Detailed micro-segment tables, regional and application-level splits, and full supplier scorecards are intentionally not reproduced here. Access to the complete dataset, annexes and financial models is available through PW Consulting’s report portal for subscribers and authorised clients.
Next steps
- Contact your PW Consulting engagement lead to request the full model and supplier annexes for bespoke scenarios.
- Schedule a strategy workshop to align capex, sourcing and product roadmaps to the scenarios in the report.
- Engage our M&A desk for target screening and transaction support tailored to the battery nonwoven value chain.
PW Consulting — translating complex market dynamics into pragmatic strategies for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Battery Nonwoven Diaphragm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


