



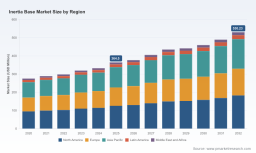
PW Consulting: Inertia Base Market Reaches USD 364.5 Million in 2025; Forecast to Top USD 530.2 Million by 2032 at 5.5% CAGR

Inertia Base Market Research — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s Inertia Base Market Research (base year 2025) synthesizes five years of historical performance (2020–2025) and delivers a seven‑year forecast (2026–2032) to inform capital, procurement and product strategy for organizations that design, specify, procure or manufacture inertia bases and related vibration‑control systems. The global market reached USD 364.5 Million in 2025 and is projected to expand at a steady 5.5% CAGR through the 2026–2032 forecast window, reflecting a combination of steady HVAC and industrial investment, rising compliance requirements, and renewed focus on lifecycle cost and reliability in mission‑critical facilities.
Inertia Base Market Research
Why this matters for 2026 strategic decisions
-
Timing and investment: With the market entering a period of steady expansion, 2026 is a pivotal year to convert strategic intent into tangible initiatives — whether that means capacity investment, channel consolidation, or product differentiation focused on high‑value applications.
Inertia Base Market Research -
Risk mitigation: Heightened seismic and vibration standards mean specification teams will need validated solutions that meet IBC/ASHRAE requirements while minimizing lifecycle disruption and warranty exposure for equipment OEMs and end users.
Inertia Base Market Research -
Cost and labor pressures: Pre‑fabricated, labor‑saving designs and integrated isolator interfaces are increasingly important as on‑site labor cost and schedule risk rise, particularly in retrofit and urban construction projects.
Market trajectory — the big picture
The inertia base market is maturing. After steady growth through 2020–2025, the sector is forecast to grow at roughly a mid‑single digit CAGR (5.5%) to 2032. This trajectory reflects continued demand from HVAC, industrial pumping and mission‑critical infrastructure, tempered by substitution pressures from alternative isolation strategies and localized supply dynamics. The market’s concentration metrics (CR3 ~32.5%, CR5 ~48.2%) indicate a landscape where a handful of established players capture meaningful share, but there remains sufficient fragmentation and opportunity for differentiated entrants.
What the report delivers — practical, transaction‑grade analysis
Inertia Base Market Research is built to be operationally useful for executives, engineers, and procurement teams. The full report includes:
-
Granular market sizing and top‑down/bottom‑up forecasts across the 2026–2032 horizon, with sensitivity scenarios that stress test demand under alternative construction and retrofit cycles.
-
Buyer personas and procurement playbooks: specification checklists, total cost of ownership models, and lead‑time strategies to reduce install risk and protect equipment warranties.
-
Vendor benchmarking and RFP templates designed to accelerate shortlisting and to surface performance and compliance differentials during supplier selection.
-
Installation and engineering guidance, including recommended concrete‑pour practices, isolator pairing strategies and interface details that preserve start‑up torque and vibration attenuation objectives.
-
Deal support materials — market entry roadmaps, M&A screening criteria, and commercial due diligence modules that quantify addressable opportunity and integration complexity.
Note: this briefing intentionally omits the report’s proprietary segment tables and region/application breakdowns. Access to the full dataset and the interactive model is available through the Inertia Base Market Research portal.
Competitive landscape — who matters and why
The sector is characterized by a mix of specialists and systems suppliers. Established manufacturers combine steel frame expertise with concrete‑fill design, integrated isolator brackets and compliance know‑how. Key players profiled in the report include U.S.‑based specialists that offer concrete‑filled frames and modular pour forms, European engineering firms providing rigid platforms for impact machinery, and regional suppliers that optimize labor‑saving prefabrication.
-
Kinetics Noise Control (USA): Known for concrete‑filled KINETICS® CIB frames in multiple configurations, with emphasis on integrated perimeter channels and isolator brackets. Their product design reflects a focus on lowering center of gravity and controllable amplitude for chillers and large pumps.
-
VMC Group (USA): Offers both seismic and non‑seismic concrete pouring forms and stock inertia bases engineered for HVAC pumps and fans, often coupled with spring isolators for specified deflections; positions itself on compliance and standardized availability.
-
Novia Corporation (USA): Emphasizes manufacturer‑warranty compliance via standard and custom bases that pair with isolation mounts to control start‑up torque and protect rotating equipment.
-
Acrefine (USA): Competes on labor savings through pre‑welded welded steel frames ready for concrete fill, targeting contractors and EPCs seeking reduced site labor.
-
Isotech, ISAT, Vibro‑Acoustics, Farrat, Vibrasystems and Diamond Walraven: Each brings regional strengths — from seismic‑rated systems to rigid platforms for impact machinery — enabling buyers to match technical needs to supply footprint and service expectations.
The competitive dynamic favors suppliers that combine product engineering (frame geometry, isolator interface, pour depth optimization) with regulatory competence and rapid delivery. Market share concentration data underscores opportunity for focused M&A to build full‑suite capabilities or expand channel reach.
Supply chain, materials and installation dynamics
-
Primary inputs: Structural steel channels/I‑beams, rebar and concrete pours remain the dominant bill of materials. Typical concrete fill depths (commonly in the 6–12 inch range) materially influence mass and vibration damping characteristics and are a recurring engineering decision in the specification process.
-
Prefabrication vs. field fabrication: Pre‑welded frames and stock inertia bases materially reduce on‑site labor, shorten schedules and limit variability in final inertial properties — a key differentiator in urban retrofit projects with constrained installation windows.
-
Logistics and lead times: Heavy, bulky frames and site pour coordination create friction. Suppliers that streamline on‑site coordination (pre‑cut rebar cages, integrated isolator brackets, engineered pour sequencing) win on total installed cost.
Regulatory and standards landscape
Compliance with building and vibration control standards is an active demand driver. ASHRAE guidance and IBC seismic requirements are elevating technical thresholds for inertia base design, particularly where seismically rated isolators are specified. The practical effect: procurement teams increasingly require documented compliance and testing evidence — a factor that can lengthen evaluation cycles but raises barriers to low‑cost, non‑compliant suppliers.
Strategic implications & recommendations for 2026
For executive teams preparing 2026 budgets and roadmaps, the report crystallizes several pragmatic courses of action. Below are prioritized recommendations drawn from scenario analysis and buyer economics.
-
Prioritize specification‑led differentiation: OEMs and suppliers should embed isolator interface standards and compliance documentation into product offerings to capture higher‑margin, specification‑driven demand.
-
Invest in prefabrication and modularity: Allocate capex to modular frame production and pre‑welded inventories to reduce lead times and site labor exposure — especially valuable in retrofit and time‑sensitive projects.
-
Enhance channel and service footprint: Expand local service presence or partner with regional installers to overcome logistics constraints and to shorten sales cycles that are lengthened by seismic and warranty reviews.
-
Pursue targeted M&A or JV plays: The market concentration profile suggests attractive roll‑up economics for mid‑market players that can acquire complementary engineering capability or broaden geographic scope without eroding margins.
-
Embed compliance into go‑to‑market: Make IBC and ASHRAE compliance a visible part of product messaging; provide pre‑validated documentation packages to specifiers to accelerate approvals.
Use cases where the report adds immediate ROI
-
Large facilities and data centers planning multi‑year chiller or pump refresh cycles can use the report’s TCO models to compare install and lifecycle costs across base types and isolator pairings.
-
Contractors and EPCs evaluating pre‑fabricated vs. field‑fabricated strategies can quantify labor savings and schedule risk reduction to support bid decisions.
-
Private equity and corporate development teams can accelerate commercial diligence with vendor scorecards and scenario valuation models tailored to inertia base product lines.
How to act on these insights
PW Consulting recommends three near‑term steps for 2026 planning cycles:
-
Run a three‑month vendor audit focused on compliance documentation and delivery performance to reprioritize preferred suppliers before bid season.
-
Pilot prefabricated frame adoption on one major retrofit project to validate labor and schedule benefits, then scale on subsequent programs.
-
Engage PW Consulting’s market modeling module to overlay your portfolio and supplier roster against regional demand scenarios and the report’s forecast to quantify upside and downside by quarter.
Next steps and how to get the full intelligence
This briefing demonstrates the report’s practical value while intentionally withholding the proprietary regional and application split tables to preserve the tactical advantage for subscribers. The full Inertia Base Market Research package includes the complete segmentation datasets, interactive forecast model (USD Million, historical 2020–2025, forecast 2026–2032), supplier scorecards and downloadable RFP templates. For procurement teams, engineering leads, and strategic investors planning actions in 2026, accessing the full report will enable execution with confidence and measurable ROI.
Contact PW Consulting to request the executive briefing deck, schedule a custom workshop, or license the interactive forecast model for your internal planning and procurement systems.
For detailed analysis of this topic, please visit the official page: Inertia Base Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


