



PW Consulting: Automatic Tool Change Spindle Market to Grow at 5.31% CAGR — Hits $787.8M in 2025 and Eyes $1.13B by 2032 as Asia‑Pacific Leads with $362.1M

Automatic Tool Change Spindle Market 2026: A Strategic Preview for Executive Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Automatic Tool Change Spindle Market
Executive summary
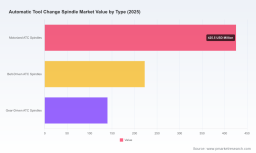
The automatic tool change (ATC) spindle market is moving from niche precision applications toward broad adoption across CNC-based manufacturing. Our latest market model—anchored on a 2025 base year—projects the market expanding from an estimated USD 787.77 Million in 2025 to roughly USD 1,130.82 Million by 2032, representing a compound annual growth rate (CAGR) of 5.31% over the 2026–2032 forecast period. For 2026 planning cycles, this trajectory signals steady, investable growth rather than a short-term bubble; it rewards strategic, capability-focused investments that reduce cycle time, enable lights-out operations, and insulate OEMs and shops from labor volatility.
Automatic Tool Change Spindle Market
Why this matters in 2026
-
Capital allocation: Organizations must prioritize investments that yield near-term efficiency (reduced downtime, fewer manual interventions) and mid-term resilience (supply-chain flexibility, modular upgrades).
Automatic Tool Change Spindle Market -
Technology selection: Differentiation is shifting from raw spindle speed to system-level integration—how spindles, ATC mechanisms, tool management software, and machine controls operate as a cohesive cell.
-
M&A and partnership timing: The market’s steady CAGR creates selective opportunities to acquire strategic suppliers or to form alliances that accelerate time-to-market for modular electrospindles, retrofit ATC systems, and software-enabled tool-life optimization.
Market trajectory and what the numbers reveal
The market path captured by our model shows a clear and continuous recovery and scaling pattern from the early-2020s baseline through the 2026 planning horizon and beyond. Management teams should interpret the mid-single-digit CAGR not as lackluster but as an indicator of disciplined adoption: ATC spindles are being embedded where they deliver quantifiable operational ROI—high-mix, high-speed milling, and lights-out cell deployments—rather than being spec’d indiscriminately.
For decision-makers, the takeaway is practical: prioritize categories and configurations that deliver measurable reductions in unit cost and setup time over a 12–36 month horizon, and treat higher-speed or specialty-bearing solutions as targeted plays for verticals with strong margin support (advanced composites, high-precision aerospace components, and micro-machining for electronics).
Key market dynamics shaping 2026 decisions
-
Labor scarcity and automation acceleration — Skilled CNC labor shortages continue to push shops toward automation. ATC adoption is a pragmatic response to retain throughput and improve scheduling flexibility; expect procurement teams to demand integration packages (spindle + ATC + tool management) rather than point-product buys.
-
Raw material pressure and margin compression — Rising input costs for critical components (notably precision bearings) have translated into meaningful production-cost increases for small and mid-tier manufacturers. Pricing discipline and design-for-cost (DfC) initiatives—standardized modular spindle platforms, alternative bearing suppliers, and service-friendly lubrication systems—will be central to protecting margins.
-
Retrofit and aftermarket growth — As OEMs target installed base monetization, retrofit ATC kits and retrofit-friendly spindle designs are creating a second wave of demand. Service models and upgrade paths will be a competitive differentiator.
-
Regulatory and trade considerations — Import/export dynamics and regional supply concentrations for high-precision components require procurement teams to build multi-sourced strategies and to validate alternate suppliers for critical lead-time risk mitigation.
Competitive landscape: who matters and why
The market is characterized by a mix of specialized spindle manufacturers, regional system integrators, and emerging U.S.-based producers targeting localized demand. Market concentration is moderate—enough to reward scale but still allowing nimble players to capture niche value.
-
GMN USA (USA; subsidiary of GMN Germany) — A technology leader in high-speed CNC spindles with ATC integration. Their product guidance updates underscore the importance of serviceability and selection criteria for high-speed applications. For 2026, GMN’s emphasis on maintenance regimes and high-RPM offerings positions them as a partner for high-throughput, high-precision lines.
-
Celera Motion (Novanta) (USA) — Known for precision air-bearing spindles capable of extreme speeds. Their strengths are in ultra-precision and lightweight-material machining; companies targeting composites and non-ferrous micro-machining will likely continue to evaluate these solutions for select toolpaths where surface finish and thermal stability are mission-critical.
-
Teknomotor (Italy) — A key European provider of electrospindles for wood and aluminum processing. Their rapid tool-change electrospindles are attractive to manufacturers seeking fast changeovers in high-mix lines.
-
Jingjiangcity Jianken (China) — A sizable player in pneumatic ATC spindle motors and air-cooled high-speed models. Their cost-positioning and established product lines make them a natural choice for volume-oriented processing where CAPEX sensitivity is high.
-
CNC Depot (USA) — U.S.-based ATC spindle manufacturer emphasizing routing and milling power levels suitable for light industrial to mid-size production, an appealing option for regional shops prioritizing local support.
-
SPINOGY (Germany) — Modular high-frequency motor spindles designed for full automation. Their modularity is well-aligned with trends toward quick-change tooling ecosystems and robotic integration in milling cells.
-
Air Turbine Tools (USA) — Offers retrofit-minded high-speed spindles with ATC compatibility; their patented mounting approaches are relevant for shops seeking finishing and detail-first upgrades without full machine replacement.
-
PwnCNC (USA) and RapidChange ATC (USA) — Both address a broad range from hobbyist to light industrial segments with modular and affordable ATC solutions; they exemplify the market’s lower-cost innovation tier that widens addressable adoption.
Notable recent developments
-
January 2026 — GMN USA published updated product guidance focused on selection and maintenance of ATC spindles, emphasizing lifecycle planning for high-speed models. This marks a broader industry focus on after-sales support and prescriptive maintenance packages.
-
December 2025 — Sienci Labs released detailed material on integrating automatic tool changers with spindles on CNC routers, reflecting growing ecosystem education and the proliferation of retrofit pathways.
Strategic playbook for 2026
Executives evaluating moves in 2026 should prioritize three strategic vectors: integration, modularity, and risk-managed scale.
-
Integration-first procurement: Buy for cell-level performance, not part-level specs. Procurement should require bidders to demonstrate full-path metrics—cycle-time reduction, mean-time-between-failure (MTBF) under targeted loads, and tool-change time under representative tool libraries.
-
Modular product architectures: Invest in spindles and ATC systems with common mechanical interfaces and standardized communication protocols (e.g., for tool-ID and life-cycle telemetry) to enable faster upgrades and lower total cost of ownership.
-
Service and aftermarket monetization: Build service contracts that include predictive maintenance, spare-parts kits, and retrofit upgrade paths. Service revenue will increasingly offset margin pressure from higher input costs.
-
Retrofit-first growth for OEMs: OEMs should develop validated retrofit kits and channel programs to monetize the installed base; this often has faster payback than new-machine sales in constrained capex environments.
-
Risk-balanced sourcing: Map critical components (especially bearings and high-frequency motor modules), and qualify at least two alternate suppliers to reduce single-point supply risk.
-
Targeted M&A and partnerships: Focus acquisitions on complementary capabilities—sensorized tool interfaces, robotics-ready spindle couplers, and software tool-management platforms—rather than broad, horizontal consolidation.
What’s inside the full PW Consulting report (practical, operational deliverables)
Our report is designed as an operational toolkit for 2026 planning cycles. Highlights include:
-
Market model with annualized forecasting through 2032, scenario sensitivity analyses, and a downloadable dataset for internal financial modeling.
-
Supplier scorecards covering technology maturity, support footprint, retrofit compatibility, warranty terms, and service economics.
-
Tool-change and spindle TCO calculators to model CAPEX/OPEX trade-offs for new machines vs retrofit, including service-plan scenarios and spare-parts stocking strategies.
-
Supply-chain risk maps and mitigation playbooks focused on critical bearing suppliers and motor-component concentration risks.
-
Case studies across representative verticals illustrating practical adoption pathways, measured ROI, and lessons learned in production ramp-up.
-
Technology maturity and IP landscape assessments that identify near-term disruptors (modular electrospindles, air-bearing high-speed units) and where to position R&D bets.
-
Actionable go-to-market and after-market service strategies for OEMs and independent retrofitters—complete with channel-development checklists and a prioritized list of capability gaps to close in 12–24 months.
Call to action
The Automatic Tool Change Spindle Market is no longer a narrow engineering curiosity—it's an operational lever for resilience, productivity, and near-term margin protection. For 2026 capital plans, the question is not whether to engage with ATC technology, but how to engage: which vendors to partner with, which retrofit pathways to enable, and how to structure service economics to preserve margins in a tightening input-cost environment.
PW Consulting’s full report provides the granular vendor intelligence, scenario models, and executable playbooks your leadership team needs to move from aspiration to measurable outcomes. To access the complete dataset, supplier appendices, and executable templates referenced in this briefing, visit our report page and download the full study.
For detailed analysis of this topic, please visit the official page: Automatic Tool Change Spindle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


