



PW Consulting: Industrial Smart Helmet Market Poised to Reach USD 2,058.16 Million by 2032, Expanding at a 14.25% CAGR

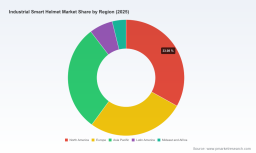
Industrial Smart Helmet Market — 2026 Strategic Preview
As enterprises evaluate connected-worker strategies for 2026, PW Consulting’s latest Industrial Smart Helmet Market Research report provides a pragmatic intelligence package designed to convert safety investments into operational advantage. This preview highlights the report’s strategic value for executive decision makers: it synthesizes the market’s rapid scale-up, identifies the supplier archetypes reshaping procurement, and prescribes an actionable playbook for pilots, sourcing and enterprise integration — while reserving the full segment-by-segment detail for the published study.
Industrial Smart Helmet Market Research
Market trajectory you cannot ignore
The industrial smart helmet market has transitioned from niche experimentation to measurable commercial adoption. Our analysis shows the market expanding from a historical base of several hundred million USD in 2020 to USD 810.0 Million in the report’s base year (2025), driven by cross-sector demand for real‑time hazard detection, worker health monitoring and compliance automation. Over the forecast window, the market is projected to grow at a compounded annual growth rate (CAGR) of 14.25%, reaching an estimated USD 2,058.16 Million by 2032.
Industrial Smart Helmet Market Research
Why this top-line matters for 2026 planning: the growth rate is sufficiently steep to change supplier economics, accelerate ecosystem partnerships (connectivity, AR, RTLS, AI) and force procurement teams to decide between pre-integrated platform helmets and modular, upgradeable architectures. Our report quantifies these inflection points and models downstream effects on TCO, deployment velocity and operational KPIs.
Industrial Smart Helmet Market Research
What PW Consulting’s report delivers — pragmatic, decision-ready assets
- Market sizing & trajectory model: An auditable top-down and bottom-up model covering historical (2020–2025) performance and a 2026–2032 forecast, enabling scenario stress‑testing against price, material and regulatory shocks.
- Vendor benchmarking toolkit: A multi-dimensional supplier scorecard that evaluates product architecture, certification footprint (ATEX/IECEx/CSA/ANSI readiness), integration openness (APIs, RTLS, cloud connectors), and field-proven durability.
- Feature-to-value matrices: Comparative mapping of sensor suites (impact, fall, gas, biometrics), connectivity options (4G/5G, BLE, LoRa), and human‑machine interfaces (AR, voice, HUD) against operational use cases.
- Procurement and contracting playbook: Standardized RFP language, acceptance tests for intrinsically safe environments, pricing model templates (capex vs. opex), and service-level clauses for firmware/security updates and recall scenarios.
- Integration & deployment blueprints: Step-by-step pilots, systems integration checklists (RTLS, MES, EHS platforms), cybersecurity hardening guidance, and workforce change management plans tuned to frontline realities.
- ROI and risk simulations: Customizable TCO models that factor in raw material price volatility, maintenance, training, and anticipated productivity and safety outcomes for 12–36 month horizons.
- Case studies & lessons learned: Vendor-agnostic illustrations from oil & gas, mining, construction and heavy manufacturing that reveal common pitfalls and high-impact tactical levers.
Competitive landscape: supplier archetypes and strategic implications
The vendor universe is evolving into several distinct archetypes — platform incumbents, specialized hardware innovators, connectivity-driven entrants and system integrators — each requiring a different sourcing approach.
- Platform incumbents with certification focus: Established safety OEMs are extending into connected helmets by integrating proven impact-protection technology with digital monitoring. Their strategic strength is trust and certification credentials for hazardous locations; they are the natural choice where compliance and intrinsic safety certificates are primary procurement constraints.
- Connected-hardware innovators: Newer players are differentiating on sensor richness and embedded connectivity. Products that combine fall/impact detection, environmental sensing and multi-radio connectivity enable turnkey deployments in brownfield contexts where retrofitting is required.
- Telecom/5G and AI-driven entrants: Vendors integrating 5G and AI analytics push the upper bound of real-time capabilities (live video, edge analytics, computer vision alerts). These entrants accelerate advanced use cases (remote guidance, automated hazard detection) but typically require stronger integration discipline and network investments.
- Integration platforms and AR partners: Suppliers that position as systems integrators or AR enablement platforms provide the glue for complex deployments — prioritizing interoperability, lifecycle services and field support.
Representative companies profiled in the report illustrate these archetypes and offer concrete lessons:
- A supplier from Sweden recently announced an industrial-grade helmet integrating impact/fall sensors and advanced brain‑protection systems — a move that signals consolidation of hardware safety heritage with connected alerts.
- A China/UAE collaboration markets modular IoT helmets with customizable sensors and solar options, demonstrating how regional deployments (including major oilfield projects) favor configurable solutions.
- Another entrant released a 5G-enabled helmet combining AI and wearable sensors, underscoring how advanced connectivity can enable new remote‑guidance and monitoring services.
- Traditional safety-head protection manufacturers continue to defend their installed base by adding advanced protection features and integration pathways for connected-workforce platforms.
Market concentration is moderate: the top three vendors account for roughly a third of supply, while the top five approach the mid‑40% range — a structure that supports both scale advantages and continued innovation from smaller vertical specialists. This balance creates opportunities for partnerships, white‑label arrangements and strategic OEM relationships.
Operational dynamics reshaping procurement in 2026
Several dynamics that buyers must bake into 2026 decisions are explored in detail in the report:
- Material-cost volatility: Fluctuating prices for ABS, polycarbonate and EPS foam have pushed component costs materially higher since 2021, impacting unit economics and supplier pricing strategies. Procurement teams should model scenarios with input cost inflation baked into multi-year contracts.
- Certification & regulatory pressure: Compliance with ANSI/ISEA Z89.1 and hazardous‑location standards remains a gating factor for many industrial deployments. Buyers must align technical requirements with certification timelines and third‑party testing schedules to avoid roll-out delays.
- Sectors driving adoption: Oil & gas, mining and construction continue to lead demand because of acute safety risk profiles and existing regulatory focus. These sectors also push suppliers to deliver ruggedized, intrinsically safe variants and turnkey integration services.
- Integration complexity: The real effort in connected-helmet programs is rarely the helmet hardware; it is the enterprise integration (RTLS, EHS systems, identity and access management) and the data governance model that turns sensor feeds into predictable safety outcomes.
Strategic playbook for 12–24 month execution
- Start with a narrowly scoped pilot: Identify a single high-risk process line, specify clear safety and productivity KPIs, and run a 90–120 day pilot with defined acceptance criteria.
- Prioritize certifications and retrofit compatibility: Favor solutions that meet required safety certifications out of the box, and that offer modularity for future sensor upgrades.
- Insist on integration APIs and lifecycle SLAs: Require vendor commitments on firmware updates, cyber‑patching windows and interoperability standards as part of procurement contracts.
- Model TCO and break-even under input-cost scenarios: Use dynamic TCO templates that include material-cost stress tests and different service models (subscription vs. capital purchase).
- Plan data governance before scaling: Define who owns the sensor data, how PII is handled, and the rules for cross-system alerts to prevent operational noise and ensure accountability.
- Design for human factors: Field acceptance depends on comfort, battery life, and clear value to the worker; incorporate frontline pilots into supplier selection criteria.
Executive value proposition — what the full report unlocks
For leaders who must allocate capital and operational attention in 2026, the full PW Consulting report supplies the decision support necessary to move from exploratory pilots to scaled programs: validated market sizing, supplier scorecards, procurement templates, TCO models with stress scenarios, and case-proven deployment blueprints. Critically, while this preview highlights the market’s trajectory and the strategic choices companies face, the detailed segmentation, regional and application breakdowns, and vendor-specific scoring matrices are available only in the full report to ensure decision makers receive the complete, auditable dataset needed for contract negotiations and board-level planning.
To access the comprehensive analysis, including the full vendor evaluation and the downloadable modeling toolkit that supports 2026 budget decisions, please visit PW Consulting’s Industrial Smart Helmet Market Research page or contact our strategic advisory team for an executive briefing tailored to your sector and operational footprint.
For detailed analysis of this topic, please visit the official page: Industrial Smart Helmet Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


