



PW Consulting: Oil and Gas Storage and Transportation Market to Expand at 5.28% CAGR During 2026–2032, Fueling Strong Global Demand

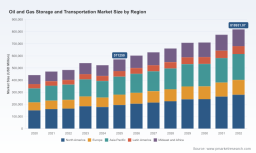
Oil & Gas Storage and Transportation Market — Strategic Intelligence for 2026 Decisions
PW Consulting’s latest market research brief on the Oil and Gas Storage and Transportation Market delivers a focused, decision-ready synthesis for executives planning capital allocation, M&A, and operational realignment in 2026. Built on a 2025 base with historical coverage from 2020–2025 and a forward-looking forecast window to 2032, the analysis combines macro trajectory, regulatory inflections, and competitive dynamics to highlight where value will concentrate — and where ambiguity will persist — over the next investment cycle.
Oil And Gas Storage And Transportation Market
Market Trajectory: Growth with Strategic Nuance
The market we cover is sizeable and expanding. Using 2025 as the base year, our top-line modeling projects continued growth at a mid-single-digit compound annual growth rate (CAGR) of approximately 5.28% across the 2026–2032 forecast horizon. Put differently, the total market expands meaningfully from the 2025 baseline as energy system complexity, resilience requirements, and new midstream use-cases (including CO2 and hydrogen logistics) exert upward pressure on capacity, service demand, and infrastructure spend.
Oil And Gas Storage And Transportation Market
This topline momentum masks a nuanced set of value pools. While the aggregate opportunity is material, the distribution of returns will be heavily influenced by regulatory shifts, geopolitical events, and the speed with which incumbent operators retrofit assets for new payloads and compliance requirements. PW Consulting’s brief frames these nuances so that management teams can prioritize options that preserve optionality while capturing near-term revenue streams.
Oil And Gas Storage And Transportation Market
Key Dynamics Shaping 2026 Decision-Making
- Inventory normalization and volatility: Recent official reports show global observed oil stocks at multi-year highs in early 2026, with central governments holding a significant emergency stock buffer. These elevated stock levels, combined with episodic draws and the reallocation of floating storage, raise operational questions for storage operators: balancing utilization-linked revenues against the capital cost of idle capacity and the risk of protracted low-turnover periods.
- Strategic releases and emergency exchanges: Actions such as government crude exchanges and strategic reserve operations in 2026 have immediate pricing and logistics implications. These events can create transient spikes in demand for terminal handling and short-term transportation while compressing margins for prolonged stretches if inventory releases persist.
- Large-scale project rollouts: Major upstream and midstream project awards and expansions — including multi-billion-dollar field development phases and associated pipeline and fractionation works — are catalyzing localized demand for storage expansions and new export logistics. These programs create contractor and service-provider pipelines, but they also intensify competition for engineering, procurement, and construction capacity.
- Energy transition and new payloads: Existing transport and storage corridors are increasingly evaluated for CO2, hydrogen, and captured byproduct handling. National programs projecting large-scale CO2 transport requirements by 2030 create strategic optionality for midstream operators willing to invest in retrofits or dual-use designs.
- Regulatory pressure on downstream energy use: Projections of declining transport-sector energy demand under stricter emissions standards introduce medium-term downside risk for refined product logistics, even as petrochemical and LNG flows provide countervailing sources of demand.
What the Report Delivers — Practical, Executable Intelligence
The PW Consulting report is structured to move quickly from diagnosis to execution. It provides:
- Actionable scenario roadmaps that quantify exposure under alternative oil inventory, demand, and regulatory pathways — enabling CFOs and strategy teams to stress-test balance sheets and capex timetables.
- Operational playbooks for terminals and pipeline operators that cover short-term utilization optimization, dynamic tariff strategies, and contractual constructs to manage volatility risk.
- Investment prioritization matrices to evaluate retrofit versus greenfield options for emerging payloads (CO2, hydrogen, LNG), including practical permitting and timeline overlays.
- M&A and partnership frameworks that identify the types of assets and geographic footprints that are most accretive under 2026 market realities while preserving long-term transition optionality.
- Commercial templates for storage and transportation contracts — including recommended clauses for force majeure, inventory exchange, and capacity flexibility — informed by 2026 contract activity and public-sector interventions.
To preserve competitive confidentiality and support client acquisition, the report intentionally reserves granular segment-level tables and regional share specifics for the full publication; the executive brief emphasizes strategic lines of sight while withholding detailed splits that would reveal proprietary allocations.
Competitive Landscape: Fragmented Scale, Concentrated Capabilities
The incumbency in storage and transportation blends global independent terminal operators, integrated midstream systems, and state-backed oil companies. Market concentration metrics indicate a moderately fragmented landscape: the top three and top five players do not command dominant shares, leaving meaningful room for regional champions and nimble independents to capture specialized value.
Key players profiled in the report include:
- Royal Vopak N.V. (Rotterdam, Netherlands) — Global independent tank storage operator with extensive terminal footprint: https://www.vopak.com/
- Kinder Morgan, Inc. (Houston, TX, USA) — Large North American midstream operator with pipeline and storage systems: https://www.kindermorgan.com/
- Enbridge Inc. (Calgary, Canada) — One of the world’s longest liquids transportation systems: https://www.enbridge.com/
- Enterprise Products Partners L.P. (Houston, TX, USA) — Integrated NGL, crude and product network with significant Gulf Coast capacity: https://www.enterpriseproducts.com/
- Energy Transfer LP (Dallas, TX, USA) — Major pipeline-focused operator with complementary storage assets: https://www.energytransfer.com/
- Saudi Aramco (Dhahran, Saudi Arabia) — State-backed operator with very large strategic tank farms and export infrastructure: https://www.aramco.com/
- China National Petroleum Corporation (CNPC) (Beijing, China) — National operator with strategic reserve and terminal assets: https://www.cnpc.com.cn/
- Oiltanking GmbH (Hamburg, Germany) — Independent global tank storage provider: https://www.oiltanking.com/
- TC Energy Corp. (Calgary, Canada) — Extensive gas and liquids pipeline systems: https://www.tcenergy.com/
- Buckeye Partners, L.P. (Houston, TX, USA) — Focused on product pipeline transport and bulk storage: https://www.buckeye.com/
- Vitol Tank Terminals International BV (VTTI) (Rotterdam, Netherlands) — Global independent storage operator: https://www.vtti.com/
- ADNOC Terminals (Abu Dhabi, UAE) — Regional anchor for crude storage and export nodes: https://www.adnoc.ae/
For 2026 strategy, the competitive calculus is two-fold: (1) defend or expand core cash-generating storage and throughput assets to preserve immediate revenues and (2) selectively pursue technical adjacencies (CO2 hubs, hydrogen-ready terminals, NGL fractionation interfaces) that offer asymmetric upside as policy and project awards crystallize.
Near-Term Signals and Recent Developments
- Government-managed inventory actions in 2026 — including strategic crude exchanges — have immediate operational and price effects that necessitate dynamic contractual and scheduling tools on the commercial side.
- Large-scale contract awards and field development programs announced or advanced in late 2024–2026 are creating concentrated demand pockets for storage, fractionation, and pipeline construction capacity in certain regions.
- Policy projections and industrial programs targeting CO2 transport and storage open a parallel value stream for midstream incumbents prepared to retrofit networks and develop integrated hub solutions.
Strategic Playbook for 2026
Executives should treat 2026 as a year of selective defensive investment and option-building. Tactical priorities we recommend include:
- Locking in flexible capacity contracts and hedged pricing arrangements to protect cash flow against inventory releases and demand shocks.
- Prioritizing retrofits and pilot projects that establish technical competence in CO2 and hydrogen handling without committing full-cycle greenfield capital.
- Reassessing long-lead procurement and EPC pipelines in light of large project awards to avoid cost escalation and schedule slippage.
- Pursuing tuck-in acquisitions and joint ventures that expand terminal connectivity or provide access to specialized product flows (e.g., NGL fractionation, LNG bunkering) with clear IRR hurdles.
- Integrating digital twin and predictive maintenance solutions to reduce operating expenses and increase terminal throughput reliability under variable utilization.
How PW Consulting’s Report Enables Better 2026 Outcomes
Our report is designed to be a working tool for strategy and commercial teams — not an academic exercise. It includes modular decision templates, scenario dashboards, and negotiated contract language that teams can adapt immediately to board-level capital calls or to inform discussions with financiers and partners. By anchoring recommendations to the 2025 base and modeling multiple 2026-relevant scenarios out to 2032, we provide both a short-term operational compass and a longer-term strategic map.
Next Steps
For C-suite and board teams preparing 2026 budgets and capital plans, the immediate value is twofold: rapid identification of low-regret investments that preserve cash generation, and a prioritized list of optionality-preserving moves that position an enterprise to participate in emerging midstream segments. The full PW Consulting market report contains the granular regional and service-level splits, proprietary modeling workpapers, and contract templates referenced above. These materials — intentionally withheld from this briefing to preserve client advantage — are available through our report portal.
To access the complete dataset, scenario models, and the full strategic playbook, please visit the PW Consulting report landing page or contact our industry desk for a tailored briefing.
— PW Consulting, Oil & Gas Storage and Transportation Market Intelligence Team
For detailed analysis of this topic, please visit the official page: Oil And Gas Storage And Transportation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


