



PW Consulting Forecasts Next‑Gen Supply Chain Market to Reach USD 132.96 Billion by 2032, Growing at an 11.4% CAGR as AI and IoT Drive Adoption

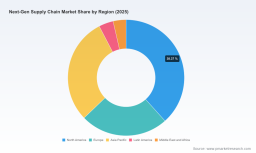
Next Gen Supply Chain Market — A 2026 Strategic Preview
PW Consulting’s new Next Gen Supply Chain Market report, grounded in a 2025 base year and covering historical performance from 2020–2025 with a forecasting horizon through 2026–2032, is written for executives who must make hard portfolio, technology and footprint decisions in 2026. The high-level market trajectory is stark: the addressable market grows at a compound annual growth rate (CAGR) of 11.4%, moving from a 2025 baseline of USD 62,450.0 Million to an expected USD 132,962.37 Million by 2032. That doubling over the forecast period creates both urgency and optionality — and it reframes how boards, CIOs and supply chain chiefs prioritize capital and talent allocation.
Next Gen Supply Chain Market
Why this report matters for 2026 decision cycles
-
Investment triage under constrained capital: With digital and physical automation competing for capital, the report gives CFOs and COOs a prioritized roadmap of where—and critically when—to invest to realize measurable resilience and cost-to-serve improvements in the coming 12–36 months.
Next Gen Supply Chain Market -
Bridging proof-of-concept to scaled deployment: We translate pilot results into enterprise-scale decision criteria. The report includes scenario-based ROI lenses and playbooks that remove “pilot paralysis” and provide a clear escalation path from a 6–9 month pilot to a 24-month scaled program.
Next Gen Supply Chain Market -
Risk-aware technology sequencing: Rather than a technology checklist, the deliverable positions AI/agentic systems, edge IoT, robotics and cloud-native orchestration on a sequenced adoption curve. This helps executives balance near-term tactical wins (visibility, orchestration) with longer-term structural bets (autonomous execution, networked marketplaces).
-
Infrastructure and operational economics: The report integrates infrastructure realities—rising data center power and cooling demands driven by AI workloads—into TCO modeling. Procurement and IT leaders get actionable guidance on aligning infrastructure upgrades with application rollouts to avoid stranded assets or capacity shortfalls.
What’s in the report — the practical toolkit
We designed the report as a decision-ready toolkit rather than a purely academic market study. Highlights include:
-
Executive decision frameworks for portfolio prioritization that align strategic KPIs (service, cost, carbon) to investment horizons.
-
Implementation playbooks: vendor selection criteria, contract negotiation levers, pilot-to-scale governance templates and outcome-based SOW examples.
-
Scenario-based financial models and stress tests that account for geopolitical shocks, supplier disruption, and energy-cost volatility tied to AI infrastructure demand.
-
Operational scorecards and leading indicators for measuring AI/automation maturity, from data readiness through productionization and ongoing model governance.
-
Partner & ecosystem matrix: capability match-ups across software, robotics, intralogistics and systems integrators, with recommended bundled approaches for common enterprise archetypes.
-
Regulatory and compliance playbook—how to operationalize traceability and data governance in light of new product data requirements—plus a checklist to align supplier onboarding and contract clauses.
Note: This press release emphasizes strategic conclusions and tools. Detailed segment-level tables, regional and end-user breakdowns, and the proprietary financial schedules that underpin our models are reserved for the full report and subscriber portal.
Competitive landscape — positioning the players
The Next Gen Supply Chain ecosystem is an assembly of enterprise software leaders, niche specialized platform providers, robotics and intralogistics OEMs, and systems integrators. Our competitive analysis recognizes three dynamic fronts: orchestration and planning platforms, execution and fulfillment automation, and enabling infrastructure (data centers, compute, and connectivity).
-
SAP SE (Walldorf, Germany) — Strengths: integrated planning-to-orchestration platforms and an accelerating AI-agent capability set that aims to embed decision support across procurement, planning and execution layers.
-
Oracle Corporation (Austin, Texas) — Strengths: end-to-end cloud SCM with deep integration into enterprise suites, attractive for organizations seeking unified ERP-SCM roadmaps.
-
IBM Corporation (Armonk, New York) — Strengths: B2B connectivity and AI-infused supply chain intelligence that tie into long-standing enterprise integration footprints.
-
Blue Yonder — Strengths: advanced demand forecasting and inventory optimization built around AI/ML models; well-suited for retailers and fast-moving CPG.
-
Kinaxis — Strengths: concurrent planning and rapid scenario modeling for organizations prioritizing real-time orchestration and “what-if” agility.
-
Manhattan Associates, E2open, GEP, Descartes — Strengths: specialized execution stacks (warehouse, transportation, procurement and logistics routing) that integrate into broader orchestration layers.
-
Dematic, SSI Schaefer, Vanderlande, Swisslog, Daifuku, TGW — Strengths: proven intralogistics and material handling systems providers that convert digital plans into high-throughput physical operations.
-
GreyOrange, Locus Robotics, Hai Robotics — Strengths: agile robotics and AMR strategies targeting rapid fulfillment throughput gains and flexible labor augmentation.
Market concentration remains low relative to many enterprise technology sectors—our concentration analysis (CR3 at ~18.5% and CR5 near ~28.3%) signals an industry that still rewards integration strategies, partnerships and solution architecture innovation rather than single-vendor dominance. This fragmentation creates opportunities for systems integrators and niche specialists to capture value through verticalized solutions and outcome-based pricing.
Macro dynamics that will shape 2026 plays
-
Regulation is converting products into data assets: Initiatives such as digital product passport requirements are increasing traceability obligations. Companies that treat products as data centric will derive outsized compliance and circularity advantages.
-
Infrastructure demands from AI: Rising AI workloads are exerting material pressure on data center power and cooling. Organizations must treat compute and energy as strategic inputs to supply chain digital twins and advanced analytics deployments.
-
Technology adoption momentum: Independent research shows that a majority of executives now rank next-gen supply chain among the top three technology trends and that transformation progress has accelerated into 2025. Expect vendor roadmaps to emphasize agentic automation and autonomous execution capabilities in 2026.
-
Geopolitical volatility: Shifting trade policy and regional risk are prompting multi-regional footprint strategies—reshoring where necessary and diversifying supplier networks—altering where companies invest in fulfillment and inventory infrastructure.
Recent vendor and market signals to watch in 2026
-
SAP’s orchestration and AI-agent roadmap signals that enterprise vendors will move rapidly from planning augmentation to prescriptive, action-oriented orchestration.
-
Hardware and infrastructure vendors are expanding AI-ready solutions—expect closer alignment between compute vendors and supply chain software providers to reduce deployment friction for large-scale AI projects.
-
Industry recognition and awards programs are increasingly valuing execution capability; leading adopters are being rewarded for tangible productivity and network redesigns rather than proofs of concept alone.
How to use the report in your 2026 playbook
-
Build a 12–36 month capital allocation plan that sequence pilots, infrastructure upgrades and labor transformation in lockstep. Use the scenario models in the report to stress-test outcomes under different geopolitical and energy-cost assumptions.
-
Establish a vendor selection protocol that weights integration risk, long-term TCO and outcome-based contracting. Leverage our orchestration-first adoption pattern to avoid “rip-and-replace” shocks.
-
Operationalize data governance: align supplier onboarding, traceability requirements and product-as-data initiatives with tactical projects to minimize compliance cost and time-to-value.
-
Prioritize workforce reskilling and center-of-excellence formation. The success of automation investments will hinge as much on governance, change management and data literacy as on technology capability.
A transparent trailer: what we hold back to drive value
In keeping with the “trailer” approach, this release outlines critical strategic directions, competitive positioning and executable frameworks — but it does not reproduce the report’s full segment-level financial tables, region-by-region breakdowns, or the proprietary vendor scoring matrices. Those analytical artifacts and the full set of model inputs/assumptions are available in the subscriber version of the report and on the PW Consulting portal. For teams building 2026 budgets and vendor roadmaps, the full report contains the drill-down intelligence required to finalize supplier shortlists, create investment cases and execute procurement milestones.
Closing perspective
The next two years will determine whether organizations treat next-generation supply chain initiatives as ornamental or structural. The market trajectory and the macro forces described here argue persuasively for a structural response: invest with discipline, sequence capabilities to capture early cashflow benefits, and guard against infrastructure mismatches that can turn fast growth into stranded cost. PW Consulting’s Next Gen Supply Chain Market report is designed to make those 2026 strategic choices less risky and more repeatable. To access the full analysis, detailed models and implementation templates, visit the PW Consulting report page and download the complete study.
For detailed analysis of this topic, please visit the official page: Next Gen Supply Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


