



PW Consulting: Carbon Thermoplastic Market to Reach USD 3,451.79 Million by 2032, Expanding at an 8.5% CAGR

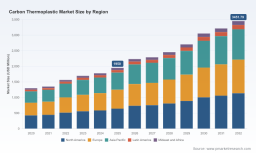
Carbon Thermoplastic Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As global manufacturers accelerate the shift to lighter, faster and more sustainable platforms, carbon-reinforced thermoplastics are entering a strategic inflection point. PW Consulting’s latest Carbon Thermoplastic Market report — using 2025 as its base year and a forecast horizon through 2032 — synthesizes market dynamics, supplier economics and near-term disruption vectors into an actionable playbook for corporate leaders making capital allocation, sourcing and product-development decisions in 2026.
Carbon Thermoplastic Market
Headline Market View
The carbon thermoplastic market stood at roughly USD 1.95 billion in 2025 and is projected to expand robustly over the coming planning cycle. Our modeling anticipates a compound annual growth rate (CAGR) of 8.5% across the 2026–2032 forecast window, driving the market to an estimated ~USD 3.45 billion by 2032. Concentration metrics indicate a market that is neither monopolized nor atomized: the top three players account for a meaningful share of supply while the top five approach half the market, leaving a competitive middle ground where scale and specialization both matter.
Carbon Thermoplastic Market
Why This Matters for 2026 Strategic Decisions
- Capital allocation and capacity planning: An 8.5% CAGR creates a compelling case for phased capacity expansion models rather than one-off large capital commitments. Companies must evaluate modular, repeatable plant designs and production lines that can be scaled incrementally to match adoption curves in transport and industrial end-markets.
- Supply chain resilience: Feedstock and precursor availability, logistics constraints, and evolving trade measures will continue to shape landed costs. Buyers in 2026 should prioritize multi-sourcing strategies and regional buffer inventories to mitigate episodic tightness.
- Commercial strategy for OEMs: With rising demand from EV, aerospace and premium automotive segments, OEMs should adopt joint development and supply agreements that align material roadmaps with vehicle-platform timelines to avoid late-stage integration friction.
- Regulatory and sustainability positioning: Regulatory shifts and circularity expectations are accelerating. Firms that can credibly demonstrate recyclability, lower life-cycle emissions, and compliance with regional chemical restrictions will enjoy preferential procurement access and pricing power.
What the PW Consulting Report Delivers — Practical, Decision-Ready Tools
The report is designed as an operator’s toolkit for 2026 planning cycles. It goes well beyond narrative to provide modular, executable assets that executives and functional leaders can use directly in boardroom deliberations and business-planning workshops:
Carbon Thermoplastic Market
- Scenario-based demand models: Three end-market adoption scenarios (Conservative, Base, Accelerated) with modular inputs so teams can re-run forecasts under bespoke assumptions for EV penetration, aerospace OEM ramp schedules and industrial automation adoption rates.
- Total cost of ownership (TCO) templates: End-to-end TCO calculators that compare thermoplastic composites to metal and thermoset alternatives across manufacturing routes (press, compression, thermoforming), enabling real-time trade-off analysis for design and sourcing teams.
- Supplier scorecards and sourcing playbooks: Standardized evaluation templates covering technical capability, quality systems, lead-time reliability, sustainability credentials and geopolitical risk. Includes suggested contract clauses for capacity reservation and price pass-through.
- Technology and process benchmark compendium: Comparative metrics for prepreg, tape, pellet and continuous-fiber compound processes — with key throughput, cycle-time and equipment-cost heuristics to inform CapEx prioritization.
- Regulatory and compliance checklists: Regionally tailored guidance to navigate chemical restrictions, end-of-life obligations and evolving recycled-content reporting requirements.
- M&A and partnership playbook: A mapped landscape of capability gaps and attractive acquisition archetypes (e.g., tape producers, recycling specialists, high-speed molding specialists), paired with valuation influence factors and due-diligence scorecards.
Competitive Landscape: Who to Watch and Why
The market features a mix of large chemical groups, specialized composites houses and targeted compounders. Several incumbents are moving beyond material supply into integrated solutions — an evolution that will be critical to monitor in 2026 as OEMs seek one-stop partners for design-to-production continuity.
- Toray Industries (Tokyo): A technology leader in CFRTP prepregs, Toray’s recent product introductions target automotive mass-production compatibility. Expect continued emphasis on lowering cycle times and maximizing fiber utilization.
- Syensqo / Solvay (Alpharetta, GA): Capacity expansions focused on EV demand signal an intent to secure OEM agreements; watch for downstream integration plays and long-term supply contracts in North America.
- Teijin Limited (Tokyo): With established PA and PEEK-based offerings, Teijin remains a key player for high-performance industrial and aerospace segments; certification milestones are a recurring differentiator.
- Mitsubishi Chemical Group (Tokyo): A strong position in prepregs and compounds for automotive and sporting goods, the group’s global footprint supports rapid customer qualification cycles.
- Arkema (Colombes): Innovator in recyclable resin systems, Arkema’s approaches to circularity create valuable differentiation for environmentally sensitive programs.
- Hexcel (Stamford, CT), SGL Carbon (Wiesbaden), Gurit (Wattwil): These firms combine aerospace pedigree with higher-rate production capabilities; partnerships with vehicle OEMs are an emerging vector.
- PlastiComp and Lingol: Niche specialists enabling high-volume, cost-sensitive applications through long-fiber compounds and pelletized inputs — critical enablers for commoditized adoption curves.
Recent corporate moves — product launches, capacity investments and strategic partnerships — are accelerating the pace at which thermoplastic composites become manufacturable at scale. For 2026 planners, tracking these developments and benchmarking against your internal roadmaps is essential to avoid downstream supply or qualification delays.
Key Market Dynamics and Risk Factors
- Feedstock and precursor supply: Carbon precursor availability and pricing trends remain the single-most important upstream lever. Firms should stress-test procurement strategies against prolonged tightness scenarios and consider strategic investments or off-take arrangements.
- Regulatory headwinds: Chemical restrictions in major markets are tightening; materials relying on legacy flame retardants face higher compliance burdens and potential redesign costs. Proactive materials substitution and early engagement with regulators reduce go-to-market friction.
- Trade and logistics: Changing tariff regimes and freight-cost volatility can materially shift landed economics by region. Nearshoring and regional production hubs are viable hedges for companies with high volume needs.
- Manufacturing technology barriers: High-temperature chemistries (e.g., PEEK) impose process constraints and capital intensity that limit near-term commoditization; for many OEMs, mid-temperature systems and novel recyclable resins offer the best near-term scale-up path.
- Market consolidation potential: Given current concentration levels, 2026 is likely to see continued M&A and JV activity as firms seek scale and integrated capabilities — creating both risk and opportunity for incumbents and challengers.
Recommended 2026 Playbook — Prioritized Actions
- Run a six-month supplier stress test: Validate second-source capabilities for critical precursors and semi-finished goods; secure conditional capacity reservations aligned with platform launch windows.
- Adopt modular CapEx plans: Favor repeatable cell designs and leasing options for equipment to preserve optionality while accelerating time-to-market.
- Accelerate regulatory-proofing: Launch materials substitution pilots for at-risk chemistries and obtain early certifications for recyclability and flame-retardant compliance in target markets.
- Pursue selective vertical moves: Consider bolt-on acquisitions that close capability gaps (e.g., high-rate tape producers or recycling technology firms) rather than horizontal roll-ups that dilute focus.
- Embed TCO into design gates: Make full TCO comparisons mandatory in early design stages to ensure composites choices are evaluated on manufacturability and lifecycle economics, not just part-level mass savings.
- Design strategic partnerships: Negotiate JDA/JDP structures with material suppliers that align incentives across qualification timelines, volume ramps and long-term pricing.
How PW Consulting Supports Your 2026 Agenda
Our full report equips executive teams with the quantitative models, supplier intelligence and scenario tools described above — delivered alongside facilitated strategy workshops and bespoke modeling to adapt the outputs to your product roadmaps and procurement cycles. The deliverables include editable spreadsheets, negotiation playbooks and a prioritized action plan calibrated to your organization’s risk appetite and time horizon.
Next Steps: Where to Find the Full Intelligence
This briefing surfaces the strategic contours you need to make informed decisions in 2026 while reserving the granular segment- and customer-level tables that drive execution. For access to the full dataset, detailed segment models and the supplier diligence annex — including downloadable TCO templates and M&A target maps — please visit the PW Consulting Carbon Thermoplastic Market report page. The complete report contains the granular breakdowns, regional and application models, and proprietary valuation assumptions that corporate teams use to finalize budgets and contractual commitments.
PW Consulting stands ready to brief executive teams, run tailored scenario workshops, and partner on transaction diligence. Contact your PW Consulting engagement lead to schedule a strategy session and obtain the full report materials.
For detailed analysis of this topic, please visit the official page: Carbon Thermoplastic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


