



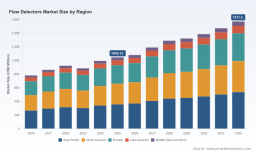
PW Consulting: Flaw Detectors Market Hits USD 1,045.13 Million in 2025, Poised for 6.0% CAGR to USD 1,571.5 Million by 2032

Flaw Detectors Market 2026: Strategic Insights for Action — PW Consulting Official Release
PW Consulting today publishes an executive briefing of our newly released Flaw Detectors Market research — an operationally focused intelligence pack designed to inform boardroom strategy, procurement decisions, and M&A screening through 2026 and beyond. Built on a 2020–2025 historical dataset (base year 2025) and a detailed forecast for 2026–2032, the report synthesizes market sizing, competitive positioning, technology trajectories, and risk factors into actionable guidance for industrial asset owners, OEMs, and investors.
Flaw Detectors Market
Market trajectory at a glance
Our market model shows the global flaw detectors market expanding from USD 780.98 Million in 2020 to USD 1,045.13 Million in 2025 (base year), and continuing to grow to an estimated USD 1,571.50 Million by 2032. This represents a compound annual growth rate (CAGR) of approximately 6.0% across the 2026–2032 forecast window. The pace of growth is underpinned by rising inspection frequencies in safety-critical sectors, accelerating adoption of higher-resolution ultrasonic modalities, and steady modernization of legacy inspection fleets.
Flaw Detectors Market
Why this matters for 2026 decision-making
- Procurement timing and capex planning: A predictable mid-single-digit CAGR creates a window to optimize capital deployment. Procurement teams can stagger fleet upgrades to capture incremental improvements in phased-array and matrix-capture systems without chasing premature obsolescence.
- M&A and partnership scouting: Market concentration metrics indicate a moderately consolidated landscape; the top tier of vendors control a meaningful share of revenue, but room exists for niche entrants and bolt-on acquisitions that add specialized capabilities (e.g., ultra-portable eddy current instruments, advanced PAUT modules).
- Technology roadmap alignment: The shift toward higher-resolution imaging and faster inspection workflows favors firms that can integrate digital data pipelines, cloud-enabled analytics, and robust instrument-to-asset traceability. Buyers should prioritize interoperability and software upgrade pathways when evaluating vendors.
- Supply-chain risk management: Critical components, notably piezoelectric transducers, remain sensitive to specialized ceramic and rare-earth supply dynamics — a factor that should be integrated into supplier diversification and contract terms for 2026.
What the PW Consulting report delivers (practical, actionable modules)
- Validated market sizing and forward scenarios: Deliverables include base-case, upside, and downside scenarios for 2026–2032 to stress-test capital plans under different macro and supply-chain outcomes.
- Vendor diagnostic matrix: Comparative, use-case driven assessments of leading suppliers across technology, service footprint, software ecosystems, and aftermarket economics — designed for sourcing committees and corporate development teams.
- Technology adoption playbook: Step-by-step migration pathways from legacy single-channel instruments to phased-array and full-matrix capture systems, including cost/benefit break-evens, staff training implications, and recommended pilot program designs.
- Procurement templates and KPI set: Bill-of-objects for fleet refresh, TCO modelling templates in USD (Million), and a compact KPI set to monitor inspection throughput, false-call rates, and asset uptime post-deployment.
- Regulatory and compliance checklist: A tailored compliance pack for aerospace, oil & gas, and power-generation stakeholders highlighting inspection cadences, traceability requirements, and audit readiness measures.
- Investment screening dashboard: Red-amber-green indicators for potential targets, focusing on technology defensibility, service revenue stickiness, and margin resilience in an evolving market.
Competitive landscape — what leaders and challengers are doing
The competitive map reflects a mix of established instrument manufacturers and agile specialist vendors. Strategic behaviors we observe include consolidation through corporate parents, focused product innovation around portability and imaging fidelity, and an intensifying aftermarket services play.
Flaw Detectors Market
- Evident (formerly Olympus IMS) — Tokyo / US operations: Evident remains a standard-bearer for rugged, field-proven ultrasonic detection with broad product lines such as the EPOCH series and OmniScan phased array systems. Their strength lies in deep OEM relationships and cross-sector product breadth which supports large-scale enterprise deployments and multinational service contracts. Evidence of continued investment in phased-array platforms positions them as a primary supplier for complex weld and aerospace inspections. ( https://www.evidentscientific.com)
- Waygate Technologies (Baker Hughes) — Hürth, Germany: Waygate’s Krautkrämer portfolio is notable for integrated automated and portable UT solutions used across oil & gas and power segments. Backed by Baker Hughes’ industrial reach, Waygate can scale bundled hardware-plus-services propositions to utility and upstream operator customers, an increasingly attractive model for buyers seeking to outsource inspection programs. ( https://www.bakerhughes.com/waygate-technologies)
- Sonatest Ltd — Milton Keynes, UK: Sonatest has sustained a focused reputation in phased-array instrumentation for aerospace and industrial markets. Their market positioning emphasizes user-centric interfaces and reliability, traits that accelerate acceptance among inspection teams under tight regulatory regimes. ( https://www.sonatest.com)
- Zetec (Eddyfi Technologies) — Issaquah, USA: Zetec’s combined ultrasonic and eddy current offerings target critical infrastructure applications with a balanced portfolio of portable and array-based systems. Their edge is in integrating inspection hardware with sophisticated signal processing for power and pipeline inspection programs. ( https://www.zetec.com)
- ETher NDE — St. Albans, UK: As a nimble innovator, ETher NDE recently launched an ultra-portable eddy current unit optimized for speed and accessibility, signaling the continued market pull for pocketable, high-performance detectors in aerospace and weld inspection niches. ( https://ethernde.com)
- Danatronics, Dakota Ultrasonics, OKOndt, NDT-KITS: These companies illustrate the competitive mid-tier where focus on portability, field usability, and cost-efficient servicing can win contracts against larger incumbents. Recent product introductions show innovation at the instrument form-factor and user-experience level.
Recent product activity underscores an innovation cadence concentrated on portability and usability: ETher NDE’s ultra-portable launch (Dec 2025), Danatronics’ Echo Pro portable ultrasonic release (Jan 2025), and new digital instruments showcased at trade shows (e.g., NDT 2025). Buyers should monitor product release timelines closely, as incremental improvements in battery life, user interfaces, and embedded analytics materially affect fleet refresh decisions.
Segment dynamics, supply-side risks, and regulatory drivers
- Raw material sensitivity: Piezoelectric sensors and transducers — the heart of most ultrasonic detectors — rely on specialized ceramics with exposure to rare-earth and specialty-ceramic supply constraints. Procurement strategies should incorporate multi-sourcing and contractual protections against single-supplier outages.
- Regulatory intensity: Tightening safety standards in aerospace, oil & gas, and power-generation will continue to mandate frequent and high-resolution inspections, elevating demand for advanced ultrasonic and eddy current technologies. This regulatory environment reduces market downside risk but raises the bar for compliance-ready instrument features (traceability, data retention, calibration records).
- Technology substitution and upgrade cycles: Phased-array and full-matrix capture modalities are increasingly preferred where imaging fidelity and inspection throughput matter. Organizations that delay migration risk higher long-term operating costs and increased false-call rates; conversely, premature upgrades without workforce readiness can erode ROI.
Strategic playbook for 2026
- Adopt a stage-gated upgrade approach: Start with targeted pilots (critical assets, high-failure modes) to validate new modalities and data workflows before enterprise rollout. Use pilot outcomes to negotiate favorable multi-year maintenance and upgrade clauses with vendors.
- Insist on open data standards: Prioritize instruments with exportable, standardized data formats to enable analytics portability and future AI integration — a key guardrail against vendor lock-in.
- Lock supply options for transducers: For capital programs slated in 2026–2028, secure component options or dual-source agreements for piezoelectric elements to mitigate lead-time and price volatility risk.
- Reassess aftermarket spending: Convert service relationships into value levers by insisting on outcome-based KPIs (inspection throughput, reduced rework) and by evaluating in-house vs. outsourced inspection economics in total cost of ownership terms.
- Use M&A to fill gaps: For strategic buyers, pursue bolt-on acquisitions that bring specialized inspection capabilities (e.g., ultra-portable eddy current, advanced PAUT modules) or strengthen service geographic reach in priority markets.
How to use the full report
PW Consulting’s full Flaw Detectors Market report contains detailed line-item forecasts, vendor profiles, an interactive decision toolkit, and downloadable procurement templates. In line with our “trailer” approach, this briefing highlights the strategic signposts and operational levers; the complete dataset and segmented breakouts — indispensable for tactical procurement and M&A diligence — are available in the full report.
For procurement leaders, operators, and investors preparing decisions in 2026, the report provides a pragmatic bridge from market theory to executable plans: scenario-tested forecasts, vendor selection criteria, and a technology migration playbook calibrated to regulatory realities and supply-chain constraints.
Next steps
- Download the full report to access the segmented forecasts, regional and application breakdowns, and our proprietary vendor scoring tool.
- Schedule a briefing with PW Consulting to run a customized supplier short-list workshop aligned to your asset base and inspection strategy.
Contact PW Consulting for enterprise access and bespoke advisory engagements that translate the Flaw Detectors Market intelligence into competitive advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Flaw Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


