



PW Consulting: Coal-to-Liquids (CTL) Market valued at USD 7.25 billion in 2025 to expand at a 3.92% CAGR during 2026–2032

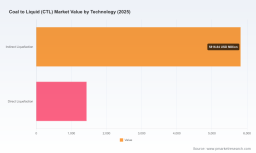
PW Consulting Strategic Preview: Coal-to-Liquids (CTL) Market — Actionable Intelligence for 2026 Decision-Makers
As governments and industrial stakeholders reassess energy security, feedstock strategy, and decarbonization pathways, the coal-to-liquids (CTL) sector is re-emerging as a strategic pivot point for upstream resource owners, midstream integrators, and downstream fuel and chemical buyers. PW Consulting’s latest market study — anchored on a 2025 base year and projecting from 2026 through 2032 — synthesizes market-sizing, technology economics, regulatory scenarios, and granular commercial diagnostics to inform high-stakes strategic choices in 2026.
Coal To Liquid Ctl Market
Why this report matters for 2026
-
Timing: Project sanctioning, construction starts and first-of-a-kind plant ramps that initiated in the 2024–2026 window will determine medium-term supply dynamics. Our analysis captures these inflection points and translates them into near-term risks and opportunities for project developers and investors.
Coal To Liquid Ctl Market -
Policy sensitivity: Emerging carbon pricing floors, CCS incentives and petrochemical demand pathways mean that a handful of policy inputs can swing project economics materially. The report quantifies these sensitivities in actionable scenarios so executives can stress-test investment and offtake assumptions.
Coal To Liquid Ctl Market -
Strategic positioning: For companies evaluating M&A, joint ventures, technology licensing or long-term offtake contracts, the report provides decision heuristics and a prioritized short-list of strategic moves calibrated to a range of near-term market outcomes.
Market trajectory — the macro picture (what we reveal)
On the macro axis, the global CTL market recorded steady expansion through the early 2020s and, as of our 2025 base year, stands at approximately USD 7,250 million (revenue unit: USD Million). Our forecast period (2026–2032) assumes an aggregate compound annual growth rate (CAGR) of 3.92%, reflecting a mix of continued capacity additions, targeted efficiency gains in synthesis routes, and selective market-pull from regions focused on energy security and chemical feedstock self-sufficiency.
By 2026 we project continued year‑on‑year growth from the 2025 baseline, driven by project ramp-ups and a wave of incremental investments in both indirect and direct liquefaction technologies and associated downstream integration. Through 2032 the market trajectory shows moderate expansion with occasional step-changes tied to the commissioning of large integrated projects and the commercial adoption of CTL-CCS configurations that capture and store emissions, enabling broader market access under tightening carbon regimes.
Key dynamics shaping 2026 decisions
-
Technology split and maturity: Both indirect (gasification + Fischer–Tropsch) and direct liquefaction routes remain commercially relevant. Technology selection increasingly hinges on feedstock logistics, integration with existing refining/chemical assets, and the potential to co-produce high-value chemical intermediates alongside fuels.
-
Carbon management becomes a financial lever: Carbon price dynamics and the availability of CCS materially alter project returns. Academic and industry analyses indicate carbon-price thresholds at which CTL-CCS transitions from a compliance cost to a value-accretive feature for projects; decision-makers should model these thresholds explicitly when sizing investment envelopes and negotiating offtakes.
-
Policy and local content: State-led project promotion, access to low-cost coal reserves, and sovereign backing for large-scale builds create asymmetric advantages for some national champions. In several jurisdictions, policy muscle continues to speed approvals and capital allocation to CTL projects.
-
Vertical integration and feedstock security: Control over coal supply chains, gasification technology licensing, and downstream offtakes has emerged as a reliable moat. Firms that can pair feedstock access with downstream markets minimize merchant exposure and raise the chances of bankable project economics.
Competitive landscape — what we highlight (and why)
The CTL market displays a concentrated competitive structure: the three largest market participants collectively account for a dominant share of commercial output, and the top five firms control an even larger portion of supply. This concentration underscores several strategic realities: incumbents retain preferential access to feedstock and project finance; scale affords optimization opportunities across gasification and synthesis trains; and market entry for new players requires differentiated economics, technology partnerships, or niche downstream integration.
Our competitive analysis profiles the primary global and regional players — covering long-established commercial operators, national energy groups leading large integrated projects, and technology providers that supply critical Fischer–Tropsch and gasification intellectual property. For each player we assess strategic posture across five dimensions: asset footprint and scale; technology stack and R&D posture; upstream feedstock control; downstream integration and offtake flexibility; and carbon management strategies including CCS readiness.
Notable strategic behaviors we observed include: operational optimization at legacy facilities to extend margins; large-scale new-builds driven by energy-security mandates; and selective alliances between technology licensors and resource owners to reduce time-to-market for new projects.
Report contents — practical outputs you can use
-
Market sizing and baseline calibration: audited historical series (2020–2025) and multiple forecast pathways for 2026–2032, with scenario toggles for policy and commodity inputs.
-
Techno-economic models: modular, spreadsheet-based models for both direct and indirect pathways that allow clients to tailor feedstock, CAPEX/OPEX, and carbon assumptions.
-
Project-level risk scoring: a reproducible framework covering construction, commissioning, offtake, regulatory and ESG risks — designed for use in investment committees and credit assessment.
-
Carbon and CCS playbook: cost curves and break-even carbon-price analyses that identify where CCS is value-accretive, and recommended commercial structures to capture incremental value (e.g., carbon offtake, bundling with hydrogen hubs).
-
Competitive benchmarking: qualitative and quantitative diagnostics for incumbent and challenger companies, covering technology licensing, vertical integration and market positioning.
-
Go-to-market and M&A signals: prioritized target lists, divestment indicators and suggested term-sheets for offtake-linked financing.
Strategic recommendations for 2026 decision windows
-
Run parallel scenario planning with carbon floors: Model projects under a range of carbon-pricing regimes — including conservative floors and accelerated pricing pathways — to identify the point(s) at which CCS upgrades should move from contingent to committed capital.
-
Pursue staged commitments and modularity: Favor phased capex commitments and modular process units that allow scale-up once first-mover risks are resolved, thereby preserving optionality and protecting balance sheets.
-
Lock feedstock and offtake exposure: Negotiate integrated coal supply and blended-offtake contracts to stabilise margin volatility. For buyers, consider long-term purchase agreements with embedded decarbonization clauses.
-
Form technology and financing consortia: Combine technology licensors, EPC partners and development finance in blended structures to de-risk execution and spread political/regulatory exposure, especially in markets with active state participation.
-
Embed CCS from early FEED studies: Given the sensitivity of CTL economics to carbon costs, early-stage CCS integration reduces retrofit risk and improves the investability of projects under tightening emissions regimes.
-
Monitor policy triggers and prepare fast-response playbooks: Maintain decision triggers anchored to policy milestones (e.g., announced carbon floors, CCS incentives, or local content mandates) so teams can execute opportunistically.
How PW Consulting’s analysis supports 2026 execution
The value proposition of our study is practical: we convert industry-scale dynamics into executable tasks for boards, investors and business-unit leaders. Rather than presenting a single deterministic outlook, the report provides the analytical scaffolding to make high-confidence binary choices in 2026 — whether that is to accelerate an FID, renegotiate an offtake, pursue a joint-venture, or step back and preserve optionality.
We intentionally designed our deliverables to be action-ready: interactive model files, an executive dashboard highlighting decision triggers, and a stand-alone policy sensitivity map that links headline regulatory moves to P&L and project NPV outcomes.
Invitation to get the full intelligence
This article provides a strategic preview of the insights and practical tools contained in PW Consulting’s full Coal-to-Liquids (CTL) Market Report (base year 2025; forecast 2026–2032). For procurement teams, corporate strategists, project developers and investors preparing for 2026, the full report contains the detailed segment analyses, project-level diagnostics and downloadable modelling assets that we deliberately summarize here to preserve the need-to-know integrity of proprietary project datasets.
Contact PW Consulting to obtain the complete report, the executable financial models, and a bespoke advisory session to translate findings into a 90‑day action plan tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Coal To Liquid Ctl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


