



PW Consulting: Water Treatment Equipment in Power Market to Reach USD 7,784.16 Million by 2032 at a 5.8% CAGR, Led by Asia‑Pacific’s USD 2,121.99M Share

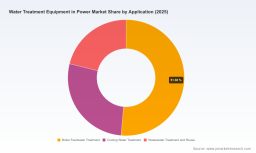
Water Treatment Equipment in Power Market — Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s new market study, Water Treatment Equipment in Power Market (base year 2025), provides a strategic blueprint for corporate leadership, investors, and policy teams preparing capital and operational decisions in 2026. The global market for water treatment equipment serving power generation is valued at USD 5,245.8 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.8% through the 2026–2032 forecast window, reaching approximately USD 7,784.2 Million by 2032. This trajectory reflects a confluence of regulatory pressure, water-stress mitigation, and technology adoption that will reshape procurement, O&M, and capital project priorities over the next three years.
Water Treatment Equipment In Power Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a pivotal year for clients updating five-year capex plans and contract portfolios. Early adopters of resilient water-treatment strategies can capture efficiency upside while avoiding asset-level regulatory and operational risk.
Water Treatment Equipment In Power Market -
Risk calibration: The market’s steady growth masks sharper micro-dynamics — supply-chain concentration for critical consumables, accelerating water-quality regulation, and localized water scarcity events. Our study translates these into investment-grade implications for plant operators and suppliers.
Water Treatment Equipment In Power Market -
Supplier selection and contracting: With market concentration indicators showing a moderately consolidated supplier base, strategic procurement that blends global OEM capability with regional service partners will be essential to control lifecycle costs and ensure uptime.
Market trajectory and drivers
The market’s upward path is being sustained by three structural forces. First, regulatory regimes — particularly tightening contaminant limits and emerging PFAS controls — are increasing demand for granular activated carbon (GAC) services, reactivation capacity, and higher-fidelity treatment trains. Second, operational imperatives in power plants (scale and corrosion control, steam purity) continue to push utilities toward integrated, higher-purity solutions to protect high-value rotating equipment and boilers. Third, water-stressed basins and sustainability commitments are driving adoption of reuse and zero-liquid-discharge (ZLD) architectures in both new-build and retrofit applications.
These drivers interact with market microstructure: critical raw materials such as ion exchange resins and activated carbon are strategic inputs, and their availability and reactivation capacity directly affect lead times and lifecycle economics for treatment systems. Recent industrial moves to expand carbon reactivation capacity and to launch nuclear-grade resins underline the materiality of these inputs to procurement strategies.
Practical content of the report — what leaders will get
Rather than theoretical overviews, the study delivers operationally actionable intelligence designed for corporate strategy and plant-level decision-making:
-
Scenario-based market sizing and demand drivers aligned to near-term regulatory milestones and water stress indices.
-
CapEx and OpEx modelling templates tailored to common power-plant configurations (thermal, combined-cycle, and nuclear), supporting rapid sensitivity testing of technologies such as membrane systems, ion exchange, and ZLD modules.
-
Procurement playbooks that recommend contracting structures, life-cycle pricing levers, and service-bundle trade-offs to mitigate supply-chain and regulatory risk.
-
Technical decision matrices comparing treatment architectures by KPIs that matter to power operators: purity, footprint, energy intensity, chemical consumption, sludge generation, and maintenance cadence.
-
Localized implementation roadmaps to support retrofit sequencing that minimizes outage risk and maximizes return on incremental investments.
Competitive landscape — what to watch in supplier strategies
The Water Treatment Equipment in Power Market is served by a mix of global engineering houses, specialized membrane and media providers, and regional integrators. Market concentration metrics indicate a landscape where a small set of large players exert influence over standards, while numerous niche providers compete on specialty media, mobile solutions, and project delivery flexibility.
Key supplier profiles summarized in the study highlight strategic differentiation points:
-
Global engineering and systems providers are leveraging integrated portfolios (membranes, electrodeionization, condensate polishing) to sell lifecycle outcomes rather than discrete equipment.
-
Equipment and media specialists differentiate through product innovation (nuclear- and high-purity grades, advanced activated carbons) and targeted aftermarket services, including rental and mobile units for temporary capacity needs.
-
Digital and monitoring-enabled vendors are pushing service-based models that convert traditional O&M spend into performance contracts tied to water-use efficiency and asset availability.
The report profiles incumbent and growth-focused companies active in power-focused water treatment, analyzing strengths that include engineered systems delivery, digital monitoring capabilities, chemical and media integration, and specialty product lines for high-purity applications. Corporate actions and recent developments signal where competition will intensify in 2026:
-
Product launches of nuclear-grade ion exchange resins and targeted orders to power customers—illustrating demand for higher-specification media tailored to boiler feed and condensate polishing.
-
Major investments in carbon reactivation capacity to address PFAS-driven demand for granular activated carbon in both municipal and industrial segments, which will reduce long-term media scarcity and influence pricing dynamics.
Regulation, raw materials, and operational risk
Regulatory tightening — notably PFAS rulemaking in key markets — is accelerating demand for robust GAC supply chains and in-plant reactivation or replacement strategies. For power operators, the immediate impacts are operational (frequent media changeouts, higher treatment complexity) and strategic (need to lock multi-year supply agreements or invest in on-site reactivation capacity).
Raw materials are not interchangeable in high-purity contexts. Ion exchange resins, specialty carbons, and membrane chemistries each have performance envelopes tied to specific boiler and condensate chemistries. Procurement that treats these inputs as strategic — with dual sourcing, qualification protocols, and total-cost-of-ownership modelling — will protect asset performance and reduce unexpected outage risk.
Technology adoption patterns and cost implications
Adoption is bifurcating. Large, high-reliability assets (including nuclear and baseload thermal plants) increasingly demand integrated, higher-capex systems that minimize long-term downtime and chemical consumption. Conversely, peaking and industrial plants favor modular and mobile solutions that offer rapid deployment and lower up-front commitment. Zero liquid discharge and high-recovery membrane trains are maturing as commercially viable retrofit options in water-constrained regions; however, energy and sludge-handling economics remain key gating factors.
M&A and partnership lenses for 2026
With moderate supplier concentration and continued demand growth, strategic M&A and alliance activity are likely in 2026. Buyers will prioritize targets that provide:
-
Proprietary media or membrane technology that shortens the path to higher-purity outcomes.
-
Service and digital platforms that convert equipment revenue into recurring, performance-linked income.
-
Regional footprint or reactivation capacity to address logistics and regulatory-driven media demand.
For corporate strategy teams, the report lays out an M&A scorecard that links target profiles to near-term synergies and longer-term integration risks, as well as alternative partnership models that preserve flexibility while securing critical inputs.
How to use the report in 2026 planning
-
Board-level investment deliberations: Use our scenario models to stress-test projected cashflows and outage probabilities under alternative regulatory timelines.
-
Procurement strategy: Adopt the report’s contracting templates to secure multi-year media supply and performance-based service agreements that cap lifecycle exposure.
-
Project pipeline prioritization: Apply our retrofit decision matrices to rank projects by ROI, implementation lead time, and regulatory urgency.
-
M&A and JV screening: Leverage the M&A scorecard to shortlist targets that deliver technical capability, regional access, or service innovation.
What we intentionally withhold — and why
This briefing demonstrates the report’s analytical depth while honoring the “trailer” principle. We present macro market sizing, CAGR, concentration metrics, and strategic implications to enable executive-level triage. Detailed breakdowns — including granular regional shares, application-level dollar splits, and company-specific revenue estimates by segment — are intentionally not disclosed here. These datasets, scenario workbooks, and executable procurement templates are available within the full report and associated data appendices.
Next steps
For strategy teams, investor groups, and procurement leaders preparing decisions in 2026, PW Consulting offers tailored briefings and data-access packages that unlock the report’s full diagnostic and modelling assets. Our advisory services can help align capex planning, supplier negotiation strategies, and M&A diligence to the market dynamics outlined above.
Contact PW Consulting to schedule a tailored executive briefing and gain access to the full Water Treatment Equipment in Power Market report, underlying datasets, and scenario toolkits designed to convert insight into defensible action.
For detailed analysis of this topic, please visit the official page: Water Treatment Equipment In Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


