



PW Consulting: IT Spending on Clinical Analytics to Expand at 13.45% CAGR, Market Reaches USD 22,500 Million in Base Year 2025

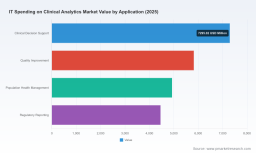
It Spending On Clinical Analytics Market — 2026 Strategic Preview from PW Consulting
Executive summary
PW Consulting’s new market study on IT Spending on Clinical Analytics Market (base year 2025) frames 2026 as a decisive year for health systems, payers, life-sciences firms and technology vendors. Our analysis projects sustained double‑digit expansion driven by AI-enabled clinical use cases, cloud maturation, and growing pressure on outcomes and cost containment. The market expanded to an estimated USD 22,500 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 13.45% through our 2026–2032 forecast horizon — a trajectory that doubles down on analytics as a strategic, rather than purely operational, investment.
It Spending On Clinical Analytics Market
Why this matters for enterprise decision-makers in 2026
- Budget prioritization: When IT and clinical leaders allocate capital in 2026, analytics investments will compete directly with platform modernization, AI infrastructure and regulatory compliance. Our report quantifies the overall market scale and growth velocity to help CFOs and CIOs benchmark spending ambition and justify multi‑year investment plans.
- Vendor strategy: The market exhibits moderate concentration (top‑three share ~28.4%; top‑five ~36.2%), implying a healthy mix of incumbents and specialized challengers. That structure creates opportunities for strategic partnerships, targeted procurement, and selective M&A — but it also requires careful vendor risk assessment.
- Regulatory and infrastructure cost exposure: New energy and data‑center regulations, plus DOJ restrictions on bulk health‑data transfers, materially affect sourcing and cloud‑hybrid decisions. We translate these dynamics into practical sourcing constraints and scenario stress tests.
Key market signals — headline metrics
PW Consulting’s headline findings offer a compact, decision‑ready view: the market reached USD 22.5 billion (2025, USD Million base) and is forecast to grow at a 13.45% CAGR across the 2026–2032 period. By 2032, our model anticipates a substantial market expansion reflecting the cumulative effect of AI platform adoption, expanded analytics services and growing demand for integrated clinical workflows. These macro figures are designed to anchor portfolio planning, vendor engagement and M&A sizing exercises.
It Spending On Clinical Analytics Market
What the report contains — practical, actionable modules
Our report is organized for immediate use by strategy, procurement and clinical leadership teams. It includes:
It Spending On Clinical Analytics Market
- Market sizing and demand drivers: a transparent, reproducible model that ties spending to provider, payer and life‑science adoption curves.
- Adoption scenarios and financial impact models: three forward scenarios (base, accelerated, constrained) that translate technology adoption into operational KPIs such as avoidable admissions, readmission reduction and cost per case improvements.
- Vendor and capability mapping: a practice‑oriented taxonomy that aligns vendor capabilities to buyer use cases (e.g., clinical decision support, population management, quality programs) while preserving our proprietary segment-level intelligence behind a gated analysis.
- Procurement playbooks and contract guardrails: negotiation templates and service-level checklists for cloud, managed‑service and software purchases, emphasizing data residency, model governance and energy‑cost pass‑through clauses.
- Regulatory, energy and data governance playbooks: scenario planning templates that quantify potential carrying costs associated with evolving state‑level data‑center rules and DOJ data‑transfer limitations.
- M&A and partnership scorecards: diligence frameworks and synergy valuation approaches tailored for acquirers and target companies in clinical analytics and adjacent segments (imaging, EHR, RWE).
Competitive landscape — what to watch in 2026
The clinical analytics ecosystem is a blend of large platform incumbents, specialist analytics firms, and adjacent diagnostic and device players. We profile leaders across these archetypes and evaluate strategic positioning, strength corridors, and risk exposures:
- Optum Inc. (UnitedHealth Group): Leverages deep claims and clinical data assets to monetize population‑level analytics and risk‑stratification capabilities. Strengths include scale of data, payer‑provider integration and end‑to‑end managed services; watch for integration and regulatory scrutiny as these platforms expand.
- Oracle Health (formerly Cerner): Emphasizes integrated EHR + analytics offerings and recent platform expansion moves. Their playbook targets hospital efficiency and clinician decision support; integration cadence and cloud migration economics are key adoption triggers.
- Epic Systems Corporation: Continues to embed analytics within enterprise EHR workflows, offering tight clinician integration and real‑world evidence capabilities. Epic’s installed base creates natural retention, but interoperability and third‑party analytics partnerships will define its competitive edges.
- IQVIA: Positioned at the intersection of life sciences and clinical data, IQVIA drives RWE and outcomes research; expect increasing collaboration between life sciences analytics and provider decision support.
- SAS Institute Inc. and Health Catalyst: Both offer strong analytics platforms — SAS with advanced statistical modeling and Health Catalyst with integrated clinical/financial datasets aimed at quality improvement and cost reduction.
- GE HealthCare and Siemens Healthineers: Diagnostic and imaging vendors are doubling down on analytics to link imaging and monitoring data into clinical workflows, a powerful vector for enterprise clinical insight monetization.
- Merative, Koninklijke Philips, Veradigm and McKesson: Each brings differentiated strengths — data consolidation, connected care, ambulatory analytics, and supply‑chain analytics respectively. Their strategies reflect horizontal integration and vertical market plays.
Across vendor types, our analysis highlights three tactical themes for buyers: (1) demand for composable analytics that fit existing EHR ecosystems; (2) growing importance of managed services for AI model ops; and (3) the emergence of outcome‑linked commercial models.
Dynamics, risks and externalities shaping 2026 decisions
Several non‑functional dynamics are reshaping how analytics spending converts to outcomes:
- Data center and AI infrastructure costs: Independent analysis shows substantial hidden external costs associated with data centers supporting AI and analytics workloads. These costs are increasingly internalized via energy surcharges and grid‑impact tariffs in state regulation, altering TCO for cloud versus on‑prem choices.
- State‑level data‑center regulation: A wave of U.S. state actions in 2025–2026 is shifting the burden of new energy and transmission infrastructure to large data center operators. Organizations relying on public cloud providers should re‑evaluate contract clauses and geographic resilience assumptions.
- DOJ restrictions on bulk health data transfers: New rules limiting bulk transfers of sensitive health data to certain jurisdictions materially influence cross‑border analytics collaborations and vendor selection for multinational projects.
- Macro AI infrastructure investment: With broad industry estimates putting AI infrastructure spending in the hundreds of billions in 2026, competing priorities around talent, GPU capacity, and sustainability objectives will shape execution timelines for advanced clinical models.
Strategic recommendations for 2026 — three priorities
- Adopt a quadrant funding approach: Allocate investments across foundational data ops, clinical use‑case pilots, scalable platform subscriptions and regulatory/compliance contingencies. Use our scenario models to size staged investments tied to measurable clinical KPIs.
- Design contracts for volatility: Insist on energy‑cost pass‑through protections, data residency guarantees and clear model governance obligations. Where possible, build outcome‑based clauses to align vendor incentives with clinical and financial goals.
- Pursue modular vendor architectures: Favor composable, API‑driven analytics stacks that permit swapping of components (e.g., model providers, MLOps, visualization) without wholesale rip‑and‑replace, reducing strategic lock‑in and improving negotiation leverage.
How to use this report in boardrooms and strategy sessions
PW Consulting’s market report is designed for immediate translation into governance and investment artifacts. Typical uses include:
- Capital allocation templates for the CFO office that reconcile analytics spend to expected quality and margin improvements;
- Procurement scorecards that incorporate vendor risk on data residency, energy cost exposure and model validation;
- M&A diligence checklists to size revenue synergies and integration risk vis‑à‑vis clinical workflow adoption;
- Regulatory scenario decks for compliance teams that map new state and federal legislative actions into sourcing outcomes.
Conclusion — the strategic value of the report in 2026
For leaders making allocation and sourcing decisions in 2026, understanding the macro scale and growth trajectory of clinical analytics spending is table stakes. PW Consulting’s study provides that top‑line perspective — alongside pragmatic modules for procurement, governance and scenario planning — while carefully preserving segment‑level intelligence to be accessed via the full report. In an environment of accelerating AI investments, tightening regulatory constraints and shifting energy economics, this study is intended to be the neutral, evidence‑based input for executives deciding not just what to buy, but how to build sustainable, auditable and outcome‑oriented analytics capability.
Get the full analysis
This press overview highlights our methodological approach, headline market sizing and the strategic lenses we apply. Detailed segment breakdowns, vendor scorecards, and downloadable modeling workbooks are available in the full PW Consulting report. Contact our research team or visit the report page to obtain the complete dataset and bespoke advisory engagement options.
For detailed analysis of this topic, please visit the official page: It Spending On Clinical Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


