



PW Consulting: Satellite Manufacturing and Launch Systems Market to Expand at an 8.26% CAGR, Accelerating Growth Through 2032

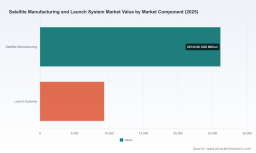
Satellite Manufacturing and Launch System Market: Strategic Imperatives for 2026
As governments and commercial actors accelerate space deployment, executives face a narrowing window to translate strategic intent into durable advantage. PW Consulting’s new Satellite Manufacturing And Launch System Market report — built on a comprehensive 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes market dynamics, competitive vectors, regulatory headwinds, and operational playbooks that will determine winner and follower outcomes in 2026. The market we model stands at USD 35,450 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 8.26% through 2032, reaching a materially larger opportunity by the end of the forecast period. This briefing summarizes the report’s strategic value for 2026 decision-making while preserving the deeper segmentation intelligence available in the full study.
Satellite Manufacturing And Launch System Market
Market Snapshot: Why 2026 Is a Pivotal Inflection Year
-
Momentum and scale: After a sustained expansion through 2020–2025, the satellite manufacturing and launch ecosystem is entering a phase where scale economics intersect with operational cadence. The base-year market size (2025) and the 8.26% CAGR underpin scenarios where mid-decision horizons (2026–2028) determine capacity utilization and competitive positioning through 2032.
Satellite Manufacturing And Launch System Market -
Concentration and competitive tensions: The market exhibits a moderate concentration profile; the top three and top five players account for a meaningful share of industry revenue, creating a landscape where incumbent advantages in manufacturing scale and launch manifest but do not preclude disruptive entrants.
Satellite Manufacturing And Launch System Market -
Capex rhythm vs. demand cadence: Capital-intensive launch programs are reaching a synchronization point with satellite constellation rollouts. Organizations that resolve the timing mismatch between factory throughput, launch manifest, and regulatory approvals in 2026 will capture asymmetric returns later in the cycle.
Five Strategic Themes Shaping 2026 Decisions
-
1) Vertical integration vs. modular specialization: The industry is polarizing between actors who pursue end-to-end control (manufacture + launch integration) and those who optimize specialized stacks (smallsat buses, payloads, or launch services). Each choice carries trade-offs in margin, capital needs, and export/regulatory exposure. Our report provides decision heuristics to evaluate capex allocation against time-to-market and risk appetite.
-
2) Supply chain resilience and critical materials: Shortages and export controls affecting high-purity gallium and germanium, together with concentrated sources for advanced detectors and solar cells, create strategic supply-risk corridors. In 2026, firms must choose between near-term component hedging, verticalizing key suppliers, or redesigning architectures to reduce dependency on constrained inputs.
-
3) Regulatory and orbital governance as a commercial factor: Recent spectrum rule updates and strengthened debris mitigation requirements mean compliance is now a design constraint, not an afterthought. Teams should embed regulatory gating in product roadmaps and partner diligence to avoid launch delays and market access friction.
-
4) Manufacturing scale and facilities: Cleanroom capacity and specialized assembly infrastructure remain limited globally. Investing in scalable iso-grade cleanrooms or securing long-term capacity slots creates a competitive moat for producers targeting high-frequency constellation deployments.
-
5) Launch cadence and insurance dynamics: A clarified launch manifest and reliable frequent-launch providers reduce program risk and insurance premiums. Strategic contracting for launch capacity — including mixed portfolios of rideshares and dedicated heavy-lift services — will be a differentiator in 2026.
What the Report Delivers to Executives
-
Rigorous market sizing and scenario models calibrated to 2025 base-year performance and stress-tested across demand, regulatory, and materials scenarios for 2026–2032.
-
Competitive intelligence and vendor scorecards that benchmark technology readiness, manufacturing throughput, launch reliability, and export-control exposure — presented as decision-ready matrices rather than raw vendor rankings.
-
Supply chain risk maps that identify single-source dependencies, substitution pathways, and regional chokepoints for critical components and cleanroom capacity.
-
Go-to-market playbooks for constellation operators, government contractors, and emerging national players — including contracting templates for launch slots, tech-transfer checklists, and partner selection criteria.
-
M&A and partnership screens that identify tactical targets (manufacturing IP, niche payload specialists, launch-integration service providers) and financial models for integration planning.
-
Operational dashboards and KPIs for 2026 execution: throughput per cleanroom, launch manifest hit rate, supplier lead-time variance, and regulatory compliance milestones.
Competitive Landscape: Positioning and Strategic Moves
The competitive map combines legacy aerospace primes, launch specialists, and vertically integrated newcomers. Key archetypes and implications:
-
High-volume integrators (example archetype: SpaceX): Achieve accelerated learning curves through repeated production and launch cycles. Their playbook focuses on reducing per-satellite costs, internalizing launch risk, and controlling fleet economics. For established competitors, the defensive options include targeting differentiated payload offerings, securing exclusive launch windows, or pursuing partnership models.
-
Legacy primes (example archetypes: Boeing, Lockheed Martin, Northrop Grumman): Leverage deep relationships in government and defense, proven system integration capabilities, and GEO/MEO heritage. Their near-term challenge is adapting production organizational models to the cadence and cost expectations of commercial constellations without eroding margins.
-
European system houses (example archetypes: Airbus Defence and Space, Thales Alenia Space): Compete on engineered, high-reliability products and institutional customers. They can win by coupling platform advances with assured access to launch frameworks and by capturing a share of government modernization budgets.
-
Small-sat and launch specialists (example archetypes: Rocket Lab, Blue Origin, Rocket Lab’s Photon offerings): Target rapid, lower-cost deployment niches and in-orbit manufacturing/servicing experiments. Their strategic advantage is agility; partnerships with OEMs for standardized bus designs expand their TAM.
-
National and sovereign players (example archetypes: ISRO, CASC): Provide alternative access to launch and manufacturing capacity, often with different commercial constraints and price points. For multinational suppliers, understanding export-control and local content implications is critical.
Recent operational and corporate developments underscore these dynamics — from high-frequency launches of new-generation constellation satellites to funding injections accelerating heavy-lift readiness. These events recalibrate launch supply assumptions and partnership opportunities entering 2026.
Actionable Roadmap for 2026 (Prioritized Moves)
-
1) Run three 18-month scenarios (base, optimistic, stress) that explicitly model launch cadence slippage, key material embargoes, and spectrum/regulatory delays. Convert scenarios into capital-allocation triggers.
-
2) Secure conditional capacity: Execute option agreements for cleanroom time and launch slots to protect go-to-market timelines while avoiding full upfront capex where possible.
-
3) Deploy supply-chain playbooks: Initiate dual-sourcing or design-for-substitution projects targeting components at material risk. Where substitution is infeasible, explore strategic inventory or JV manufacturing to lock supply.
-
4) Integrate regulatory and orbital-sustainability disciplines into product development: mandate passivation and deorbiting designs, embed spectrum mitigation planning, and map export-license timelines into delivery milestones.
-
5) Pursue targeted partnerships and bolt-on M&A that accelerate capability rather than diversify away from core advantages — for example, payload specialists, in-orbit-servicing technology, or launch-integration firms.
How PW Consulting’s Report Enables Execution in 2026
The study is engineered to be operational: each strategic insight is paired with a toolkit — templates, KPIs, supplier due-diligence checklists, and financial models — that can be adopted by product, supply-chain, and corporate-development teams. For executives preparing 2026 budgets and board-level strategy reviews, the report converts ambiguous space-industry dynamics into prioritized initiatives, measurable milestones, and acceptable-risk levers.
PW Consulting’s approach blends quantitative modeling with qualitative expert interviews and proprietary scenario stress-testing. We protect value by presenting high-confidence topline sizing (2025 base and 2026–2032 growth trajectory) while reserving granular subsegment breakouts and supplier-level intelligence for the full report — a deliberate design to ensure readers contact the source for transaction-grade insights.
Next Steps
Leaders who want to translate these strategic themes into action plans for 2026 should engage with our report to obtain the executable modules: the launch-capacity contracting playbook, supply-chain mitigation templates, and a prioritized M&A shortlist calibrated to your risk profile. Visit PW Consulting’s Satellite Manufacturing And Launch System Market page to download the executive summary and arrange a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Satellite Manufacturing And Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


