



PW Consulting: Digestive Enzyme Complex Market Poised for Robust Expansion with a 7.21% CAGR, New Insights Reveal

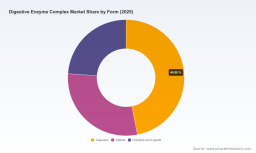
Digestive Enzyme Complex Market: Strategic Imperatives for 2026 — Pw Consulting Digest Release
Executive snapshot
As the global digestive enzyme complex market transitions from niche clinical applications into more diversified consumer- and practitioner-oriented channels, executives must calibrate strategy to a market that is growing steadily yet remains fragmented. Our new Pw Consulting Digest synthesizes a comprehensive model — built on a 2025 base year — that shows the market reached approximately USD 1.10 billion in 2025 and is expected to expand into the mid‑teens of percentage points annually over the next decade, with a compound annual growth rate of 7.21% across the 2026–2032 forecast window. By 2032 the market is projected to approach USD 1.8 billion, driven by converging forces in healthcare access, consumer wellness trends, and supply‑side adjustments in enzyme sourcing and manufacturing.
Digestive Enzyme Complex Market
Why 2026 is a decision inflection point
-
Post‑pandemic demand normalization and a maturing supplement landscape are creating pressure to differentiate. Pure price competition is no longer a durable route to growth; scientific provenance, supply chain transparency, and channel partnerships will decide winners.
Digestive Enzyme Complex Market -
Regulatory clarity around enzyme sources and manufacturing controls — particularly for pancreatic enzyme replacement therapies (PERT) and porcine‑derived inputs — is tightening in key markets. Firms that embed regulatory design into product development will avoid late‑stage compliance costs and launch delays.
Digestive Enzyme Complex Market -
Supply dynamics remain a strategic risk and an opportunity. A combination of government procurement actions and API capacity investments announced in 2025–2026 signal that security of raw material and API throughput will be a competitive lever for prescription and high‑touch practitioner channels.
What Pw Consulting’s Digest delivers to senior leaders
This release is not a high‑level overview. It is a practitioner’s playbook designed to be actionable in the boardroom and during investor due diligence. Highlights include:
-
A vetted market model calibrated to historical performance (2020–2025) and a detailed 2026–2032 forecast scenario set. The model is built to be scenario‑sensitive so you can stress‑test decisions under alternative demand, price and supply assumptions.
-
Commercial scorecards for suppliers, CMO partners and finished goods competitors that synthesize quality certifications, GMP footprint, clinical validation, and go‑to‑market reach.
-
A regulatory tracker with practical compliance milestones — including characterization and safety requirements — mapped to product classes (prescription PERT, over‑the‑counter digestive complexes, enzyme‑augmented probiotic formats) so teams can time development and filings.
-
Supply‑chain heat maps and mitigation playbooks addressing porcine sourcing, microbial production scale‑up, and plant‑based enzyme procurement strategies.
-
Go‑to‑market playbooks for three strategic archetypes: clinical/prescription leadership, practitioner‑channel specialists, and mass retail/online value brands — each with recommended R&D, manufacturing and commercial investment timing.
-
Deal flow and inorganic growth frameworks that prioritize targets by strategic fit (technology, capacity, channel) and illustrate likely valuation differentials driven by validated clinical data or secured API supply.
Competitive landscape — who matters and why
The sector remains moderately concentrated: a group of established pharmaceutical and ingredient specialists coexists alongside nimble supplements brands and purpose‑built enzyme manufacturers. Market leadership is not monopolized; the top players collectively capture less than half of the market, leaving ample room for mid‑market consolidation and niche innovation.
Key corporate archetypes and the strategic implications we draw in the report:
-
Large pharmaceutical incumbents (e.g., AbbVie/Creon franchise) — Command trust in prescription PERT and enjoy deep regulatory experience and channel access into gastroenterology practices. Their decisions on API capacity and contract manufacturing reverberate across the PERT supply chain. For non‑prescription entrants, competing on clinical parity demands significant investment or strategic partnerships.
-
Ingredient specialists and enzyme manufacturers (Amano, Bioseutica, National Enzyme/ADM/Deerland, Advanced Enzyme Technologies, DSM‑Firmenich) — These firms are gatekeepers for enzyme sourcing, technical know‑how, and scale. Their proprietary extraction or microbial fermentation platforms determine cost curves and product differentiation opportunities (e.g., lactose‑ or gluten‑targeted enzyme specialties).
-
Dedicated supplement brands and contract manufacturers (Enzymedica, Specialty Enzymes & Probiotics, Garden of Life, NOW Foods, Integrative Therapeutics, Metagenics, Pure Encapsulations) — These actors translate enzyme science into consumer propositions. Their strengths vary — some compete on clinical testing and practitioner trust, others on clean‑label and price accessibility. The most attractive partners for rapid market entry are those that combine formulation expertise with e‑commerce and practitioner network access.
-
Hybrid entrants and innovators — New product categories that combine enzymes with probiotics, targeted substrates, or personalized dosing are emerging. Recent launches and product expansions demonstrate demand for combined digestive‑microbiome propositions targeted at practitioners and premium e‑commerce channels.
Recent developments that reshape 2026 strategies
-
New product launches that pair enzymes with probiotics or targeted microbiome‑support ingredients are accelerating category overlap and widening adoption among clinical practitioners and online consumers.
-
Supply announcements and API capacity investments by major players are reducing single‑point failure risk in the medium term but may compress margins for manufacturers who cannot secure forward contracts or backward integration.
-
Regulatory guidance continues to emphasize source characterization and contaminant controls. For companies pursuing animal‑derived enzymes, documented traceability and third‑party certification are non‑negotiable for market access in developed markets.
Strategic recommendations for 2026 corporate planning
-
Secure supply now, optimize later: Evaluate multi‑sourcing and long‑term offtake agreements for API or enzyme concentrates. Consider tolling arrangements or minority stakes in critical suppliers to maintain optionality without full vertical integration.
-
Differentiate on provenance and evidence: Invest selectively in clinical or mechanism‑of‑action studies that match your go‑to‑market channel. Provider channels value clinical validation; retail consumers value clean‑label certification and sustainability claims backed by traceability.
-
Segment commercialization by channel archetype: For prescription/PERT, prioritize regulatory and supply investments. For practitioner channels, invest in medical education and distribution partnerships. For mass retail and e‑commerce, optimize cost of goods, packaging, and digital conversion funnels.
-
Pursue bolt‑on M&A with capability gaps in mind: Target small manufacturers with GMP credentials or ingredient innovators with proven cost advantages or novel microbial fermentation platforms to accelerate time‑to‑market.
-
Design for regulatory resilience: Implement source‑characterization workflows and third‑party testing regimes that reduce launch risk across jurisdictions; embed regulatory KPIs in R&D gates.
-
Monitor adjacent innovation: Enzyme‑microbiome combinations and enzyme delivery formats that improve stability or targeted release are potential disruptors. Keep an option value budget for licensing early‑stage innovations.
How the full Pw Consulting report supports execution
The Digest is a condensed, actionable briefing. The full Pw Consulting Digestive Enzyme Complex Market report provides the unlocks needed for execution: a downloadable financial model that allows management to run custom scenarios; supplier due‑diligence templates; a prioritized M&A target list with commercial and technical valuation drivers; and a regulatory playbook with jurisdictional checklists. We balance transparency with commercial discretion — the full segmentation tables, regional breakdowns, and proprietary company scoring are reserved for the complete report to maintain data integrity and client value.
Next steps for leaders
-
Schedule a single‑day strategy workshop with Pw Consulting to translate the forecast scenarios into a 12–24 month roadmap tailored to your business archetype.
-
Request the full report to obtain the model, supplier scorecards and our prioritized M&A shortlist. The report will enable your team to quantify tradeoffs between CAPEX for manufacturing capacity versus contractual resilience with third‑party suppliers.
-
Engage our regulatory team for a targeted gap assessment if you rely on animal‑derived enzymes or plan to enter markets with stringent characterization requirements.
Closing perspective
The digestive enzyme complex market presents a classic strategic paradox — clear growth but dispersed value. Success in 2026 will not be won by scale alone; it will be won by firms that marry technical supply assurance, regulatory foresight, and channel‑specific commercialization. Our Pw Consulting Digest equips executives to make those choices with confidence, offering the strategic frameworks and operational tools needed to convert market growth into sustainable advantage.
For detailed analysis of this topic, please visit the official page: Digestive Enzyme Complex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


