



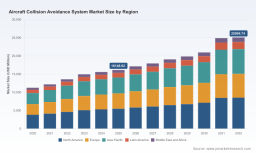
PW Consulting: Aircraft Collision Avoidance System Market Poised to Grow at a 6.5% CAGR (2026–2032), Reaching USD 25,094.74 Million by 2032

Aircraft Collision Avoidance System Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting's new market study on Aircraft Collision Avoidance Systems (ACAS) delivers a practical, decision-focused roadmap for executives planning capital allocation, product strategy, and regulatory engagement in 2026. The global market for collision avoidance technologies has expanded materially over the past half‑decade — rising from roughly USD 11.3 billion in 2020 to about USD 16.1 billion in 2025 — and our base-case forecast anticipates continued expansion at a 6.5% compound annual growth rate (CAGR) through the 2026–2032 horizon, lifting total market value toward the mid‑twenty billion dollar range by 2032. This trajectory reflects a blend of regulatory pressure, platform diversification (including crewed and uncrewed systems), and rapid technology maturation — all of which create both risk and opportunity for OEMs, suppliers, air carriers, and UAS ecosystem players.
Aircraft Collision Avoidance System Market
Why this report matters for 2026 decisions
-
Timing and certification clarity: With the FAA’s March 2026 Technical Standard Order facilitating ACAS Xu certification for unmanned aircraft systems, program timelines and procurement windows are shifting. Our analysis translates these regulatory milestones into tangible deployment scenarios and certification risk multipliers so leaders can prioritize near‑term projects.
Aircraft Collision Avoidance System Market -
Investment prioritization: The market’s steady 6.5% CAGR masks important inflection points driven by ACAS X adoption, retrofit cycles, and new‑platform demand. We show how to allocate CapEx and R&D budgets to maximize returns under alternative adoption curves.
Aircraft Collision Avoidance System Market -
Go‑to‑market design: As manned/unmanned airspace integration accelerates, strategies for partnerships, MRO positioning, and value‑added services (e.g., sensor fusion, predictive maintenance, software upgrades) become decisive. The report provides commercial playbooks tailored to OEMs, suppliers, and integrators.
Key market drivers and inflection points
-
Regulatory acceleration and differentiation. ICAO and regional regulators have long set baseline mandates for collision avoidance system performance; since 2024–2026, however, attention has turned to next‑generation algorithmic approaches. The FAA’s progressive acceptance of ACAS Xa and permitting of ACAS Xu certification, together with ongoing ICAO and EASA compliance programs, are creating a defined, if staggered, pathway for ACAS X family deployment. The practical implication: certification timelines are now a leading indicator of adoption and retrofit volumes.
-
ACAS X and algorithmic performance. ACAS X variants (Xa, Xu, sXu) move beyond rule‑based advisories toward probabilistic conflict resolution, materially lowering nuisance alerts and enabling safer mixed manned/unmanned operations. Operators and integrators that can demonstrate lower false‑alarm rates and smoother human‑machine interaction will command pricing and retrofit preference.
-
Multi‑sensor fusion and low‑SWaP solutions. Advances in sensor fusion — combining ADS‑B, radar altimeter, optical/EO, and inertial inputs — are enabling robust Detect‑and‑Avoid (DAA) stacks for both crewed aircraft and UAS. Vendors pursuing low‑size, weight and power (SWaP) implementations for uncrewed platforms are unlocking large addressable pockets of demand.
-
Safety events and institutional pressure. Recent recommendations from safety authorities following mid‑air investigations have amplified retrofit urgency across fleets. Expect accelerated fleet planning conversations and procurement windows in 2026 as operators weigh regulatory expectations against retrofit cost and downtime.
Competitive landscape — positioning and strategic implications
The collision avoidance market remains moderately concentrated: the top three suppliers account for a meaningful share of installed systems, and the top five further strengthen concentration — a structure that favors scaled incumbents while creating niches for highly specialized innovators. Key company archetypes and strategic recommendations include:
-
Legacy avionics leaders (Honeywell, Collins Aerospace / RTX, ACSS/Thales): These firms combine deep certification expertise, broad installed bases, and extensive aftermarket channels. Their strengths are retrofit scale and regulatory credibility. For incumbents, the clearest growth path is modularizing upgrade offerings (software‑enabled retrofits to ACAS X compatibility), packaging certification support, and leveraging MRO partnerships to capture recurring revenue.
-
Integrated system suppliers (Thales via ACSS, L3Harris): Integration capabilities across surveillance, transponder and advisory functions are a differentiator in transport and rotary segments. These firms should prioritize cross‑domain product suites that lower installation complexity for airlines and helicopter operators.
-
Flight‑deck integrators and GA specialists (Garmin, Avidyne): Focused on business and general aviation, these players translate advanced warning capabilities into user‑centric cockpit experiences. Their commercial opportunity lies in bundled avionics upgrades and targeted retrofit campaigns for mid‑cycle fleet refreshes.
-
New‑wave innovators (Sagetech, select avionics startups): Companies developing ACAS X variants and ultra‑low‑SWaP DAA stacks for UAS are winning design‑win positions in emerging segments. Strategic choices for these firms include aligning with regulatory pilots, joining standards consortia, and securing platform OEM partnerships to scale beyond prototype demonstrations.
-
Implications for buyers: Procurement teams should evaluate suppliers across three dimensions — certification velocity, software upgrade pathways (minimizing recurring hardware changeouts), and aftermarket network reach. Price alone underestimates lifecycle value; negotiate outcome‑based contracts that tie supplier remuneration to demonstrated reductions in nuisance alerts, downtime, or retrofit cycle time.
Report scope and hands‑on deliverables
PW Consulting’s Aircraft Collision Avoidance System Market report is structured to support active decision cycles in 2026 and beyond. Highlights of practical deliverables include:
-
Market sizing and scenario models: transparent top‑down and bottom‑up frameworks (including base, accelerated, and conservative adoption paths), with downloadable inputs for executive sensitivity analysis tied to a 6.5% central CAGR assumption.
-
Certification and regulatory heatmaps: timelines, risk scoring, and step‑by‑step checklists for ACAS X variants and retrofit certification pathways mapped to major regulator milestones.
-
Procurement playbooks and TCO models: retrofit vs new‑install comparisons, downtime optimization levers, and negotiation templates that internal teams can operationalize with suppliers.
-
Technology and supplier scorecards: relative assessments across algorithm performance, sensor fusion, SWaP, retrofit maturity, and support footprint — designed to help MROs and fleet managers shortlist partners.
-
Platform and use‑case playbooks: tailored strategies for commercial transport, business aviation, rotary platforms, and unmanned systems, including BVLOS operational considerations and airspace integration pathways.
-
M&A and partnership diagnostics: identification of capability gaps, strategic targets, and valuation sensitivity tied to certifiable IP and installation pipelines.
Actionable recommendations for 2026
-
Prioritize certification agility: If you are a supplier, convert regulatory milestones (e.g., FAA TSO updates) into concrete product roadmaps and customer certification support packages. If you are an operator, require supplier roadmaps and test evidence as a precondition for long‑lead procurements.
-
Invest in software‑forward architectures: Successful players will monetize continuous improvement (algorithmic updates, reduced nuisance rates) rather than one‑off hardware sales. Allocate at least one third of R&D budgets toward software upgradeability and cybersecurity for advisory channels.
-
Target retrofit windows strategically: Use scheduled heavy maintenance events as the lowest‑cost retrofit opportunity. MRO networks with rapid turn capabilities will capture disproportionate share of near‑term retrofit demand.
-
Engage on joint demonstrations and standardization: For new entrants and incumbents alike, participation in regulatory pilots and standards consortia is table stakes. Early validation in mixed manned/unmanned trials unlocks commercial opportunities as airspace authorities accelerate UAS integration.
-
Screen acquisition targets for certification momentum: In a moderately concentrated market, smaller firms with certifiable ACAS X implementations or unique low‑SWaP DAA solutions make attractive bolt‑on targets. Pay special attention to demonstrated flight test programs and documented interoperability with existing cockpit ecosystems.
Final note — what we intentionally withhold and why
In keeping with the “preview” nature of this release, we have presented macro market trajectories, regulatory inflection points, and supplier archetypes to help executives calibrate strategy for 2026. The report’s full dataset — including granular segmentation by region, system type, and platform; detailed supplier market shares; downloadable financial models; and the interactive scenario tool — is intentionally reserved for report subscribers. This approach preserves the commercial integrity of primary research while ensuring that decision makers who require transaction‑grade detail have a single, authoritative source for procurement and investment execution.
PW Consulting’s Aircraft Collision Avoidance System Market report is operationally focused and tailored for immediate use: program managers can extract retrofit schedules, CFOs can run revised capex scenarios, and corporate development teams can identify targets with live certification momentum. For organizations positioning themselves to lead in the evolving collision avoidance landscape, 2026 will be a year to move decisively — armed with data, certification foresight, and a supplier strategy aligned to a 6.5% CAGR growth pathway.
For detailed analysis of this topic, please visit the official page: Aircraft Collision Avoidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


