



PW Consulting Predicts N Methoxymethyl N Trimethylsilylmethylbenzylamine Market to Rise from USD 20.15 Million in 2025 to USD 33.04 Million by 2032 at a 7.32% CAGR

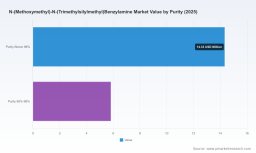
N-Methoxymethyl N-Trimethylsilylmethylbenzylamine Market — Strategic Intelligence Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on N-Methoxymethyl N-Trimethylsilylmethylbenzylamine delivers an operationally focused intelligence package designed to inform procurement, R&D prioritisation, and inorganic growth decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast window, the report synthesises primary supplier mapping, demand drivers, regulatory guardrails, and a calibrated scenario-based outlook. At the macro level the market shows steady expansion, with a compound annual growth rate of 7.32% and a trajectory that takes the total market from the low‑tens of millions (USD, Million unit basis) in recent baseline years to a materially larger market by 2032. This briefing summarises the strategic takeaways and practical use of that intelligence while deliberately withholding the granular segment tables that are available in the full report.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
Why this report matters for 2026
-
Actionable forecasting for a speciality reagent: Organisations that buy or design workflows around this reagent face unique purchasing, regulatory and synthesis risks. Our forecast—anchored on a 2025 base year—identifies inflection points through 2032 so that procurement teams can align contracts, safety stock and alternative-sourcing strategies to avoid disruption.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market -
Quantified growth and concentration dynamics: The market’s mid‑single-digit to high‑single-digit CAGR provides a predictable backdrop for investment decisions. Competitive dynamics are neither fully fragmented nor tightly monopolised: the leading three suppliers capture a significant slice of demand while the top five increase that lead, indicating a balance between global platform players and nimble specialists.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market -
Timing of R&D and scale choices: For chemical and pharmaceutical innovators, the timing to integrate this reagent as a validated route (versus alternative chemistries) is now constrained by supplier roadmaps and lead times. The report helps R&D and process chemistry teams decide whether to lock in supply, qualify substitutes, or invest in backward integration.
What’s inside the PW Consulting report (practical highlights)
-
Forecast and scenario engine: Base-case, upside and downside scenarios through 2032 with sensitivity to raw material availability, regulatory shifts and downstream adoption in pyrrolidine synthesis pathways.
-
Supplier matrix and capability heatmap: Sourcing intelligence across manufacturer types (global distributors, speciality chemists, regional producers), including lead-time benchmarking, qualification pathways and quality/purity tiers.
-
Use-case and application playbooks: Step-by-step guidance for process chemists to assess reagent substitution risk, margin impact in active ingredient synthesis, and scale-up considerations from gram-to-kilogram procurement.
-
M&A and partnership shortlist: Candidate targets and strategic rationale for buyers seeking capability, regulatory footholds, or regional inventory access.
-
Supply‑chain risk and mitigation toolkit: Supplier redundancy maps, minimum viable stock recommendations, and raw-material watchlists tied to upstream trimethylsilyl and benzylamine feedstocks.
-
Regulatory and compliance checklist: Practical controls for ensuring use strictly within research and chemical synthesis contexts; draft contract clauses and labelling best practices to limit unintended therapeutic/consumer application.
-
Price and margin modelling templates: Reverse-engineer scenarios that show the P&L impact of substitution, purity upgrades and freight/cold-chain options.
Competitive landscape — who matters and why
The competitive field blends multinational distributors with specialist manufacturers and regional players. Our vendor intelligence evaluates capability rather than list prices, focusing on quality consistency, catalogue breadth, logistics reach and innovation in handling and packaging.
-
Merck KGaA (Sigma-Aldrich), Darmstadt, Germany ( https://www.sigmaaldrich.com): A global incumbent with strong catalogue reach and trusted specification control. Their positioning is attractive to organisations that prioritise reproducibility and rigorous documentation for regulated R&D workflows.
-
Thermo Fisher Scientific — including Thermo Scientific Chemicals, Acros Organics and Alfa Aesar, Waltham, MA ( https://www.thermofisher.com): Distribution scale and channel depth make Thermo Fisher a go‑to for laboratories requiring rapid access and established procurement pathways.
-
Enamine Ltd., Kyiv, Ukraine ( https://enamine.net): A building‑block specialist that supports medicinal chemists with route-specific expertise—useful for teams designing non‑stabilised azomethine ylide syntheses.
-
BLD Pharmatech and Arborpharm (Shanghai hubs) and several India‑based producers and traders: These regional suppliers provide complementary scale and flexible packaging options, often attractive for cost‑sensitive or volume‑driven projects.
-
Biosynth and Oakwood Chemical: Supply-chain partners that bridge bulk availability with research-scale logistics, relevant to organisations that require interim volumes during process validation.
Strategic takeaway: Buyers should calibrate supplier selection to three vectors—quality/purity tier, speed-to-lab (catalogue access), and supply resilience. Where speed and documentation matter more than unit cost, multinational distributors dominate. For cost and custom packaging, regional manufacturers are often preferable.
Market structure and concentration
PW Consulting’s market-concentration analysis shows a moderate consolidation pattern: the top three providers account for a substantial portion of market demand while the top five increase that share materially. This structure creates pockets of negotiating leverage for buyers who can consolidate volumes or engage in strategic dual-sourcing—but it also exposes single‑source strategies to supplier-specific events. Our model uses a CR3/CR5 framework to quantify bargaining power in supplier negotiations and to model the impact of supplier exits or capacity constraints on pricing and lead times.
Supply chain, regulatory and technical dynamics
-
Primary use-case: The reagent is predominantly employed as a specialised amine for generating non‑stabilised azomethine ylides in [3+2] cycloaddition chemistry, making it an important building block for pyrrolidine scaffolds in medicinal chemistry. This sustained application underpins demand but keeps volumes in the speciality space rather than commodity scale.
-
Upstream exposure: Key feedstocks include trimethylsilylmethyl derivatives and benzylamine precursors. Volatility in upstream availability or shifts in hazardous-substance rules can affect lead times and cost trajectories—variables modeled explicitly in our forecast scenarios.
-
Regulatory boundary conditions: Suppliers and users alike must observe a strict “research‑use‑only” label; the compound is not authorised for medicinal, household or therapeutic claims. Contract terms and labelling that codify this usage are part of the compliance checklist included in the report.
-
Scale and packaging: The market remains largely laboratory-to-kilogram scale. There are no verified large‑volume industrial expansions at the time of publication; companies contemplating high-volume sourcing should evaluate backward integration or tolling arrangements.
Practical recommendations for 2026 (prioritised)
-
Procurement: Establish a dual‑tier sourcing strategy—primary from a validated global distributor for documentation and speed; secondary from a regional manufacturer to negotiate price and volume flexibility. Include contractual clauses for priority allocation during spikes.
-
R&D and process chemistry: Validate alternative routes and reduced‑purity process windows where possible to reduce dependence on the highest‑purity SKUs. Use the report’s substitution decision tree to quantify yield and impurity trade-offs.
-
Supply‑chain resilience: Move from reactive stockholding to a trigger-based safety-stock policy tied to upstream indicators. Implement a quarterly supplier risk review that incorporates our concentration metrics and scenario stress tests.
-
Corporate development: For organisations seeking growth via M&A, prioritise assets that offer backward integration into trimethylsilyl feedstocks, or specialist tolling capacity that can be scaled to meet forecast demand in the upside scenario.
90‑day and 12‑month playbooks
-
90 days: Complete supplier qualification using our checklist; negotiate short‑term priority allocation agreements; and perform a pilot validation of any candidate alternate route to reduce single‑supplier exposure.
-
12 months: Execute supply diversification contracts, integrate price/margin modelling into quarterly planning, and pursue selective partnerships or equity stakes in regional capacity providers if your volume projections meet the thresholds described in the report’s strategic guidance.
What we deliberately withhold here — and why
This briefing is intentionally high‑value but curated as a “trailer”: it communicates the report’s analytical framework, strategic implications and practical tools while withholding granular segment tables (regional and application splits, purity-tier revenue breakdowns and per‑supplier market shares). Those tables are the core actionable inputs for tactical procurement and M&A diligence and are accessible in the full PW Consulting report via our distribution page. The approach preserves the work product while giving decision-makers enough signal to prioritise investment of attention and budget.
How to access the full intelligence
For procurement leaders, process chemistry heads and corporate development executives planning decisions in 2026, the full report contains the segment-level revenue matrices, supplier scorecards, forecast-by-scenario spreadsheets and contractual templates necessary to act with confidence. Contact PW Consulting for a preview package that includes an executive slide deck and a demo of the forecasting tool, and secure access to the full dataset and appendices required for transaction diligence or operational implementation.
Conclusion: The N-Methoxymethyl N-Trimethylsilylmethylbenzylamine market presents a classic speciality‑chemical strategic decision set—modest absolute volumes, predictable growth (7.32% CAGR), and a supplier landscape that rewards thoughtful sourcing, regulatory diligence and selective integration. Organisations that use this reagent should move beyond ad hoc purchasing to a deliberate 2026 strategy informed by the full PW Consulting analysis.
For detailed analysis of this topic, please visit the official page: N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


