



PW Consulting: PI Film Market to Hit USD 3.497B by 2032 at 7.85% CAGR

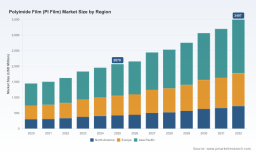
Polyimide Film (PI Film) Market — 2026 Strategic Brief
As PW Consulting’s lead industry analyst, I present an executive preview of our full Polyimide Film (PI Film) Market research — a decision-grade synthesis designed to shape capital allocation, product strategy, and supply-chain moves through 2026 and beyond. Anchored on a 2025 base year and a forecast window from 2026–2032, the market exhibits robust expansion driven by flexible electronics, automotive electrification, advanced aerospace composites, and high-reliability industrial applications. Our core quantitative view: the global PI film market is on a multi-year growth trajectory underpinned by a mid-single-digit-plus compound annual growth rate (CAGR) through the forecast horizon, supported by material substitution, new form-factor products, and structural demand from electrification and advanced packaging.
Polyimide Film (PI Film) Market
Why this research matters for 2026 decision cycles
-
Capex prioritization: Companies must decide whether to expand conventional PI capacity, invest in ultra-thin/colorless lines for flexible displays, or pursue backward integration of key precursors. Our study quantifies the trade-offs between near-term utilization gains and longer-term strategic differentiation.
Polyimide Film (PI Film) Market -
Product roadmap alignment: Product teams need evidence-based guidance on which polymer formats and value-added services (coatings, laminates, patterned PI) will command premium pricing and OEM design wins in 2026–2028.
Polyimide Film (PI Film) Market -
Go-to-market and partnership strategies: OEMs and suppliers require a clear view of distribution, fabrication ecosystems, and which partnerships accelerate qualification timelines for EV, 5G, and foldable-device use cases.
-
Risk and compliance planning: With raw-material volatility and tightening chemical regulations in major jurisdictions, procurement and regulatory teams must calibrate hedging, supplier diversification, and green-chemistry investments.
At-a-glance market trajectory (high-level)
From a resilient historical base, the market reached a notable checkpoint in 2025, and our forecast anticipates continued expansion throughout the 2026–2032 period under a compound growth scenario. The drivers are multi-fold: accelerating adoption of flexible printed circuits and thin-film substrates in consumer and industrial electronics, increased specification of high-temperature PI films in EV traction motors and power modules, and ongoing aerospace/defense demand for high-performance thermal/chemical resistant materials. These demand vectors interact with supply-side constraints and raw-material volatility to create both margin compression risk and premium-pricing opportunities for differentiated players.
What the full report delivers (practical, actionable content)
-
Transparent market-sizing and scenario forecasts — a reproducible quantitative model that maps demand by application, product type, and region across multiple upside/downside cases (available to subscribers as an interactive model).
-
Supply-chain heat map — upstream precursors, critical process steps, global capacity locations, and single-point-of-failure identification to inform procurement and resilience investments.
-
Pricing and margin archetypes — historical pricing dynamics, correlation to feedstock swings, and elasticity insights to support contract negotiation strategies and indexation clauses.
-
Commercial playbooks — go-to-market templates for suppliers targeting OEM qualification (timelines, testing regimes, co-development structures), plus distributor/partner selection criteria for scaling thin-film volumes.
-
Regulatory and ESG impact matrix — scenario planning for tightening EU chemical rules and emissions/solvent restrictions, including transition roadmaps to lower-emission process chemistries.
-
M&A and investment screening — buyer/seller scorecards, valuation multiples sensitivities, and a prioritized list of tuck-in targets and capability gaps for potential acquirers.
-
Board-ready recommendations — succinct strategic options with expected NPV implications, time-to-market estimates, and risk-weighted decision trees.
Analytical backbone: methodologies and data sources
-
Bottom-up demand build combining installed base estimates, OEM BOM analysis, and component-level adoption curves for flexible electronics, EV components, aerospace, and industrial markets.
-
Supply-side mapping using plant-level capacity data, publicly disclosed expansions, and proprietary interviews with manufacturers and major converters.
-
Price and cost modeling that explicitly incorporates volatility in key precursors and energy inputs; scenario analysis shows how feedstock swings (including historic episodes) affect supplier margins and potential pass-through to end customers.
-
Primary stakeholder interviews (manufacturers, Tier-1 OEMs, converters, fabricators), and patent/technology scans to track advances in ultra-thin, colorless, and solvent-free PI technologies.
Competitive landscape — who matters and why
-
DuPont (Wilmington, Delaware, United States) — Established brand strength with Kapton® polyimide films; strong positioning for extreme-temperature, vibration, and chemical-resistance applications across electronics, aerospace, and automotive. Recent capacity expansions target growing colorless/ultra-thin demand.
-
Kaneka Corporation / APICAL (Osaka, Japan & North America) — Known for precise thickness control and dimensional stability; deep relationships in consumer electronics and industrial insulation markets.
-
Arkema (Colombes, France) — Pushing high-performance positioning under a refreshed brand strategy, with offerings aimed at semiconductors, EVs, consumer electronics, and aerospace use cases.
-
Ube Industries (Tokyo, Japan) — Focus on ultra heat-resistant grades and composites applications; maintains strong presence in aerospace and advanced composites channels.
-
PI Advanced Materials, Kolon Industries, Taimide Technology, and regional specialists — Competitive strengths include thin-film innovation, local market access, and application-specific productization for foldables, 5G devices, and automotive wiring harnesses.
-
Distributors and fabricators (e.g., American Durafilm) — Play critical roles in qualification support, small-batch fabrication, and aftermarket channels for aerospace and defense.
Recent developments shaping 2026 strategy
-
Brand and portfolio moves: Arkema’s mid-2025 rebranding of its ultra-high-performance PI range signals intensified competition in premium segments and a push to broaden aerospace and EV footprints.
-
Capacity and technology investments: DuPont’s 2025 capacity expansion for colorless PI films highlights how frontrunners are positioning for foldable and next-gen flexible displays — a clear nod to where innovation value will accrue.
-
Market engagement and visibility: Ube’s participation in major composites trade shows underscores the continued relevance of PI films in high-value aerospace and industrial composites chains.
-
Supply-risk noise: The industry experienced material-price swings in 2024 tied to feedstock inspections and regulatory actions, underscoring procurement risk and the need for diversified sourcing and hedging mechanisms.
Strategic implications and recommended 2026 actions
-
Prioritize optionality in capacity investments: Favor modular and convertible lines that can shift between conventional and colorless/ultra-thin grades to capture premium segments while protecting utilization.
-
Secure precursor supply or consider upstream M&A: Given historic swings in key raw-material pricing and regulatory pressure points, resilience through contracted supply, strategic inventory, or partial backward integration is prudent.
-
Accelerate qualification partnerships with OEMs: Time-to-design-win is a critical barrier; co-development agreements that share testing costs and speed qualification are high ROI moves.
-
Invest in greener chemistries and compliance capabilities: Regulatory tailwinds favor manufacturers that can reduce solvent emissions and demonstrate lower migration risks; early adopters will access premium markets and avoid future compliance bottlenecks.
-
Targeted M&A to fill capability gaps: Buyers should prioritize targets that add ultra-thin processing, patterning capabilities, or geographically strategic capacity to shorten qualification timelines for major OEMs.
-
Design flexible commercial terms: Incorporate feedstock-indexed pricing, volume-flex triggers, and co-investment arrangements to balance supplier margins with OEM procurement predictability.
How PW Consulting can accelerate your 2026 outcomes
Our full Polyimide Film Market report includes the complete quantitative model, granular segmentation tables, plant-level capacity maps, supplier scorecards, regulatory compliance pathways, and a prioritized list of strategic initiatives tailored to your role (investor, supplier, OEM, or private-equity buyer). We also offer implementation support — from diligence for strategic acquisitions to commercial negotiations and regulatory readiness planning.
For senior leaders preparing key 2026 decisions — whether allocating capex, sourcing raw materials, or selecting technology partners — this research is designed to convert market insight into executable options. To access the full intelligence package, detailed segment-level data, and the interactive forecast model, please visit the PW Consulting report page or contact our advisory team for a customized briefing.
For detailed analysis of this topic, please visit the official page: Polyimide Film (PI Film) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


