



PW Consulting: Property Management Software to Grow at 6.98% CAGR Through 2032

Property Management Software Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused primer on the Property Management Software (PMS) market intended to orient executive teams preparing multi-year investment, product and M&A decisions in 2026. This narrative distils the most consequential market signals — historical trajectory, validated forecast, competitive dynamics, regulatory and cost pressures, and tactical imperatives — while reserving the granular segment tables and proprietary scenario permutations for the full report.
Property Management Software Market
Why this briefing matters for 2026
The PMS sector is transitioning from functional automation to intelligence-led operations. Our base-year assessment (2025) captures a market that experienced steady expansion through 2024, a pronounced adjustment in 2025, and a return to growth thereafter. Over the 2026–2032 forecast window, we project a compound annual growth rate (CAGR) of approximately 6.98%, with total market value climbing toward the low‑to‑mid forty millions (USD, revenue unit: Million) by 2032. These dynamics create discrete opportunities and risks for software vendors, property operators, and investors that require immediate strategic decisions in 2026.
Property Management Software Market
Market trajectory — a disciplined view of recent history and short‑term outlook
-
Historical pattern (2020–2024): The market demonstrated robust expansion as landlords and operators replaced legacy systems and adopted cloud-first, mobile-enabled platforms. Our historical series shows substantial year-over-year increases through 2024 driven by product innovation and portfolio digitization.
Property Management Software Market -
2025 correction: In 2025 the market contracted versus 2024. This correction reflects a convergence of macro pressure (cost optimization post‑expansion), vendor repricing, and a pause in large enterprise procurement cycles as buyers reassessed AI and integration readiness.
-
Recovery and forecast (2026–2032): We forecast a disciplined recovery beginning in 2026, underpinned by renewed capital deployment into platforms that demonstrate measurable operational ROI, and by a widening adoption of AI-native capabilities across leasing, revenue management, maintenance and tenant engagement.
Key market drivers and structural dynamics
-
AI and automation as a new hygiene factor: The race is now about operationalizing AI across workflows — not just experimentation. Vendors that move from point AI features to agentic, workflow-embedded intelligence will unlock disproportionate adoption among mid-to-large portfolios.
-
Cloud economics versus control: Cloud platforms continue to attract new customers because of speed-to-value, integration breadth and SaaS economics. At the same time, buyers are increasingly sophisticated about total cost of ownership: cloud hosting costs, region‑specific pricing and hidden fees figure into procurement decisions, especially for multi-jurisdictional portfolios.
-
Regulatory and privacy risk: Data protection is now a board-level priority. Benchmarking shows many firms allocate material budgets to privacy and compliance programs; initial enterprise-scale implementations can be significant. The regulatory environment is tightening in key markets — with enforcement and harmonization initiatives accelerating — which elevates the value of vendors offering hardened compliance tooling and pre‑packaged controls.
-
Operational labor and cost pressures: Property managers face margin pressure from labor and maintenance costs. Software that demonstrably reduces human-intensive tasks (e.g., triaging maintenance, automating accounting reconciliations, or optimizing revenue management) has a clear pathway to premium pricing and stickier contracts.
Competitive landscape — leaders, challengers, and strategic motions
The PMS market exhibits moderate concentration: our market concentration metrics indicate that the top three vendors account for a meaningful but not dominant share of the market (CR3 ≈ 25%), and the top five approach roughly 30% (CR5 ≈ 30%). This structure creates a two‑tier battleground: established firms defending broad portfolios and a vigorous challenger field focused on specialization, vertical depth or pricing agility.
-
Incumbents and scale players: Companies such as Yardi Systems, AppFolio and RealPage remain central to enterprise selection conversations due to comprehensive feature sets, large installed bases, and expanding AI roadmaps. Recent announcements and partnerships demonstrate their focus on scaling platform functionality and retaining enterprise clients through integration breadth and service ecosystems.
-
Fast‑moving challengers: Entrata’s March 2026 release—positioning an AI‑native, agentic operating system—signals intensified competition around autonomous workflows. Vendors offering tightly integrated resident engagement or facility management capabilities are challenging incumbents by delivering specialized ROI in leasing velocity, retention and maintenance spend reduction.
-
M&A and capability consolidation: MRI Software’s acquisition activity (e.g., an asset to bolster tenant experience) exemplifies the inorganic route to rapid feature expansion. Expect continued acquisitive moves from vendors seeking to fill experience, analytics or integration gaps.
-
Specialists and new entrants: A cohort of focused platforms—targeting multifamily, commercial, or facilities management—are leveraging vertical expertise and lower cost models to win smaller portfolios and selectively penetrate larger accounts via API-first architectures.
Recent signposts (2025–2026) that shape strategic options
-
Entrata (Mar 2026): Major product release emphasizing autonomous property management and agentic AI across workflows.
-
AppFolio (Feb 2026): Industry benchmarking showing AI adopters reporting stronger growth expectations and organizational investment plans.
-
Yardi (Oct 2025): Strategic client wins that reinforce platform scalability messaging.
-
MRI (Nov 2025): Targeted acquisition to enhance tenant experience and digital engagement capabilities.
Strategic implications for 2026
-
For vendors: Prioritize three investments in 2026 — (1) embedding agentic AI into high-frequency workflows, (2) accelerating privacy-by-design and compliance automation to reduce buyer friction, and (3) clarifying cloud pricing and TCO models. These moves are essential to convert pilots into multi-year commitments.
-
For property operators and owners: Re-balance procurement criteria to weight measurable cost reduction and revenue uplift over feature checklists. Negotiate contractual terms that align vendor incentives with operational outcomes (e.g., shared-savings models for maintenance or revenue management).
-
For investors and acquirers: Seek targets with demonstrated unit economics where AI lifts margin, not just headline automation. Evaluate integration risk carefully—platform expansion via M&A is valuable only when cross-sell and technical interoperability are credible.
What the PW Consulting report delivers — practical content for execution
-
A validated top‑down and bottom‑up market model covering 2020–2025 historicals, with a granular forecast through 2032 and scenario sensitivity that isolates the impact of AI adoption, cloud migration, and regulatory cost inflation.
-
An actionable playbook for vendors covering product roadmap prioritization, GTM segmentation, pricing strategies, and partner ecosystems — including templated contract clauses for outcome-based pricing and data protection SLAs.
-
Due diligence checklists and valuation sensitivities for M&A, with explicit risk-adjusted return scenarios for bolt-on acquisitions versus organic R&D investment.
-
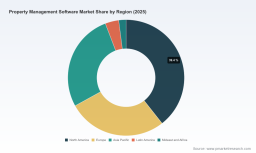
Competitive intelligence dossiers on all major and mid‑tier players, combining product feature matrices, win/loss themes, recent strategic moves, and integration footprints. (Note: the report intentionally withholds raw segment share tables in this preview — full access provides the complete segmentation matrix.)
-
Regulatory and compliance playbook, mapping likely enforcement trajectories in major jurisdictions, budget benchmarks for GDPR-style programs, and practical steps to operationalize privacy controls across SaaS platforms.
How to use these insights in 90–180 day planning cycles
-
Vendors should run a three-month sprint to translate one AI pilot into a productized, SLAdelivered capability tied to a commercial metric (e.g., maintenance ticket resolution time or leasing turnaround). Follow with a six-month commercial test in a controlled cohort.
-
Operators should audit their current vendor stack for hidden cloud costs and privacy gaps; prioritize remediations that unlock contract renewals and reduce operational overhead within one renewal cycle.
-
Investors should require targets to present AI-lifted P&L cases and validated customer references that confirm realized savings or revenue gains before closing deals.
Concluding perspective — positioning for durable advantage
The PMS market in 2026 is less about simplistic feature competition and more about ecosystem orchestration: vendors that couple intelligent automation with demonstrable compliance and transparent economics will capture the strongest growth. The market’s mid‑decade correction has created a buyer base that demands evidence: vendors and investors must now show verifiable ROI, not just roadmaps.
PW Consulting’s full Property Management Software Market report contains the detailed segmentation matrices, vendor scorecards, scenario models and executable playbooks that executive teams need to convert the insights above into decisions. This preview intentionally summarizes the strategic thrust and high‑impact signals — for the granular, actionable intelligence and proprietary data tables, access the complete study on our site.
For detailed analysis of this topic, please visit the official page: Property Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


