



Aluminum Plates Market to Hit USD 39.95B by 2032 at 5.5% CAGR — PW Consulting

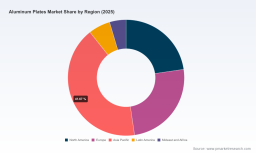
Aluminum Plates Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the aluminum plates market as firms enter the pivotal 2026 planning cycle. Our full market study uses a 2025 base year and traces the 2020–2025 historical arc before projecting out to 2032. In headline terms, the global aluminum plates market expanded from roughly USD 21 billion in 2020 to USD 27.5 billion in 2025, and PW Consulting’s scenario work supports a mid-single-digit compound annual growth rate—5.5%—through the 2026–2032 forecast window, with the market approaching the USD 40 billion range by the end of the period. These macro dynamics frame every near-term commercial decision: procurement, capacity, product strategy, and corporate development.
Aluminum Plates Market
Why this study matters for 2026
-
Precision in a constrained environment: Executives are making capital and sourcing commitments against a backdrop of supply-chain reconfiguration and evolving trade policy. The difference between a 12-month and a 36-month view materially changes the ROI calculus on rolling lines, casting upgrades, and alloy-specific capacity.
Aluminum Plates Market -
From cost management to value capture: Low-carbon premiums, alloy differentiation, and downstream integration are shifting margin pools. Buyers and sellers who align commercial terms with lifecycle cost and sustainability profiles will capture outsized value.
Aluminum Plates Market -
Deal flow and valuation: M&A and joint-venture opportunities are concentrated around specialty alloy capabilities, low-carbon footprint assets, and regionalized finishing capacity. Our research isolates where strategic acquisitions create defensible higher-margin positions.
Key market dynamics shaping 2026 choices
-
Demand composition and secular trends. Aerospace, automotive (including EV body-in-white and structural applications), construction and high-performance industrial applications remain the core volume drivers. Demand growth is heterogeneous across applications: structural and high-strength alloys are growing faster than commodity sheet in many markets, creating material mix shifts that matter for pricing and throughput planning.
-
Supply-side reconfiguration. A mix of integrated producers (smelting-to-rolling), specialty plate makers, and distributors shapes availability. Recent capacity investments and restarts in primary metal and casting/rolling facilities are moderating tightness in certain product lines, but lead times for high-strength plate and specialty temper grades remain lengthy.
-
Input-cost and feedstock evolution. Raw-material cycles—bauxite, alumina and energy—continue to create episodic volatility. Price softening and regional surpluses emerged through 2025, but the structural balance remains sensitive to restart timings, logistical bottlenecks and environmental constraints in alumina refining.
-
Trade policy and industrial strategy. Recent policy moves aimed at strengthening domestic production have altered cross-border economics. Tariff, subsidy and security-of-supply considerations are forcing producers and OEMs to re-evaluate long-term sourcing footprints, regional hedging strategies and local value creation commitments.
-
Decarbonization and product innovation. Low-carbon primary aluminum, electrified smelting, hydro-power integrated production, and improvements in casting/rolling technology are creating differentiation opportunities. Buyers increasingly reward demonstrable lifecycle emission reductions; producers with credible low-carbon credentials command pricing optionality.
Competitive landscape — what matters in 2026
The aluminum plates market sits at a medium concentration level: the top three global participants control a meaningful but not overwhelming share of the market, and the top five collectively approach a plurality position. That concentration profile creates both cooperation and competition dynamics—large integrated suppliers can exert pricing influence and service scale, while nimble specialists capture premium end-markets.
-
Integrated global leaders: Firms with scale in rolling and downstream finishing, established supply relationships with OEMs, and geographic reach are positioned to supply high-volume needs and to influence benchmark pricing.
-
Specialty alloy and defense-focused suppliers: Companies concentrating on 2000-, 6000- and 7000-series alloys and military/aerospace specifications derive stronger margins per ton and benefit from longer qualification cycles that raise barriers to entry.
-
Low-carbon and regional champions: Producers leveraging low-emission power inputs or localized supply chains capture both sustainability-linked premiums and buyer preference in regulated markets.
Relevant market participants covered in our competitive analysis include leading integrated roll-to-cast players, specialty plate makers, regional integrated groups, and major distributors and service centers. Each profile in the full report includes operational footprint mapping, alloy capability matrices, investment pipelines, and an M&A posture assessment—an indispensable input for sourcing and strategic-investor teams.
Recent industry signals you must interpret in 2026
-
Targeted capacity investments and defense-backed programs are redirecting capital toward domestic casting and finishing capability; these projects are changing the availability profile of cast-to-roll plate volumes and qualification windows for aerospace-grade alloys.
-
Commercial product expansions in prepainted and value-added flat products indicate distributor and coil-coating segments are seeking higher-margin offerings and faster time-to-market for architectural and industrial customers.
-
Market noise around feedstock and alumina supply has created short-term price swings and excess availability in certain regions; buyers that build dynamic purchasing protocols and sprint-response logistics can convert volatility into a competitive advantage.
Scenario implications for 2026 decision-makers
-
Base Case (Mid-single-digit growth, continued re-shoring): Expect steady demand growth in core applications and gradual easing of some supply constraints. Recommendation: prioritize flexible capacity upgrades that reduce time-to-qualification for high-strength alloys, and secure staged offtake agreements with variable-price collars.
-
Protectionist/Regionalization Upside: If trade barriers and strategic procurement intensify, regional players with local casting/rolling capacity and secure feedstock access will outcompete distant suppliers. Recommendation: accelerate local partnerships, shorter supply chains and inventory decentralization.
-
Rapid Demand & Premiumization: In a technology- or policy-driven spike in demand for low-carbon or high-strength plates, capacity will be the constraining factor. Recommendation: pursue bolt-on acquisitions in specialty plate makers, enter into capacity reservation agreements, and prioritize premium alloy R&D.
Actionable playbook — priority moves for 2026
-
Establish a tariff- and subsidy-aware sourcing playbook. Reprice long-term contracts to reflect regional policy shifts and maintain alternative sources for critical alloy grades.
-
Lock in alloy-specific supply through qualification-focused partnerships. Invest in jointly-funded qualification lines to cut time-to-approval for aerospace and defense OEMs.
-
Layer sustainability into procurement and commercial terms. Include lifecycle emission metrics in supplier selection and develop a premium pricing strategy for low-carbon plate variants.
-
Pursue selective M&A to secure specialty alloy capabilities and local finishing capacity. Target assets that shorten qualification cycles and raise entry barriers for competitors.
-
Optimize inventory and hedging for input cyclicality. Use blended hedges and dynamic safety stocks for alumina-based risk while maintaining responsiveness to product-specific lead times.
-
Embed technical differentiation through R&D partnerships. Co-develop higher-strength, manufacturable tempers and coatings that reduce total system cost for OEMs.
What PW Consulting’s full report delivers (teaser)
-
Granular, scenario-based demand model to 2032 with application-by-alloy trajectories (note: specific segment-level tables are available in the full report).
-
Supplier and capacity atlas with operable footprints, grade capabilities, expansion pipelines and regional service-network maps.
-
Tariff and policy impact simulator that models landed-cost outcomes across alternative sourcing routes and duty scenarios.
-
Cost curve and margin pool analysis for commodity vs. specialty plates, including sensitivity to energy and alumina cost paths.
-
Competitive profiles and strategic playbooks for leading players, including capacity and investment signals to watch for.
-
M&A screening list and valuation templates tailored to strategic and financial buyers, plus a prioritized due-diligence checklist.
-
Buy-side and sell-side negotiation tools, procurement templates, and a recommended governance framework for long-term supply agreements.
Concluding guidance
For executives setting 2026 budgets and strategic roadmaps, the aluminum plates market presents a classic combination of structural growth and tactical uncertainty. The mid-single-digit CAGR to 2032 underlines a sizable commercial opportunity, yet value capture will be concentrated in alloy differentiation, low-carbon credentials and regional supply-security plays. Our report is designed to accelerate the required strategic choices—what to build, buy, or reserve—and to translate market dynamics into executable commercial and M&A actions.
PW Consulting’s full study provides the confidential, data-rich foundation for those decisions. The public primer you are reading purposefully omits the core, segment-level datasets and price curves that are essential to transaction- and procurement-grade work. Contact PW Consulting for the complete dataset, bespoke scenario workshops, or a focused executive briefing to convert the 2026 planning horizon into a defensible and value-accretive strategy.
For detailed analysis of this topic, please visit the official page: Aluminum Plates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


