



PW Consulting: Atomic Clock Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Atomic Clock Market 2026: Strategic Imperatives for Decision-Makers
As organizations recalibrate technology roadmaps and procurement priorities for 2026, high-precision timing has risen from a niche engineering concern to a strategic enabler across navigation, communications, defense, and scientific infrastructures. PW Consulting’s forthcoming Atomic Clock Market study provides a concise, actionable synthesis of market dynamics, vendor positioning, and go-to-market scenarios designed specifically to inform executive decision-making in the year ahead. This introduction outlines the study’s strategic value and highlights the practical intelligence executives will need to set investment, sourcing, and partnership priorities in 2026 — while preserving the granular segmentation analytics for subscribers who access the full report.
Atomic Clock Market
Macro trajectory: market scale and the investment horizon
The atomic clock sector is unmistakably growing. Global market size rose from a baseline of roughly USD 163 million in 2020 to approximately USD 215 million in the base year (2025). Our forecast model — driven by demand growth in navigation, telecom holdover solutions, and defense-grade timing — projects a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 period, taking the market to roughly USD 345 million by 2032. Those headline figures frame the size of the prize for systems integrators, component suppliers, and public agencies considering multi-year programs for precision timing.
Atomic Clock Market
Why this research is mission-critical for 2026 decisions
- Procurement timing: The forecast and scenario work in our study enable procurement teams to time capex and multi-year contracts to benefit from incremental performance gains in optical and trapped-ion technologies while avoiding early obsolescence.
- Technology roadmaps: R&D and product chiefs can use our assessment of holdover performance, integration complexity, and maintenance cost profiles to prioritize modular upgrades versus forklift replacements.
- M&A and partnerships: With a fragmented market structure (top-three firms control under one-quarter of the market and top-five firms remain only marginally higher), the report identifies where industry consolidation will create scale advantages and where bolt-on acquisitions can rapidly accelerate capability.
- Supply-chain resilience: Our supplier-risk mapping highlights single points of failure in strategic raw materials and precision components — insight that informs dual-sourcing, inventory policy, and supplier development strategies.
- Regulatory and standards engagement: For organizations competing in regulated sectors (telecom, defence, metrology), the report shows which standards and national metrology activities will materially affect certification and procurement windows in 2026–2028.
What the full report delivers (practical, executable content)
We designed the report to be immediately usable by cross-functional teams. Highlights of the deliverables include:
Atomic Clock Market
- Market sizing and verified outlooks (2020–2032) with scenario variants (baseline, accelerated adoption of optical clocks, risk-constrained downside).
- Supplier and component supply-chain maps identifying critical raw material exposures (e.g., rubidium, cesium), specialized quartz and vacuum components, and single-source risks.
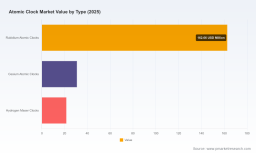
- Technology maturity and integration profiles, including holdover performance thresholds, environmental requirements, and life-cycle maintenance costs for Rubidium, Cesium, Hydrogen Maser, and emerging optical/ion solutions.
- Go-to-market playbooks tailored to vendors and end-users — covering procurement RFP templates, proof-of-concept criteria, test‑lab specifications, and operational acceptance thresholds.
- Vendor scorecards and a validated shortlist methodology for M&A and supplier selection; an acquisition-screening checklist for strategic buyers and private equity.
- Regulatory impact assessment and recommended engagement paths with national metrology institutes and standard-setting bodies to accelerate certification and adoption.
- Risk matrices and mitigation plans for high-cost development programs (vacuum systems, cryogenics, controlled environments) and for supply disruptions of specialty gases and precision electronics.
Competitive landscape: strategic implications for vendors and buyers
The market remains technology-diverse and commercially fragmented, creating distinct strategic postures for incumbents, challengers, and new entrants. Notably, the market concentration metrics indicate significant room for consolidation and differentiation — an insight that should shape 2026 M&A, partnership, and alliance strategies.
- Specialist suppliers (e.g., niche rubidium and oscillator manufacturers) continue to compete on compactness, cost-to-operate, and proven field reliability. These firms are attractive acquisition targets for larger system integrators seeking to internalize timing modules.
- Large, diversified players with multisector portfolios can leverage scale to offer integrated timing-plus-communications solutions to telecom and defense prime contractors; they are also better positioned to absorb the R&D and capital intensity of optical and ion-based clocks.
- Innovative entrants and quantum-focused firms (including those with optical atomic clock and trapped‑ion competencies) are pushing the frontier of precision but require pathways to industrialize sensitive lab-grade systems for field use.
In the full report we provide vendor-level strategic profiles that map capability, end-market focus, and likely partnership roles. Public examples of market movements that inform those profiles include a recent acquisition and several technology milestones that materially affect competitive dynamics:
- Strategic M&A activity has started to reshape the landscape: a prominent quantum information company completed an acquisition to embed rackmount optical atomic clocks and synchronization hardware into its sensing and PNT portfolio — signaling that quantum-capable firms are pursuing rapid vertical integration to access defense and federal markets.
- Metrology breakthroughs continue to recalibrate expectations: national labs have demonstrated trapped-ion clocks with unprecedented precision, and operational cesium fountain systems have been brought into full service for national time dissemination — developments that will influence buyer calculus for the highest-stability reference clocks.
- Productization progress by established suppliers has narrowed the gap between laboratory accuracy and telecom-ready holdover performance: new optical cesium models now achieve multi-week holdover accuracy targets that meet or exceed telecom standards, lowering the technical barrier for network operators to adopt higher-precision references.
Practical strategic recommendations for 2026
Based on the macro trajectory and supplier dynamics, the following actions should be prioritized by enterprise decision-makers in 2026:
- Align procurement windows with technology maturation: For non-mission-critical systems, favor modular upgrades and staggered deployments to capture improved holdover economics from new optical variants without incurring early replacement costs.
- Hedge supply-chain risk: Map and qualify alternate sources for critical gases and precision parts; evaluate inventory strategies for long-lead items and secure contractual protections for suppliers with constrained production capacity.
- Pursue targeted partnerships and minority investments: For system integrators and large OEMs, minority stakes or strategic JV agreements with optical/ion innovators accelerate productization timelines and provide privileged access to advancing IP.
- Use standards engagement to accelerate procurement acceptance: Participate in working groups with metrology institutes and standards bodies to influence test protocols and to ensure new products meet certification paths required by telecom and defense buyers.
- Run acquisition screens focused on modularity and services: Prioritize targets that offer repeatable module designs and service contracts; ownership of field-reliable modules can convert fragmented revenue streams into long-term service annuities.
- Budget for lifecycle costs, not just headline price: Include maintenance, environmental control, and calibration schedule costs in TCO models — advanced systems can have higher up-front costs but lower long-term failure and replacement risk in mission-critical applications.
Scenario planning: three plausible 2026-2030 pathways
Our report builds three investable scenarios to guide capital allocation:
- Baseline: Market grows in line with the 6.98% CAGR forecast as telecom modernization and GNSS resilience projects continue to expand demand for stableholdover devices.
- Accelerated adoption: Faster-than-expected industrialization of optical and ion clocks combined with favorable procurement cycles in defense and major telcos pushes adoption and compresses price erosion curves — creating attractive entry opportunities for firms that can scale production.
- Constrained risk-downside: Budgetary slowdowns, supply-chain interruptions for specialty gases or vacuum components, or slower standards harmonization delay procurement cycles and lengthen time-to-value for larger, costlier systems.
How to use this report in day‑to‑day decision-making
Operationalize the study by embedding its outputs into quarterly reviews and procurement gates: use the vendor scorecards to short-list suppliers for RFPs, apply the scenario sensitivities in capex approval decks, and leverage the supply-chain maps in continuity planning workshops. For boards and investors, the report’s M&A playbook and valuation heuristics enable faster, lower-risk assessments of target fit and upside potential.
Closing: where this intelligence creates value in 2026
Timing technology sits at the intersection of national infrastructure resilience and commercial service availability. In 2026, executives face choices that will lock in platform capabilities for the next decade. PW Consulting’s Atomic Clock Market study distills the essential market scale (with a clear forecast trajectory), the supplier-and-technology implications of recent breakthroughs, and the practical steps organizations must take to convert timing precision into durable strategic advantage. For teams prioritizing resilience and competitive differentiation in navigation, telecom, defence, and advanced R&D environments, the report is engineered to be operationally relevant on day one — while preserving the detailed segmentation and vendor-specific metrics exclusively for subscribers and licensed users.
For detailed analysis of this topic, please visit the official page: Atomic Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


