



PW Consulting: Medical X-Ray Tube Market to Reach USD 186.7M by 2032 at 5.4% CAGR

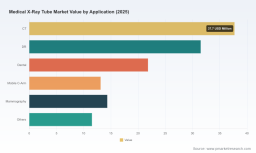
Medical X‑Ray Tube Market: Strategic Preview for 2026 Decision‑Making
As PW Consulting’s lead industry analyst, I present this strategic preview of our forthcoming Medical X‑Ray Tube Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This briefing synthesizes the macro trajectory, competitive dynamics, regulatory inflection points, and actionable planning levers that matter for capital allocation, supply‑chain choices, and go‑to‑market strategies in 2026. Consider this a high‑fidelity trailer: it demonstrates the depth and operational focus of our full research while reserving the proprietary segment-level detail for subscribers and clients who download the complete report.
Medical X-Ray Tube Market
Why this market matters in 2026
Medical X‑ray tubes remain a foundational technology underpinning diagnostic imaging and certain interventional modalities. After steady expansion through the early 2020s, the market displays resilient mid‑single‑digit growth driven by imaging volume recovery, capacity upgrades in advanced modalities, and demand for aftermarket and refurbishing services. Our base‑year assessment places the market at approximately USD 130 million (2025), building from about USD 107.7 million in 2020 and projecting to roughly USD 186.7 million by 2032, which corresponds to a compound annual growth rate of 5.4% over the forecast window. These headline figures frame the investment case: the market is large enough to support specialized players and mature enough to reward operational excellence and regulatory competence.
Medical X-Ray Tube Market
Core takeaways for 2026 corporate strategy
- Prioritize service and aftermarket economics: Aftermarket replacement and refurbishment provide margin resilience and faster revenue realization than new OEM tube sales. Our analysis finds that health‑system aftermarket contracts can materially reduce replacement turnaround—improving uptime and repeat business—making service capability a key differentiator for both independent suppliers and OEMs.
- Regulatory readiness is a competitive moat: Compliance with FDA 510(k), IEC‑60601 family standards, and ISO 13485 continues to be a gating factor for market access. Recent regulatory events (including an FDA Class II recall tied to rotating support assemblies in late 2025) underline that quality management and post‑market surveillance are not optional for market leaders.
- Capitalize on CT modernization cycles, but hedge exposure: High‑throughput CT platforms are a growth vector; players that align tube capability, thermal management, and serviceability to CT upgrade paths stand to capture disproportionate value. At the same time, diverse application footprints and aftermarket channels reduce dependency on any single modality cycle.
- Supply‑chain and input cost management matter: Manufacturers faced margin pressure in 2026 as energy, material, and labor costs rose. Notably, some suppliers maintained pricing throughout 2026 despite cost headwinds—an operating choice that may pressure margins but preserve market share. Firms should model both price elasticity and the cost of service differentiation when refining 2026 budgets.
Market structure and competition — what we found
The market exhibits moderate concentration: the top three suppliers control a meaningful share of installed base replacement volumes, with the top five increasing the concentration further. This structure creates both opportunity and risk: scale enables global aftermarket logistics and extensive compatibility catalogs, while independents can win via speed, cost‑effective refurbishing, and niche product breadth.
Medical X-Ray Tube Market
- Varex Imaging Corporation (Salt Lake City, USA): A leading independent supplier with a broad tube portfolio and image processing capabilities, producing tens of thousands of tubes annually across CT, diagnostic, mammography, and other modalities. Their 2025–2026 catalogue updates and compatibility expansions are tactical moves to cement aftermarket share.
- Dunlee (Hamburg, Germany): Positioned with a strong OEM heritage in CT tube and high‑voltage generator systems. Dunlee’s alignment with major scanner platforms makes it a strategic partner for system integrators and hospitals pursuing high‑throughput imaging upgrades.
- IAE S.p.A. (Cormano, Italy): Europe’s noted independent rotating‑anode specialist, with a reputation for quality manufacturing and engineering focus on diagnostic imaging systems. Their product depth supports both OEM and replacement channels across Europe and beyond.
- Ray‑Pac (South Carolina, USA) & X‑Ray America (Charleston, USA): These aftermarket specialists emphasize replacement and repair services for installed fleets, with catalog and distribution expansions in 2025 that improved in‑stock availability for many models—an operational response to customer demand for reduced downtime.
- Superior X‑Ray Tube Company (Illinois, USA): A specialist in custom and general‑use tubes with in‑house design and manufacturing capabilities—an asset for bespoke clinical and industrial applications.
Recent corporate moves (e.g., new compatibility catalogs, product relaunches for legacy platforms, and consolidation among aftermarket players) underscore a tactical emphasis on service coverage and cross‑platform replacement parts. These trends are summarized in our full competitive matrices and capability maps.
Regulatory and reimbursement dynamics shaping the operating environment
- Regulation and standards compliance: X‑ray tubes for medical diagnosis are subject to Class II device pathways in the U.S. and must satisfy IEC and related NEMA/ASTM specifications for electrical, mechanical, and focal‑spot characteristics. The 2025–2026 period saw active regulatory management, including an FDA Class II recall tied to ceiling support shafts—highlighting the reputational and financial implications of even localized field events.
- Reimbursement and service economics: Health‑system contracting trends favor providers that deliver predictable uptime and fast replacement cycles. Our review finds aftermarket contracts and OEM service programs reducing average replacement turnaround times materially—creating a value pool around logistics, spares inventory, and rapid technical support.
- Input cost pressures: Despite rising manufacturing, material, and energy costs, some suppliers held pricing steady through 2026—an indicator that competitive positioning and contract pricing stability were prioritized over short‑term margin protection in many cases.
Report deliverables and practical assets (what the full study contains)
The full PW Consulting report is designed for strategic decision‑makers who need executable intelligence in 2026. Highlights include:
- Proprietary market model with historical performance (2020–2025) and a detailed 2026–2032 forecast (growth drivers and sensitivity analyses). Note: our public preview supplies headline market sizing and CAGR; segmented revenue and regional shares are available in the full dataset.
- Service economics playbook—benchmarks for aftermarket margins, typical replacement lead‑times, and best‑practice spares inventory strategies to reduce system downtime.
- Regulatory and risk matrix—mapping compliance requirements, recent recalls, and mitigation frameworks tailored to medical device manufacturers and service providers.
- Competitive intelligence pack—company profiles, capability maps, M&A and product launch timelines, and a supplier scorecard that rates scale, aftermarket reach, product breadth, and regulatory controls.
- Strategic options analysis—scenarios for market entry, bolt‑on acquisition targets, partnerships for CT supply, and price‑service tradeoff modeling to inform 2026 CAPEX/OPEX decisions.
How to use this intelligence in 2026
- Investment committees: Use our forecast and concentration analysis to size the addressable opportunity for acquisitions and to stress‑test synergies against service‑level guarantees.
- Product and R&D leaders: Align tube development priorities with CT thermal demands, reliability targets, and serviceability criteria to shorten time‑to‑value for hospital procurement cycles.
- Commercial teams: Reframe offers around uptime guarantees, bundled service agreements, and validated compatibility catalogs to capture aftermarket share where delivery speed is a purchase trigger.
- Supply‑chain and operations: Reassess spares stocking, refurbishment throughput, and dual‑sourcing strategies to mitigate component cost volatility and regulatory hold‑ups.
Final reflections and next steps
The Medical X‑Ray Tube market in 2026 presents a blend of steady demand growth and tactical battlegrounds around aftermarket service, regulatory discipline, and platform compatibility. With a projected CAGR of 5.4% and a clear path from the 2025 base to 2032, the market rewards firms that combine engineering credibility with logistics excellence and compliance rigor. Our full report translates these macro trends into measurable moves—target lists, margin scenarios, and product/service design criteria that executives can operationalize in 2026.
To access the detailed segment breakdowns, region and application shares, full company scorecards, and downloadable data models that underpin the analyses in this preview, please download the complete PW Consulting Medical X‑Ray Tube Market report from our research portal. The full dataset is purposefully gated to ensure that paying clients receive the granular inputs necessary for transaction and operational planning.
For detailed analysis of this topic, please visit the official page: Medical X-Ray Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


