



PW Consulting: Road Sweeper Market to Grow at 4.4% CAGR, Hitting USD 3.69B by 2032

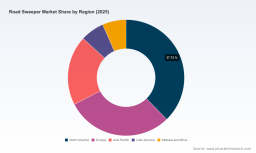
Road Sweeper Market — 2026 Strategic Outlook and Decision Playbook
As governments, fleets, and technology vendors recalibrate around air-quality mandates and urban resilience, the road sweeper market has entered a phase where near-term procurement choices will determine competitive positions across the decade. This preview outlines the strategic value of PW Consulting’s Road Sweeper Market report for executives making decisions in 2026. It conveys the report’s analytical depth and practical outputs while intentionally reserving detailed segment-level tables and regional breakdowns for the full study to maintain an effective “trailer” that drives stakeholders to the complete intelligence package.
Road Sweeper Market
Macro frame: market trajectory that should guide 2026 planning
At the aggregate level, the global road sweeper market exhibits steady expansion underpinned by regulatory tightening, urbanization, and accelerating product innovation. From a base of approximately USD 2.73 Billion in 2025, our forecast model — reflecting the historical 2020–2025 dynamics and multiple policy scenarios — points to mid-single-digit growth through the 2026–2032 forecast window, with a compound annual growth rate of 4.4% and an expected market size approaching USD 3.7 Billion by 2032. The path is not linear: the historical series shows pockets of softness alongside rebound years, signaling that geography, fleet replacement cycles, and technology adoption will be key modifiers of local demand.
Road Sweeper Market
Why this research matters for 2026 corporate decisions
- Timing capital deployment. The market’s steady CAGR and policy-driven fleet upgrades mean 2026 is a pivotal year to commit CAPEX for electrification pilots, hydrogen trials, or large procurement frameworks that will deliver returns across the forecast horizon.
- Prioritizing R&D vs. M&A. Our scenario analyses identify where internal innovation creates differentiated value versus where targeted acquisitions or partnerships are a faster route to technology or distribution scale.
- Negotiating vendor and supplier contracts. The study’s supply-chain risk maps and cost-curve analytics enable procurement teams to lock favorable terms or to hedge material exposure ahead of anticipated pricing cycles.
- Designing go-to-market mixes. Municipal tenders are evolving into multi-criteria procurements (air-quality outcomes, lifecycle emissions, total cost of ownership, digital telemetry). The research provides playbooks for tailoring offers to diverse buyer expectations.
What the full report delivers (practical, operational outputs)
- Market sizing and validated forecasts (2026–2032) with scenario splits for policy, fuel-cost, and macroeconomic sensitivity.
- Segment performance analysis across vehicle types, applications, and regions, with growth vectors and risk profiles (note: detailed numerical splits and regional tables are available in the full report).
- Regulatory and standards matrix tying local air-quality mandates and vehicle emissions rules to procurement timing and specification impacts.
- Technology roadmaps (electrification, regenerative air, automated sweeping, hydrogen integration) with adoption curves and commercialization milestones.
- Supplier and materials assessment, including input-cost volatility and strategic sourcing recommendations.
- Competitive benchmarking: deep profiles of >12 OEMs, technology adjacencies, partnerships, and recent product and go-to-market moves.
- Commercial playbooks: tender-response templates, leasing/subscription models, and municipal engagement frameworks tailored to 2026 procurement cycles.
- Investment and M&A shortlist with valuation heuristics and integration risk checklists.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration at the top: the three largest suppliers account for a sizable share of global revenue, and the top five increase that share materially. This structure creates both opportunities for scale players to defend premium pricing and for specialist vendors to exploit niche technical or geographic advantages.
Road Sweeper Market
- CEKSAN SWEEPERS (Turkey) — Known for eco-focused designs with effective dust suppression and noise reduction systems; attractive for municipalities prioritizing community impact and regulatory compliance.
- SWP (China) Clean Equipment Limited — A Sino-US joint venture that leverages compact, high-tech designs and cost-efficient manufacturing; a natural partner for global OEMs seeking scale in emerging markets.
- Elgin Sweeper Company / Alamo Group — A US-based lineage combining mechanical, regenerative air, and electric platforms; strong in airport and industrial channels.
- Bucher Municipal — Swiss engineering and an early mover on EV and hydrogen integration; recent initiatives indicate a pivot toward automation and digital services.
- Schwarze Industries and TYMCO — US specialists with deep expertise in regenerative air technology and heavy-duty sweepers; ideal acquisition targets for firms wanting technical depth in niche cleaning modalities.
- Boschung and Kärcher Municipal — European innovators pushing compact electric solutions and urban-focused machines, including recent product upgrades tuned to zero-emission urban tenders.
- Hako, Fayat Group, Hubei Chengli — Regional champions with strong distributor networks; critical partners when scaling localized service and spare parts for tenders.
Recent industry moves illustrate momentum: product launches of next-generation electric sweepers and trade-show unveilings of heavy-duty mechanical models in 2025 signaled R&D intensity, while companies announced digital transformation and hydrogen integration initiatives that point to dual pathways — electrification for urban fleets and alternative energies for heavy/high-duty use cases. A product delivery in mid-2026 demonstrates that vendors are rapidly converting R&D into fielded assets, elevating the pace for buyers evaluating pilots versus full fleet replacements.
Regulatory and operational tailwinds that shape 2026 choices
- Stricter air-quality mandates in multiple jurisdictions are creating quantifiable procurement triggers: cities that must demonstrate PM reductions will tend to prioritize higher-specification sweepers and increased sweep frequency budgets.
- Global guideline tightening (e.g., revised WHO particulate limits) acts as a policy multiplier—expected to accelerate minimum performance standards and procurement scoring criteria in many markets.
- National programmes requiring sub-35 µg PM2.5 targets in major Chinese cities are a clear demand accelerator for upgraded fleets and technology retrofits in those municipalities.
- Material input volatility — notably ferrous alloys used in brush and hardware components — is creating margin pressure and stimulating interest in alternative materials or supplier diversification strategies.
- Operational best-practice regulations, such as mandatory operator training, increase lifecycle cost transparency and favor OEMs that bundle training and certification into their offers.
Actionable playbook for 2026 executives
- Prioritize pilot-to-scale pathways: Run geographically targeted pilot programmes (electric + telematics) in cities with imminent air-quality compliance deadlines to de-risk large procurements.
- Accelerate modular product roadmaps: Invest in modular architectures that decouple chassis from sweeping modules to shorten time-to-market and ease upgrades (battery, brush systems, filtration).
- Negotiate supplier options and hedges: Secure multi-year agreements or financial hedges for critical ferrous and electronic components to stabilize costs through 2027.
- Bundle outcomes with services: Transition from unit sales to outcome-based contracts (e.g., guaranteed PM reductions, availability SLAs, and predictive maintenance) to capture higher lifetime value.
- Target bolt-on M&A: Seek small-cap specialists (regenerative air, niche electric controllers, or digital maintenance platforms) that provide rapid capability uplift with limited integration risk.
- Engage regulators proactively: Shape tender specifications by providing evidence-based emissions testing and TCO models so procurement criteria reward true lifecycle outcomes.
- Localize service footprints: In fast-growing regions, prioritize joint ventures or distribution partnerships that provide spare parts velocity and local operator training to win municipal tenders.
How to use the full PW Consulting report
The full report expands on the themes summarized here with granular, executable intelligence: segment-level revenue and growth tables, regional and application breakdowns, supplier scorecards, tender-scoring templates, and interactive scenario models. For teams preparing 2026 budgets, the downloadable financial model inside the subscription provides a customizable TCO calculator and supplier comparison matrix, enabling direct insertion into procurement evaluations and board-level business cases.
Because strategic differentiation hinges on the detail — which specific vehicle types, regions, and application pockets will grow fastest — we reserve those detailed numeric segmentations and ranked supplier scorecards for the full report. This preview is designed to give you a clear sense of the directional imperatives and immediate actions; the complete intelligence package empowers procurement, product, and corporate development teams to execute with precision.
2026 represents a decisive year: policy pull, technology supply, and procurement sophistication converge to reshape demand. Organizations that act with data-driven clarity — prioritizing pilots, supplier resilience, and outcome-based commercial models — will capture outsized value as the market scales toward the late‑decade inflection. PW Consulting’s full Road Sweeper Market report provides the actionable roadmap and financial tools required to convert that opportunity into advantage.
For detailed analysis of this topic, please visit the official page: Road Sweeper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


