



PW Consulting: TPEE Market to Reach USD 2,430.29M by 2032 at 7.62% CAGR

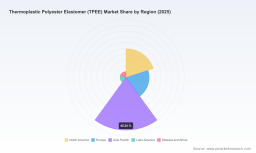
Thermoplastic Polyester Elastomer (TPEE) Market — Strategic Preview for 2026 Decision-Makers
Executive synopsis
As companies calibrate supply chains, product portfolios, and M&A priorities for 2026, Thermoplastic Polyester Elastomer (TPEE) sits at an inflection point. Our new PW Consulting market study tracks a clear recovery and growth trajectory from the pandemic trough through a 2025 base and projects robust expansion across 2026–2032. With a compound annual growth rate (CAGR) of approximately 7.6% through the forecast period, the TPEE market is transitioning from niche engineering applications to broader adoption across mobility, electrification, durable consumer goods, and selected industrial segments.
Thermoplastic Polyester Elastomer (TPEE) Market
Market trajectory and what the headline numbers mean for strategy
-
Momentum: The market recovered steadily over 2020–2025 and enters 2026 from a position of strength, reflecting both pent‑up demand and new product pathways that broaden TPEE applicability.
Thermoplastic Polyester Elastomer (TPEE) Market -
Scale: Aggregate market revenues—reported on a USD million basis—show sustained expansion year-on-year in our baseline scenario. This scale enables a wider array of commercial strategies, from regional production optimization to multi-tiered price architectures for value and performance grades.
Thermoplastic Polyester Elastomer (TPEE) Market -
Growth quality: The projected ~7.6% CAGR is not merely volume-driven. It combines higher-value use cases (e.g., EV battery thermal components, performance consumer footwear midsoles, and demanding electrical insulation) with incremental penetration in conventional segments where TPEE replaces legacy elastomers and thermoplastics.
Why this report matters to 2026 decision-makers
-
Actionable demand forecasting: Our study translates headline growth into demand scenarios by application class and polymer grade (injection, extrusion, blow molding), enabling procurement teams to stress-test supplier contracts and capacity commitments without relying on point-in-time anecdotes.
-
Cost-to-profit modelling: Embedded price-sensitivity frameworks link raw material indices (including observed PBT price movement in early 2026) to finished-goods margins, helping commercial teams quantify the impact of feedstock volatility and pass-through options.
-
Strategic supply mapping: We provide layered supplier maps and contingency routes—vital for firms reassessing onshore vs. offshore production given evolving tariff dynamics and regional trade frictions that already affect automotive supply chains.
-
Regulatory readiness: With tightening chemical regulations under frameworks such as REACH, product teams need to plan reformulation and substitution roadmaps. The report benchmarks compliance risk across grades and geographies and prioritizes reformulation pathways with the highest probability of commercial success.
Key market dynamics shaping 2026 decisions
-
Raw material and input-cost signals: Early‑2026 feedstock indices presented modest upward movement in PBT pricing within the U.S. market, while domestic supply remained broadly stable. For buyers and planners, this translates into manageable, short‑term margin pressure but elevated sensitivity to further upstream shocks.
-
Regulation and reformulation: The REACH environment and similar global regulatory updates are driving continuous product reformulation, particularly for flame‑retardant and medical-grade variants. Firms without proactive R&D and regulatory monitoring will face increasing time-to-market delays and increased compliance costs.
-
Trade and tariff volatility: Targeted tariffs and trade measures are already having practical impacts on component flow—most notably where automotive tier suppliers import specialized TPEE compounds. Procurement and logistics teams must model tariff scenarios and build alternative sourcing options into commercial contracts.
-
Innovation pull vs. cost push: The market is characterized by simultaneous demand for premium performance (high-temperature stability, oil resistance, biocompatibility) and pressure to lower total system cost. Winners will be those who can segment offerings and capture both premium and cost-conscious demand streams.
Opportunities and risks—where to invest scarce resources in 2026
-
High-opportunity pockets: Electrification (battery components, thermal management), advanced consumer footwear, and certain medical applications represent above-average margin opportunities due to technical requirements and certification barriers.
-
Operational risks: Single-source dependencies for specialty grades and geographic concentration of compounding capacity create interruption risk. Scenario planning and dual-sourcing strategies are essential near-term actions.
-
Sustainability as a commercial lever: Sustainable formulations and recycled-content offerings are rapidly moving from niche marketing claims to procurement table stakes. Early investments that reduce product carbon footprint while preserving performance will unlock contracts with OEMs aligning their supply chains to net‑zero targets.
-
Regulatory execution risk: REACH-driven reformulations and regional compliance regimes can materially affect time-to-market for new grades; proactive regulatory engineering will be a differentiator.
Competitive landscape—what leading suppliers signal for 2026
The supplier ecosystem spans global chemical majors, specialized polymer houses, regional compounders, and custom compounders. Recent company moves reflect both portfolio upgrading and commercial repositioning:
-
Celanese has signalled commercial tightening via price increases on flagship engineered materials ranges—an indicator of end‑market strength and feedstock/operational cost pressure. For buyers, this underscores the need for hedging and supplier negotiation playbooks.
-
Envalior (carrying forward the DSM Engineering Plastics heritage) continues to push performance applications through high-profile partnerships, illustrating how co‑development can accelerate adoption in premium segments such as athletic footwear and battery components.
-
BASF’s collaboration on inflatable seat modules highlights cross‑industry product innovation: polymers used as enablers for novel user experiences rather than component commodity replacements.
-
Regional players and specialty compounders—including producers from Asia and Europe—are expanding portfolios into EV and medical applications, often through targeted product announcements that emphasize sterilization, halogen‑free flame retardancy, and elevated heat resistance.
-
Smaller custom compounders and formulators remain vital partners for OEMs seeking differentiated properties or rapid supply chain responsiveness, particularly where global majors maintain longer lead times.
What our full PW Consulting report delivers (practical chapter map)
-
Market sizing & scenarios: A transparent methodology linking historical demand (2020–2025 base) to multiple 2026–2032 forecast scenarios, stress-tested against input‑cost and demand-shift events.
-
Segment playbooks: Tactical GTM guidance for injection, extrusion and blow molding grades—covering pricing, specification thresholds, and margin archaeology. (Note: we intentionally withhold granular split tables here—see the full report for subsegment volumes and value splits.)
-
Supplier scorecards & commercial negotiation templates: Objective supplier benchmarks including capability matrices, certification footprints, and risk profiles.
-
Regulatory impact mapping: REACH and equivalent regional frameworks mapped to grades and likely reformulation timelines, with prioritized mitigation measures.
-
Cost modeling toolkit: Scenario-ready spreadsheets that roll feedstock price changes through to landed cost and suggested price‑pass strategies.
-
M&A & partnership screening: Target identification criteria and integration risk checklists tailored to both strategic acquirers and financial sponsors.
-
Technology & sustainability roadmap: Pathways for bio‑based and recycled-content TPEE variants, lifecycle-carbon estimations, and certification roadmaps.
How to use this preview in your 2026 playbook
-
Procurement: Use the macro price and availability signals to renegotiate supply contracts, add optionality clauses for feedstock swings, and prioritize qualification of alternate compounders in low-risk geographies.
-
Product management: Prioritize two lanes—(1) premium differentiated grades tied to EV/medical requirements and (2) cost-optimized formulations for higher-volume consumer/industrial parts—with clear go‑to‑market and margin targets.
-
Strategy & M&A teams: Target bolt-on acquisitions that fill critical capability gaps (e.g., medical-grade compounding, halogen‑free flame retardant expertise, or local compounding capacity) rather than broad diversification.
-
Risk & compliance: Implement forward-looking REACH compliance runs and build certification timelines into new product development roadmaps to avoid downstream launch delays.
Final note — the signal, not the full dataset
This preview synthesizes the strategic signals PW Consulting’s full TPEE market study captures: clear growth, differentiated margin pools, and a competitive landscape where technology partnerships and supply resilience will determine winners in 2026. To preserve commercial value for clients and preserve the “trailer” nature of this introduction, we have not disclosed the detailed subsegment splits, regional breakdown tables, or the full supplier scoring matrix here. The comprehensive dataset, scenario models, and executable playbooks are accessible in the full report and accompanying data room.
For teams preparing 2026 budgets, supplier negotiations, or M&A theses, the full PW Consulting Thermoplastic Polyester Elastomer (TPEE) Market study is designed as a hands-on operational tool—reach out via our report landing page to request the complete executive briefing, data appendices, and bespoke workshop options.
For detailed analysis of this topic, please visit the official page: Thermoplastic Polyester Elastomer (TPEE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


