



PW Consulting: Automotive Antenna Module Market to hit USD 6.1B by 2032, growing at 7.4% CAGR

Automotive Antenna Module Market — Strategic Outlook for 2026 Decision‑Makers
Base year: 2025. Forecast horizon: 2026–2032. Compound annual growth rate (CAGR): 7.4%.
Automotive Antenna Module Market
The automotive antenna module market is entering a second, structurally different phase of growth. After expanding from roughly USD 2.6 billion in 2020 to about USD 3.7 billion in 2025, the market is projected to continue at a mid‑single digit annual pace and exceed USD 6.1 billion by 2032 under our central scenario. This report from PW Consulting is designed as a practical playbook for executives who must turn this predictable market expansion into defensible commercial advantage in 2026.
Automotive Antenna Module Market
Why this study matters for decisions you must take in 2026
-
Procurement and supplier strategy — Connectivity functions are consolidating in modular antenna assemblies; a wrong sourcing decision in 2026 creates a multi‑year lock‑in with cascading BOM and validation costs.
Automotive Antenna Module Market -
Product planning and differentiation — Multi‑band, multi‑technology antenna modules (GNSS, cellular including 5G, V2X, Wi‑Fi, Bluetooth, satellite services) are now a floor, not a premium. How OEMs and Tier‑1s sequence features across vehicle segments determines realized ASP uplift.
-
Regulatory compliance and testing investments — New mandates and EMC/ESD test requirements mean suppliers and OEMs must budget for accredited testing and design margins; reactive fixes are costly.
-
M&A and partnership timing — The market shows modest concentration (our model estimates the top three firms control roughly one quarter of revenues and the top five around two‑fifths), leaving room for roll‑ups and vertical partnerships.
What the PW Consulting report delivers — practical contents
-
Proprietary market model (2020–2032) with scenario toggles for EV penetration, 5G rollout speed, and regulatory adoption curves. The model is delivered in a live spreadsheet to stress‑test supplier choices and product roadmaps.
-
Decision frameworks for procurement teams: supplier qualification checklist, cost‑to‑validate calculators, second‑source gating criteria and a template RFP tailored to multi‑band antenna modules.
-
Technology roadmap and interoperability matrix covering GNSS, 4/5G cellular, V2X and short‑range wireless. Includes EMI/ESD design implications derived from ISO 11452 and CISPR 25 test scenarios, and compliance pathways mapped to EU General Safety Regulation expectations.
-
Supply chain maps and risk heatmaps: raw material dependencies, test/validation bottlenecks, and high‑risk single‑source components. We identify where nearshoring or dual‑sourcing generates the fastest risk‑adjusted ROI.
-
Competitive playbooks and vendor scorecards: capability, scale, certification scope, and likely strategic moves for each major supplier to 2028 (full scorecards and score drivers available in the report appendix).
-
Commercial benchmarking tools: BOM composition templates, price elasticity scenarios, and aftermarket vs OEM revenue splits to support negotiation and pricing strategies.
Market dynamics that will shape tactical choices in 2026
-
Connectivity commoditization vs. integration premium — Antenna modules are evolving from single‑function parts to integrated, validated systems. Buyers will pay for validated integration (EMC, thermal and mechanical) but will not accept unproven, untested assemblies.
-
Electromagnetic complexity and testing burden — The rise of high‑power EV drivetrains and denser in‑car RF ecosystems increases the cost and time required for EMC/ESD validation. Compliance with ISO 11452, CISPR 25 and the EU General Safety Regulation effectively makes accredited testing an upfront procurement requirement.
-
Regulatory drivers — Mandates such as the EU eCall requirement (automatic emergency call systems with GNSS and cellular connectivity) are accelerating adoption of certified intelligent antenna modules across vehicle segments, reshaping baseline specifications.
-
Concentration and consolidation — The supplier base remains fragmented enough to permit strategic M&A and OEM‑level exclusivities, but established Tier‑1 and component firms continue to control critical customer relationships and validation capabilities.
Competitive landscape — what to watch and recommended responses
The competitive set includes large vertically integrated Tier‑1s, specialized RF component manufacturers, and regional high‑volume players. Below are concise, strategic readouts on the principal firms we track and the implications for buyers and rivals.
-
Continental AG (Hannover, Germany) — Strength: integration with vehicle architectures and multi‑band modules including 5G and V2X. Strategic thesis: Continental's scale and systems approach make it a logical partner for OEMs seeking turnkey validation. For competitors: pursue niche differentiation or lower TCO through localized validation services.
-
Denso Corporation (Kariya, Japan) — Strength: deep OEM relationships and experience across GPS, cellular and Bluetooth modules. Strategic thesis: Denso is well placed to bundle antenna modules with telematics ECUs; suppliers should expect aggressive co‑engineering offers to lock in design wins.
-
Robert Bosch GmbH (Gerlingen, Germany) — Strength: integration with ADAS and safety systems. Strategic thesis: Bosch's certification and system safety competencies make it a preferred partner for safety‑critical connectivity; rivals should emphasize faster validation cycles as a counter.
-
Harman International (Stamford, US) — Strength: global telematics certification and infotainment interfaces. Strategic thesis: Harman will remain influential in consumer‑facing connectivity; OEMs should use Harman to accelerate global homologation where needed.
-
TE Connectivity (Schaffhausen, Switzerland) — Strength: robust smart‑module manufacturing and connector technologies. Strategic thesis: TE is a strategic acquisition target for firms seeking hardened, production‑ready RF modules with strong connector IP.
-
Harada Industry (Tokyo, Japan) — Strength: very high volume deployments. Strategic thesis: Harada is a winner in cost‑sensitive mid‑volume programs; competitors must focus on value‑added integration or specialized RF performance.
-
Valeo SA (La Défense, France) — Strength: integrated communication and safety functions. Strategic thesis: Valeo's systems view aligns antenna strategy with vehicle safety roadmaps; OEMs should assess whether to consolidate supplier lists around such integrated offers.
-
Laird Connectivity (Wiltshire, UK) — Strength: high‑frequency RF specialization. Strategic thesis: Laird can win high‑performance niches (e.g., satellite radio or precision GNSS) and is a logical partner for performance differentiation.
-
Amphenol Corporation (Wallington, US) — Strength: test & measurement antennas and robust connectivity modules. Strategic thesis: Amphenol is the pragmatic choice where lab‑grade validation and testability across supplier ecosystems are priorities.
Recommended strategic moves for 2026
-
Implement a 90‑day supplier validation sprint. Prioritize partners that can demonstrate accredited EMC/ESD test passes and provide design‑for‑test artifacts to shorten homologation time.
-
Adopt a modular architecture policy. Define mandatory interface and validation layers for antenna assemblies to allow third‑party innovations without redoing full‑vehicle certification.
-
Build a regulatory compliance buffer. Allocate budget and calendar contingencies for accredited testing and document retention required under EU and international safety regulations.
-
Screen M&A targets using our concentration and supplier scorecards. Look for targets that deliver either immediate validation capabilities or portfolio depth in high‑growth subfunctions (e.g., multi‑GNSS, 5G mmWave prep).
How to use this report in practice
Leaders should treat the report as both a forecasting tool and a project playbook. Use the provided market model to stress‑test capital allocation scenarios (e.g., investing in in‑house test labs vs outsourcing validation). Deploy the procurement templates in tandem with our vendor scorecards to compress negotiation cycles and limit late‑stage non‑conformances. Finally, integrate the compliance checklist into product development gate reviews for 2026 launches.
Trailer note — what we are intentionally holding back
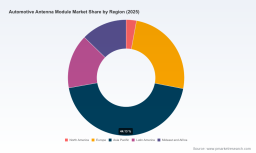
To preserve the value of the full market study and to ensure you have the actionable detail needed for procurement, product and M&A decisions, we have presented macro market evolution and strategic implications here while withholding the granular segmentation tables, regional / application percentage breakdowns, and the full vendor scoring matrices. These withheld elements are available in the full report and spreadsheet package, which contains the line‑by‑line model, vendor scorecards and validation checklists you will need to operationalize a 2026 strategy.
Next steps
Contact PW Consulting to obtain the complete Automotive Antenna Module Market report and the live model if you are preparing sourcing rounds, product roadmaps, or M&A diligence for 2026. Our team can also run a compact, bespoke stress‑test of your supplier strategy using the same model in a one‑day workshop.
For detailed analysis of this topic, please visit the official page: Automotive Antenna Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


