



LTCC Market to Reach USD 344.8M by 2032 at 5.8% CAGR — PW Consulting

LTCC Market 2026 Strategic Briefing — A PW Consulting Introductory Insight
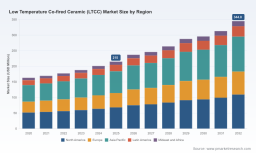
Low Temperature Co-fired Ceramic (LTCC) substrates and packages are transitioning from niche enablers into strategic building blocks for high-frequency communications, advanced automotive electronics, and next‑generation semiconductor modules. This introductory briefing outlines why our comprehensive PW Consulting LTCC Market study — anchored on a 2025 base year, a 2020–2025 historical series, and a detailed 2026–2032 forecast horizon — is essential for any executive making capital, sourcing, or product roadmap decisions in 2026. The market we model expands from roughly USD 163.2 million in 2020 to USD 215.0 million in 2025, and our baseline forecast projects a steady compound annual growth rate (CAGR) of 5.8% through 2032, culminating in a market size approaching USD 345 million by 2032. These headline figures frame a market that is growing steadily, yet is being reshaped by raw‑material pressures, regulatory shifts, and selective consolidation.
Low Temperature Co-fired Ceramic (LTCC) Market
Why this study matters for 2026 decisions
-
Timing: The next 12–18 months will determine who secures long‑lead raw materials, who localizes capacity, and who locks in strategic partnerships for 5G/6G and automotive-qualified LTCC. The 5.8% CAGR is healthy but not explosive — growth will be uneven across segments and geographies, making prioritization essential.
Low Temperature Co-fired Ceramic (LTCC) Market -
Strategic tradeoffs: Firms must weigh near‑term margin protection against longer‑term product differentiation. Decisions about in‑house manufacturing versus outsourced fabrication, material standardization, and co‑development with OEMs will materially affect margins and time‑to‑market.
Low Temperature Co-fired Ceramic (LTCC) Market -
Investment sizing: Our forecast and scenario work provide the necessary confidence intervals for CapEx and procurement commitments. Whether building a greenfield line, retrofitting existing ceramic fabs, or acquiring a specialist contract manufacturer, the report translates market growth into investment thresholds and payback profiles.
Macro drivers and near‑term shocks reshaping LTCC economics
-
Raw‑material dominance: Alumina remains the principal feedstock in LTCC formulations. Industry data show that raw alumina powder and metallization account for roughly 60% of LTCC production costs. That concentration of cost in one input creates a tight coupling between raw‑material markets and final‑product economics.
-
Supply volatility: Temporary shortages of alumina during 2024–2025 pushed unit prices materially higher — industry reports indicate price spikes up to ~20% in that period. Firms unable to hedge or qualify alternative suppliers faced margin compression or production delays.
-
Energy and regulatory delta: Sintering is energy‑intensive, and energy price differentials matter. Sintering energy costs in Europe have been measured as roughly 25% higher than in Asia‑Pacific, which combined with the EU’s Carbon Border Adjustment Mechanism (effectively imposing about USD 90 per ton CO2‑equivalent on imports) alters location economics for both raw material supply and final assembly.
-
Demand concentration and technology cycles: Growth drivers include telecommunications (5G/6G), automotive electrification and ADAS, and advanced semiconductor packaging. These end markets reward low‑loss materials, miniaturization, and high‑reliability process control — capabilities that some suppliers are already leveraging to capture premium segments.
Competitive landscape — capabilities, openings, and tactical moves
The LTCC ecosystem is a mix of materials suppliers, specialty fabricators, and integrated component manufacturers. Market concentration metrics indicate that the top three suppliers account for a majority share (CR3 ~65%), and the top five push that toward high concentration (CR5 ~82%), signaling a market where scale and specialized capability matter.
-
Vibrantz Technologies Inc. (Houston, TX) — a materials and paste supplier with a focus on low‑loss dielectrics and conductor systems. Recent technical presentations and conference activities suggest Vibrantz is positioning its L8 and A6M‑E systems as preferred options for high‑frequency multilayer substrates. For companies seeking material performance gains (loss tangent, thermal stability), Vibrantz represents an attractive partner for co‑development.
-
IMST GmbH (Kamp‑Lintfort, Germany) — a producer of LTCC modules with in‑house prototyping. IMST’s European presence and microwave/RF specialization make it well‑positioned for regional telecommunications and defense programs that prioritize proximity, qualification timelines, and small‑volume engineering runs.
-
NEOTech Inc. (Chesterfield, MO) — differentiated by custom fabrication, embedded passives and hermetic sealing. NEOTech is a contender for customers requiring high‑reliability packaging and tight electrical tolerances for high‑frequency applications.
-
Fralock Corporation (Clinton, SC) — a fabricator that works across multiple material systems (Ferro, DuPont, Heraeus) and offers secondary brazing capabilities. Fralock’s flexibility is a strategic asset for OEMs needing rapid material qualification and mixed‑technology assemblies.
-
TTM Technologies (Santa Ana, CA) — provides turnkey LTCC manufacturing compatible with major material systems. TTM is notable for scale and integration, suitable for OEMs aiming to outsource at higher volumes while retaining engineering control.
-
Murata Manufacturing, Kyocera, TDK (Japan) — these large, vertically integrated electronics players combine materials expertise with high‑volume production, portfolio breadth, and global customer reach. Recent developments — Murata’s new production building (completed April 2026) and continued product launches targeted at automotive applications — underscore the speed at which incumbents can mobilize capacity for priority markets.
Strategic implication: smaller specialists can win premium engineering programs through speed and customization, while larger incumbents will compete on scale, reliability, and bundled component offerings. Expect continued deal activity in 2026 (partnerships, tolling agreements, targeted M&A) as firms pursue capability gaps.
What the full PW Consulting LTCC report delivers — practical, executable outputs
-
Financial model: A dynamic market model (2020–2032) with scenario toggles for demand elasticity, material‑price shocks, and regulatory cost pass‑through. The model quantifies upside and downside pathways around our 5.8% CAGR baseline.
-
Supply‑chain stress tests: Cost build‑ups with raw‑material sensitivity (alumina and metallization), labor, energy, and logistics. We simulate the P&L and cash‑flow impact of up to 20% raw‑material price volatility observed in 2024–2025 and the effect of carbon‑adjusted import costs.
-
Supplier scorecards: Comparative capability matrices for materials suppliers, contract fabricators, and integrated component manufacturers — including qualification timelines, production scale, design support, and risk profiles.
-
Regulatory and energy impact analysis: Regionally differentiated plant economics that incorporate energy‑cost deltas and CBAM‑style tariffs to guide site selection and near‑term localization choices.
-
Commercial playbooks: Go‑to‑market and procurement templates for securing feedstock, setting contractual protections, and structuring long‑term supply agreements. Also included are negotiation levers for OEMs and CMs.
-
Investment cases and M&A roadmaps: Valuation contours, potential synergy capture levers, and integration checklists particular to LTCC capabilities (e.g., embedded passives, hermetic sealing, low‑loss dielectrics).
Note: This briefing intentionally avoids republishing granular segment tables or confidential supplier revenue splits. The full report contains the detailed segmentation, downloadable datasets, and supplier scorecards that power the above outputs.
Strategic imperatives for leadership teams in 2026
-
Secure feedstock through diversified suppliers and contractual hedging — given alumina’s outsized share of production cost and recent price volatility, procurement strategy is now a strategic moat.
-
Quantify and price regulatory risk into product bids — especially for companies selling into or sourcing from Europe where CBAM and higher sintering energy costs increase landed cost.
-
Prioritize low‑loss materials and co‑development for high‑frequency markets — LTCC value increasingly accrues to firms that can offer demonstrable electrical performance benefits for 5G/6G and advanced RF subsystems.
-
Right‑size capacity regionally — use our regional plant economics and energy sensitivity analyses to decide whether to localize production, toll‑manufacture, or outsource.
-
Evaluate targeted consolidation and partnership plays — CR3/CR5 concentration signals room for meaningful M&A and strategic alliances to secure volume, market access, or specialized capabilities.
-
Invest in energy efficiency and process control — reductions in sintering energy and yield improvements directly expand margin in a market where input costs dominate.
How to use this briefing and next steps
-
For strategy teams: Use the forecast scenarios and supplier benchmarks to prioritize product roadmaps and capital allocation over a 36–60 month horizon.
-
For procurement: Apply our cost‑build templates to renegotiate supplier contracts and to design hedging strategies for alumina and metallization purchases.
-
For business development and M&A teams: Leverage the supplier scorecards and investment cases as a baseline due diligence toolbox for potential transactions or JV partners.
-
Engagement options: PW Consulting can provide the full report with downloadable datasets, run a tailored sensitivity analysis for your portfolio, or facilitate supplier selection workshops based on our benchmarking framework.
Conclusion — The LTCC market sits at a crossroad of steady end‑market growth and heightened input‑ and policy‑driven risk. Our baseline projection sees the market continuing to expand from a 2025 base of roughly USD 215 million, growing at a 5.8% CAGR through 2032. The difference between winners and laggards in 2026 will be defined less by exposure to demand and more by the robustness of feedstock plans, regulatory foresight, and execution capability on materials performance. For the full segmentation, supplier profiles, downloadable models, and tactical playbooks that operationalize these insights, please consult the PW Consulting LTCC Market report on our website or reach out to request a customized executive briefing.
For detailed analysis of this topic, please visit the official page: Low Temperature Co-fired Ceramic (LTCC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


