



PW Consulting: Release Liners Market to Reach USD 26.32B by 2032 at 6.33% CAGR

Release Liners Market — Strategic Preview for 2026 Decision-Makers
As companies operationalize 2026 plans, release liners occupy an increasingly strategic position at the intersection of adhesives innovation, sustainable packaging, and regulated supply chains. PW Consulting’s Release Liners Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies the commercial trajectory and decodes the business implications: the global market is estimated at USD 17.13 Billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.33% through 2032, reaching approximately USD 26.32 Billion. For executives weighing capital allocation, supplier strategy, product development, and compliance roadmaps, the implications are immediate and actionable.
Release Liners Market
Why this study matters for 2026 strategy
-
Market momentum and clarity: the market’s multi-year, 6%-plus CAGR reflects structural drivers — adhesive-driven labeling expansion, medical and hygiene demand, and the shift toward sustainable materials — rather than cyclical blips. Understanding this baseline growth is critical for prioritizing investment versus portfolio rationalization.
Release Liners Market -
Regulatory inflection points: 2026 is not merely another planning year — several regulatory forces that materially affect material choice, recyclability and extended producer responsibility (EPR) costs are converging. Firms that integrate policy scenarios into procurement and product roadmaps will preserve margin and market access.
Release Liners Market -
Competitive configuration: while major specialty players hold meaningful positions, the market remains only moderately concentrated (CR3 ~28%, CR5 ~35%), leaving room for both focused niche plays and scale-driven consolidation. This dynamic favors disciplined M&A, targeted partnerships, and technology licensing.
What the report delivers — practical content for execution
Our full study is designed as a decision-support toolkit rather than an academic exercise. Key operational deliverables include:
-
Bottom-up market sizing and scenario models (2026–2032) calibrated to demand drivers and price dynamics — enabling quick sensitivity testing of price, substrate mix and end-market demand shocks.
-
Regulatory impact matrices that translate EU packaging rules, EUDR timelines and expanding EPR schemes into cost-per-tonne and compliance-cost scenarios for converters and brand owners.
-
Supply-chain heat maps identifying concentrated nodes for raw materials (coatings, pulp, PET film) and conversion capacity — designed to support dual-sourcing strategies and CAPEX prioritization.
-
Technology and product roadmaps comparing silicone vs non-silicone chemistries, glassine and kraft-based substrates, and emerging recyclable solutions — with break-even analytics for switching investments.
-
Go-to-market playbooks: commercialization blueprints for specialty suppliers, converters and brand owners including pricing levers, specification governance, sample-to-qualification timelines and partnership archetypes.
-
M&A and partnership teardowns: valuation benchmarks and integration risk checklists that reflect the market’s fragmentation and the economics of scale in coating and liner handling operations.
-
Operational checklists for contamination-sensitive and medical/pharma applications, including silicone migration control, surface energy optimization and traceability requirements.
Market dynamics executives must internalize
-
Raw material volatility and upstream linkages: glassine and calendared kraft grades depend on softwood pulp, which remains exposed to cyclical drivers like housing activity, exchange rates and forestry policy shifts. These inputs translate swiftly into conversion economics and inventory strategy for converters and converters’ customers.
-
Regulatory timing is non-linear: the EU Packaging and Packaging Waste Regulation (EU) 2025/40 came into force in early 2025 and is broadly applicable from August 2026. Meanwhile, the transition window for deforestation regulations (EUDR) and expanding EPR schemes create overlapping compliance horizons. Firms that adopt a “comply early” posture reduce disruption and win shelf access with sustainability-sensitive brand owners.
-
Sustainability as a product spec: recyclable-with-paper liners and novel coatings are progressing from proofs to commercial launches. The competitiveness of recyclable solutions will increasingly hinge on certified circularity claims and compatibility with existing conversion lines.
-
Fragmented but consolidating competitive landscape: the moderate concentration ratios show leading firms have strong niches but do not dominate end-to-end value chains universally — creating opportunities for scale players to consolidate converter relationships or for specialists to capture high-value niches.
Competitive landscape — profiles and strategic posture
The release liners ecosystem includes integrated paper suppliers, specialty coaters and niche technology providers. Below are strategic snapshots of industry participants whose moves matter for 2026 planning.
-
Loparex LLC (Cary, NC) — a specialty silicone-coated liner manufacturer focused on PSA applications across industrial and electronics sectors. Loparex’s value proposition centers on high-performance silicone technologies and co-development with adhesive formulators. Strategy signal: pursue deep technical partnerships with adhesive OEMs to lock in spec-in cycles.
-
Ahlstrom (Espoo, Finland) — a fiber-based specialty materials leader that has invested heavily in recyclable silicone-coated liner platforms. Its recent product launches emphasize circularity credentials. Strategy signal: vertical integration around recycled fiber supply and certification programs is core to capturing sustainability-led demand.
-
Mondi (Brussels, Belgium) — combining paper production with coating operations, Mondi is positioned to optimize cost-to-serve for labels and sustainable packaging. Strategy signal: integrated supply models reduce cost volatility exposure and accelerate qualification with brand owners focused on recyclability.
-
Tredegar Surface Protection (Richmond, VA) — differentiated by non-silicone liners for contamination-sensitive uses. Strategy signal: differentiation via chemistry allows access to regulated end-markets where silicone migration is a critical failure mode.
-
Adhesives Research, Inc. (Glen Rock, PA) — specialty manufacturer with expertise in migration control and engineered surface energy. Strategy signal: technical depth enables premium pricing in high-spec medical and electronics segments.
-
Tee Group Films (Ladd, IL) — focuses on customized liners for rubber, automotive and aerospace sealing solutions. Strategy signal: customization and engineering know-how carve defensible niches where qualification cycles justify higher margins.
Recent industry milestones shaping 2026
-
Feb 2026 — Ahlstrom launched a next-generation recyclable silicone-coated liner aimed at PSA tapes and double-sided applications, reflecting the acceleration of circular product launches.
-
Mar 2026 — AWA Global convened the Release Liner Summit, consolidating practitioner views on commercialization timelines, coating technologies and standardization needs.
-
Mar 2026 — Several suppliers, including major regional exhibitors, showcased liner innovations at Interpack 2026, highlighting the rapid commercialization pipeline for both silicone and PET-based liners.
Strategic recommendations for corporate agendas in 2026
-
Procurement: embed regulatory scenarios into procurement contracts. Include clauses for recycled content, EPR pass-throughs and alternative material approvals to avoid last-minute cost shocks.
-
R&D and Product: prioritize recyclable and low-migration chemistries for high-growth categories. Fast-track pilot lines with converters and brand owners to compress qualification cycles.
-
Supply-Chain Resilience: diversify pulp and film sourcing and create safety stocks tied to housing and currency indicators. Consider toll-coating agreements to mitigate capital intensity while securing supply.
-
Commercial: align pricing and specification governance with brand sustainability targets. Offer joint development agreements to secure long-term offtake in exchange for co-investment in certification and circular supply chains.
-
M&A and Partnerships: target tuck-in acquisitions to consolidate regional conversion footprints or acquire specialized coating chemistry IP. Joint ventures remain attractive for entering regulated end-markets with long qualification cycles.
What this preview withholds — and why it matters
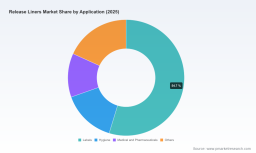
In this executive preview we have presented the high-level market trajectory, competitive dynamics and regulatory inflection points that will matter to 2026 decision-makers. To preserve the utility of the study as a decision tool and to protect commercially sensitive segmentation granularity, detailed regional/application splits, proprietary price curves and the full financial model are available only in the comprehensive report. These elements are essential for precise procurement hedging, capex sizing and M&A valuation — and they are intentionally reserved for subscribers and licensed users.
Next steps for leaders
If your 2026 plan includes new product launches, material switching, M&A exploration or compliance programs tied to EPR and EU packaging rules, this study provides the scenario models and playbooks you need to de-risk execution. PW Consulting’s full Release Liners Market report contains the segmentation matrices, downloadable model workbook and supplier scorecards required to convert the strategic themes above into executable roadmaps.
PW Consulting stands ready to brief leadership teams and run tailored scenario workshops that map our market model to your cost base and qualification timelines. For companies that must move from insight to action in 2026, the most urgent advantage will come from integrating regulatory foresight, substrate choice and supplier strategies into a single, executable plan.
For detailed analysis of this topic, please visit the official page: Release Liners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


