



PW Consulting Market Insight: Large-Volume Wearable Injectors to Reach USD 1.25B by 2032

Large Volume Wearable Injectors Market: Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on our Large Volume Wearable Injectors market study — a focused, action‑oriented synthesis designed to inform C‑suite and commercial leadership decisions in 2026. This preview surfaces the structural forces, competitive tensions, and investment levers that will determine winners and losers as the sector transitions from niche capability to mainstream delivery option for high‑volume biologics.
Large Volume Wearable Injectors Market
Why this study matters for 2026
The market has moved beyond proof‑of‑concept. After expanding from roughly USD 470 million in 2020 to about USD 655 million in 2025 (base year), the sector is poised to exceed USD 1.25 billion by 2032 under our central forecast — implying a compound annual growth rate of 9.8% across the 2026–2032 forecast window (all values in USD Million). That trajectory reflects accelerating adoption of on‑body and patch‑style platforms for subcutaneous administration of high‑volume biologics, evolving payer stances in developed markets, and scaling of manufacturing for disposable and reusable device components.
Large Volume Wearable Injectors Market
For life‑science manufacturers, device OEMs, contract manufacturers, and investors, 2026 is a hinge year: technologies are de‑risking, several commercial partnerships are crystallizing, and reimbursement pathways are maturing unevenly. Our report translates these macro signals into tactical decisions — where to invest in capacity, which product features to prioritize, how to structure value propositions for payers, and which partnering strategies de‑risk launch timelines.
Large Volume Wearable Injectors Market
What the full PW Consulting report delivers (practical, executable content)
- High‑fidelity market sizing and scenario modelling: We provide a base case anchored in the 2025 market and generate upside/downside scenarios through 2032. These models allow you to stress test launch timing, price points, and adoption curves without exposing confidential client inputs.
- Go‑to‑market playbook: Segmented strategies for device OEMs and pharma sponsors covering channel design (direct vs. distributor), key payer engagement milestones, clinical evidence sequencing, and pilot deployment templates for homecare integration.
- Regulatory and reimbursement roadmaps: Comparative timelines and decision trees for CE, FDA, and leading reimbursement authorities; recommended evidence packages and real‑world endpoints to accelerate coverage decisions.
- Manufacturing & supply chain scale-up guide: Capital expenditure sizing heuristics, partner selection criteria for CMOs, and a checklist for device‑component qualification and sterile assembly to mitigate first‑in‑market supply risk.
- Technology evaluation framework: A structured rubric to compare mechanical, electronic, and disposable tradeoffs (usability, connectivity, battery life, drug containment) aligned to clinical and commercial priorities.
- Commercial heating map: Prioritized target indications and customer segments for early revenue capture, accompanied by sample contracting terms, KPI dashboards, and win/loss lessons learned from recent product launches.
- M&A and partnership playbook: Valuation anchors, diligence checklists, and three archetypal partnership structures (co‑development, supply agreement, licensing) mapped to risk appetite and time‑to‑market objectives.
- Decision support toolkit: Excel‑based forecast models, payer value calculators, and a risk/mitigation matrix that executives can apply directly to their project portfolios.
Market dynamics shaping strategic choices
- Therapeutic and patient adoption drivers: The push to convert intravenous biologic regimens to high‑volume subcutaneous dosing, together with strong patient preference for home administration, continues to expand addressable demand. Device usability and adherence metrics are now key commercial differentiators.
- Technology clustering and capability vectors: Platforms span non‑programmable patch pumps to programmable reusable on‑body injectors and cartridge‑based systems. Roadmaps are converging on improved dose accuracy, connectivity for adherence data, and simplified reconstitution or prefilled formats.
- Commercial and payer friction: Despite momentum in developed markets, high device costs and constrained reimbursement in emerging markets remain material barriers. Our client playbook emphasizes early payer engagement and outcome‑based contracting pilots in select jurisdictions to accelerate coverage.
- Regulatory precedent lowers uncertainty: The regulatory landmark of an on‑body delivery device attaining U.S. approval for a biosimilar has decreased regulatory execution risk for new entrants and sponsors seeking subcutaneous alternatives. Still, country‑specific evidence expectations and post‑market commitments vary widely.
- Concentration and competitive speed: The market exhibits moderate concentration among incumbent platforms, with the top three players commanding a majority share and the top five increasing that share further. This dynamic favors rapid scale‑up by first movers and makes strategic alliances attractive to challenger firms seeking distribution and payer access.
Competitive landscape — who to watch (selected profiles)
Our competitive coverage focuses on capability, commercial positioning, and strategic intent rather than exhaustive transactional detail. Client engagements benefit from our vendor due‑diligence templates and a proprietary heatmap that scores companies on clinical readiness, manufacturing scale, and commercial reach.
- LTS Lohmann Therapie‑Systeme AG (Andernach, Germany): The Sorrel™ platform targets non‑programmable large‑volume wearable delivery for biologics, supporting exceptionally high single‑dose volumes. LTS’s approach emphasizes integration with biosimilars and established parenteral formulations.
- Ypsomed AG (Burgdorf, Switzerland): YpsoDose positions as a prefilled, ready‑to‑use patch injector for higher‑volume biologics. Recent product updates have reiterated availability as a 10 mL capable solution, signaling readiness for a broader commercial pipeline with reduced device‑fill complexity.
- West Pharmaceutical Services, Inc. (Exton, PA, USA): The SmartDose® 10 On‑Body Delivery System combines a battery‑powered wearable with prefillable cartridge design, targeting sponsors seeking an integrated device/pharmaceutical containment solution and a differentiated user experience.
- Enable Injections, Inc. (Cincinnati, OH, USA): The enFuse® hands‑free on‑body injector supports subcutaneous delivery up to larger volumes and has attracted strategic investor interest; recent activity underscores its push toward commercial scale and regulatory acceptance in combination with branded therapeutics.
- Gerresheimer AG (Düsseldorf, Germany): Gx SensAir delivers a programmable reusable on‑body option for multi‑mL administration, appealing to sponsors seeking dosing flexibility and potential lifecycle extension through device upgrades.
Recent market signals that matter
- Investment flows: In January 2026, a major pharma sponsor announced a material investment to accelerate manufacturing capability for a hands‑free on‑body system — an early signal that strategic pharma partners will underwrite device scale when it materially reduces time to patient.
- Regulatory and commercial milestones: CE certification of combination uses and updated manufacturer product statements in 2026 are incrementally lowering adoption friction and enabling regional launches tied to specific biologic combinations.
- Regulatory precedent: U.S. approval of an on‑body device for a biosimilar has created a template for U.S. regulatory submission strategies and catalyzed interest among biosimilar sponsors evaluating self‑administration as a commercial differentiator.
Strategic implications for 2026 — five recommended actions
- Prioritize partnership over solitary scale‑up: For most pharma sponsors, co‑development or supply partnerships with device OEMs provide the shortest path to market. Use staged agreements that align manufacturing milestones with reimbursement evidence generation.
- Invest selectively in manufacturing where it protects margin: Capital allocation should focus on sterile fill/finish interfaces and single‑use component supply rather than full vertical integration unless volume visibility exceeds defined thresholds.
- Design evidence packages for payers, not regulators alone: Early health economic modelling, adherence and patient‑reported outcome measures, and limited payer pilot studies can materially accelerate coverage conversations post‑launch.
- Differentiate on total cost of care, not just device features: Articulate how the wearable solution reduces infusion center burden, improves adherence, lowers hospitalization risk, and integrates with remote monitoring; quantify these in payer calculators supplied during negotiations.
- Adopt a modular product roadmap: Launch with a minimally viable device aligned to a lead indication, and migrate to programmable/connectivity upgrades that extend product life and create recurring revenue via services.
What the preview does not disclose — and why you need the full report
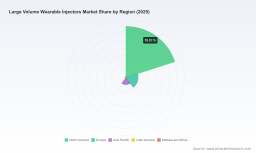
To preserve competitive value and follow the “trailer” principle, this preview intentionally omits granular regional and application‑level splits, detailed vendor market shares by segment, and proprietary transactional comparables. The full PW Consulting report contains those elements plus downloadable forecast models, sensitivity scenarios, and our recommended contracting templates. These are the inputs that translate strategic intent into executable 90‑ and 180‑day plans for teams preparing launches in 2026.
Next steps — how PW Consulting can accelerate your 2026 plan
- Custom scenario modelling using your pipeline timing, price assumptions, and partnership options.
- Vendor due‑diligence and benchmarking against our technology and commercial readiness heatmaps.
- Co‑development of payer evidence plans and commercial pilots tailored to your target geographies.
In a market growing toward USD 1.25 billion over the next decade at roughly a 9.8% CAGR (2026–2032), companies that combine smart partnerships, payer‑centric evidence strategies, and surgical manufacturing investments will capture disproportionate value. PW Consulting’s full study equips decision makers with the hard models, procurement playbooks, and competitive intelligence required to make those calls confidently in 2026.
Contact PW Consulting to access the full report, datasets, and models that underpin this strategic briefing.
For detailed analysis of this topic, please visit the official page: Large Volume Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


