



PW Consulting: Artificial Marble Market to Hit USD 29.4B by 2032 at 9.71% CAGR

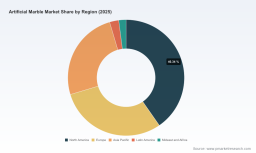
Artificial Marble Market — A 2026 Strategic Preview by PW Consulting
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our comprehensive Artificial Marble Market study — a research asset designed to inform and de-risk executive decisions throughout 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study synthesizes historical performance (2020–2025) with forward scenarios. The market has expanded meaningfully in recent years, rising from a global scale of under USD 10 Billion in 2020 to over USD 15 Billion by 2025, and our central forecast points toward roughly USD 29.4 Billion by 2032 — a compound annual growth rate of 9.71% across the projection window. These headline dynamics create a window of strategic opportunity for manufacturers, materials suppliers, private equity, and institutional buyers in 2026; this preview explains where to focus and why.
Artificial Marble Market
Why this report matters for 2026 decision-making
-
Investment calibration: Rapid compounding growth means capacity and capital decisions taken in 2026 will determine market share positions for years. Our study converts top-line growth into practical capacity-utilization, payback, and scenario-based IRR analyses tailored for manufacturing and distribution investments.
Artificial Marble Market -
Product and channel prioritization: The market’s expansion is not uniform across use-cases and product architectures. The report maps end-market elasticity and margin corridors so product managers and commercial leaders can align SKUs, pricing ladders, and channel incentives to highest-return nodes without overcommitting to low-margin segments.
Artificial Marble Market -
M&A and partnership screening: With market concentration at meaningful levels among the largest players, the study provides a repeatable M&A screening playbook — from target scoring to integration risk matrices — enabling acquirers to time deals and structure earn-outs with market-aware benchmarks.
-
Supply chain resilience: Raw material exposure, energy cost sensitivity, and manufacturing tech differences create differentiated supply risk. Our supplier-risk heatmaps and near-term disruption scenarios are built to inform procurement strategy and buffer planning for 2026 volatility.
What the report contains — practical, actionable modules
-
High-resolution market model: A three-tier model (historical run-rate calibration, baseline forecast, and two alternative scenarios) that converts macro demand growth into product-type and application-level demand curves, with sensitivity levers for pricing, construction cycle shocks, and material cost swings.
-
Cost and margin playbooks: Detailed cost stacks across common manufacturing routes (resin-based solid surfaces, engineered stone processes, cementitious systems and sintered technologies), including variable and fixed-cost breakouts, labor productivity benchmarks, and regional manufacturing cost relativities.
-
Go-to-market frameworks: Channel economics for direct distribution, dealer networks, specification sales to architects and contractors, and hospitality/healthcare procurement. Each route is paired with conversion metrics, typical sales cycle timelines, and recommended incentive structures for 2026 rollouts.
-
Supply-side diagnostic: Supplier concentration analysis, raw material sourcing maps, lead-time distributions, and a supplier performance scoring system that supports tactical supplier rationalization or strategic hedging programs.
-
Sustainability and regulatory impact assessment: Lifecycle footprint approximations, recyclability options, and compliance risk matrices tied to emerging hospital and commercial hygiene standards that influence specification choices.
-
M&A and capex tools: Deal valuation templates, accretion/dilution simulations, prioritized checklist for integration, and a CapEx sizing guide aligned to projected demand curves so teams can evaluate brownfield vs greenfield strategies.
-
Commercial annexes: Case studies, procurement RFP templates for large institutional buyers, and evidence-based spec decks for architects and facilities managers to accelerate adoption in high-value verticals.
Competitive landscape — what to watch in 2026
The sector exhibits meaningful clustering among established global incumbents and numerous regional specialists. The market’s three- and five-firm concentration ratios indicate that leading players capture a substantial share of industry revenue, creating both defensive pressures and consolidation opportunities.
-
Corian (Buffalo, New York) — Corian continues to play the premium solid-surface card with an emphasis on durability and hygiene, particularly in commercial and medical installations. Its May 2026 catalog refresh — expanding color options and emphasizing locally manufactured sheet formats — is a clear signal of inventory and specification push across institutional channels. For rivals, the lesson is clear: invest in specification-grade product attributes and contractor enablement.
-
Caesarstone (Israel) — Positioned around engineered quartz and high-hardness cultured stone slabs, Caesarstone’s strengths are in premium architectural applications. Competitive pressure will come through price-performance alternatives and from players reducing total installed cost via modularization and faster installation methods.
-
LG Hausys and Lotte Advanced Materials (South Korea) — Both bring advanced resin and engineered stone formulations to market, emphasizing repairability and heat resistance for commercial fit-outs. Their R&D and vertical integration capabilities create a technology moat; market entrants must match product durability or disrupt on cost or service speed.
-
Regional specialists (e.g., Shower Walls, Marblecraft, Patrician Marble, International Marble, The Marble Factory) — These firms dominate particular niches such as hospitality, student housing, and localized contracting markets. Their agility and bespoke capabilities make them attractive partners for larger brands seeking local penetration without heavy capex.
-
Adjacent entrants and product innovations — New product catalog releases from firms like Dekton/Grupo ONA, and supplier ranking updates from market platforms, are accelerating buyer awareness and shifting specification preferences. Expect ongoing product proliferation in 2026 as incumbents and niche providers jockey for spec authority.
Key strategic implications and prioritized plays for 2026
-
Prioritize specification wins in long-lead institutional channels: Healthcare and commercial fit-outs offer durable specification economics. Invest in clinical trials, hygiene certifications, and specification sales resources to lock contract pipelines.
-
Right-size capacity with staged investments: Use our scenario-driven capex templates to avoid overcapacity in low-margin segments while maintaining ramp-up optionality for high-growth product lines.
-
Partner with regional specialists for speed to market: Where local installation capability and bespoke finishes matter, pragmatic partnerships or minority investments can unlock distribution without full greenfield commitment.
-
Differentiate on service and total installed cost: With product features converging, companies that optimize logistics, pre-fabrication, and installation will capture superior margins.
-
Make sustainability an end-to-end value proposition: Recycled feedstocks, lower-energy production routes, and transparent LCA claims are increasingly required by specifiers and large buyers — prepare to operationalize these by 2026 to avoid specification risk.
-
Consider targeted consolidation: The market concentration metrics suggest room for accretive M&A in 2026. Buyers should prioritize targets that add distribution reach, proprietary formulations, or fabrication synergies rather than headline revenue alone.
How to use PW Consulting’s dataset and tools
-
Interactive model: Use the scenario toggles to test price shocks, construction cycle slowdowns, and raw-material inflation; the model outputs region-agnostic demand pivots and product-level capacity needs.
-
Benchmarks: Downloadable cost stacks and margin benchmarks allow rapid peer comparison for diligence and commercial planning (note: detailed segment tables and company-level splits are available only in the full report appendix).
-
M&A playbooks and checklists: Ready-to-deploy templates for target screening and integration prioritization help private equity and corporate M&A teams accelerate deal timelines in 2026.
-
Procurement heatmaps: Supplier risk scoring and alternative-sourcing pathways to operationalize supply chain resilience in the short-run.
In summary, 2026 represents a pivotal year — one where the choices around capacity, product differentiation, channel strategy, and corporate portfolio design will compound into long-term market positions. The market’s strong compound annual growth rate and expanding overall scale create both an upside for nimble players and heightened risk for those who misallocate capital. PW Consulting’s full Artificial Marble Market study translates these macro signals into immediate, executable plays: detailed forecasts, cost/margin diagnostics, and commercial frameworks designed to support confident decisions in 2026 and beyond.
For access to the full datasets, segment-level forecasts, and the proprietary M&A and CapEx tools referenced above, please consult the report landing page where the complete appendices and interactive models are hosted.
For detailed analysis of this topic, please visit the official page: Artificial Marble Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


