



PW Consulting: Prostate Cancer Diagnostics Market to Reach USD 5.4B by 2032 at 8.2% CAGR

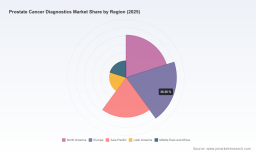
Prostate Cancer Diagnostics Market 2026: Strategic Imperatives for Decision‑Makers
As PW Consulting’s senior strategy team, we present a concise, market‑shaping perspective to guide corporate decision‑making in 2026. Our new Prostate Cancer Diagnostics Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes clinical, commercial, regulatory and reimbursement developments that will determine winners and losers over the coming investment cycle. At a macro level, the market is expanding rapidly — growing at a projected CAGR of 8.2% — and our modeled topline rises from a 2025 base to a materially larger market by 2032 (USD denominated, revenues expressed in Millions). This briefing highlights the strategic value of the full report while intentionally withholding granular segment and regional tables to encourage direct engagement with the source dossier for actionable line‑item intelligence.
Prostate Cancer Diagnostics Market
Why 2026 Is a Pivotal Year for Prostate Diagnostics
-
Regulatory momentum and new CPT coding are changing adoption economics. A sequence of regulatory clearances and approvals between 2023–2026 — across AI pathology tools, imaging navigation systems, and companion diagnostics — has compressed the time from innovation to clinical implementation.
Prostate Cancer Diagnostics Market -
Payer architecture and coding modernization are realigning reimbursement flows. Specific molecular and isoform assays now carry distinct CPT identifiers, and the 2026 CPT codebook introduced new procedure codes to support image‑guided and fusion biopsies. These coding milestones materially affect hospital and lab purchasing decisions.
Prostate Cancer Diagnostics Market -
Clinical practice is shifting toward multiparametric workflows that combine blood/urine biomarkers, advanced imaging, and molecular classifiers to reduce unnecessary biopsies and enable treatment‑decision enrichment. This composable diagnostic pathway creates both integration opportunities and competitive threats.
Market Trajectory — A Data‑Anchored Snapshot
PW Consulting’s model integrates epidemiology, utilization trends, technology adoption curves and reimbursement pathways to produce a quantified outlook. From our 2025 base, the market continues to accelerate into 2026 and beyond, reflecting sustained investment in non‑invasive assays, multiparametric imaging, and genomic classifiers. The market’s overall escalation — driven by higher utilization per patient, migration toward higher‑value tests, and widening adoption in clinical pathways — underscores why 2026 is a year to commit resources to diagnostics innovation rather than defer.
Key Dynamics Shaping 2026 Decisions
-
Technology convergence: Imaging (mpMRI, PSMA PET/CT) and liquid/tissue molecular diagnostics are rapidly moving from parallel offerings to orchestrated diagnostic algorithms. Vendors that can position their products as integrable modules into clinical workflows — or as defensible nodes in diagnostic decision trees — will command premium valuation multiples.
-
Regulatory acceleration: Several industry milestones in 2024–2026 recalibrated the regulatory baseline. Notable approvals include AI pathology tools cleared to assist pathologists and companion diagnostic approvals that expand theranostic pathways in metastatic disease. These create new commercial adjacencies and expand addressable markets for companies with regulatory expertise.
-
Reimbursement complexity: The assignment of discrete CPT codes to specific assays and the emergence of image‑guided biopsy codes alter unit economics. Developers must prioritize coding strategies and early payer engagements — clinical utility dossiers are no longer optional for scale.
-
Competitive concentration: The market exhibits moderate concentration — a small coalition of established molecular and imaging incumbents exert significant influence, while a broader long tail of innovators competes on niche performance claims. This structure favors both consolidation plays and focused niche strategies.
-
Clinical evidence hunger: Payers and guideline committees demand prospective, real‑world performance evidence that demonstrates patient‑level outcomes such as reduced unnecessary biopsies, improved risk stratification, or therapy selection impact. Evidence generation is the gating factor for both reimbursement and hospital adoption in 2026.
Competitive Landscape — Who to Watch and Why
Our competitive analysis focuses on clinical differentiators, regulatory milestones, commercialization reach and M&A activity that matter to 2026 planning.
-
Cleveland Diagnostics, Inc. (Cleveland, Ohio) — The company’s IsoPSA assay has moved from promise to commercialization following FDA PMA approval of an IVD kit in late 2025. IsoPSA’s positioning as a blood‑based isoform‑specific PSA analysis tool makes it a direct challenger in primary screening and biopsy‑avoidance workflows. Strategy implications: competitors must evaluate head‑to‑head evidence, payer positioning, and laboratory implementation logistics.
-
OPKO Health, Inc. (Miami, Florida) — The 4Kscore continues to be a leading blood‑based multianalyte risk test prior to biopsy. Its established clinical adoption and provider familiarity create a durable installed base, but growth depends on demonstrating comparative effectiveness against newer isoform and genomic assays.
-
MDxHealth SA (Irvine, California) — MDxHealth sharpened its market footprint by acquiring the ExoDx Prostate business in 2025, consolidating urine‑based molecular testing capabilities. This acquisition illustrates a broader trend: strategic M&A to assemble end‑to‑end solutions across sample types and to scale commercial operations for payer contracting.
-
Veracyte, Inc. (South San Francisco, California) — Veracyte’s Decipher genomic classifier remains central to post‑biopsy risk stratification and therapy selection. The value proposition is clear for urologists and oncologists seeking prognostic granularity to guide adjuvant therapy and active surveillance.
-
Adjacent technology plays — Philips (image guidance), Ibex Medical Analytics (AI pathology) and Foundation Medicine (companion diagnostics) — represent expansion vectors that will influence diagnostic pathways. Notable regulatory and product milestones across 2024–2026 (e.g., AI clearance, imaging navigation clearance, companion diagnostic approvals) are changing how pathology, imaging and genomics integrate into therapeutic decisions.
Selected Recent Developments That Matter for 2026 Strategy
-
Regulatory and approvals: The FDA’s clearance/approval of AI pathology solutions and additional companion diagnostics in 2025–2026 increases the clinical reliance on digital and genomic tools; companion diagnostic approvals for targeted prostate therapies broaden diagnostic demand downstream.
-
Commercial consolidation: MDxHealth’s acquisition of ExoDx assets indicates a market shift toward portfolio aggregation to secure payer contracts and to present bundled clinical pathways.
-
Coding and reimbursement: Certain high‑profile assays have been assigned distinct CPT codes (examples include unique identifiers for isoform and exosome assays), and updated biopsy procedure codes in the 2026 CPT book support the economics of image‑guided approaches. These coding events materially influence pricing strategy and hospital uptake.
What the Full PW Consulting Report Delivers (Practical Contents)
-
Market sizing & forecasting methodology rooted in epidemiology, clinical adoption curves and reimbursement trajectories (base 2025; forecast 2026–2032).
-
Clinical pathway maps that show decision nodes where diagnostics shift management (screening, pre‑biopsy risk stratification, post‑biopsy genomic prognosis, therapy selection).
-
Reimbursement playbook: CPT mapping, payer policy scan, value‑dossier templates, and price‑sensitivity analyses for key markets.
-
Competitive intelligence module: company profiles, product positioning, pipeline assessment, M&A scenarios and commercial capability scoring.
-
Go‑to‑market playbooks by end‑user (hospital urology departments, oncology reference laboratories, diagnostic imaging centers, urology clinics, academic/ research institutes), including sales resource models and partnership options.
-
Scenario analyses and stress tests: uptake under alternative reimbursement regimes, impact of rapid AI adoption, and downside cases reflecting slower guideline integration.
-
Actionable recommendations for R&D prioritization, evidence generation sequencing, and inorganic strategies to accelerate scale.
Strategic Recommendations for 2026 Deployments
-
Prioritize evidence that maps to payer value levers. Sponsor prospective studies that quantify downstream cost‑avoidance (e.g., fewer unnecessary biopsies, reduced diagnostic delays) and patient‑level outcomes; this is the fastest route to favorable coverage decisions.
-
Lock in coding and pricing early. Where discrete CPT identifiers exist, secure reimbursement narratives and pricing models that capture the assay’s clinical and operational value.
-
Build integrative partnerships. Consider alliances with imaging vendors, pathology AI providers, or established reference laboratories to create bundled diagnostic pathways that simplify hospital procurement.
-
Differentiate through workflow integration. Products that are easy to order, interpret and operationalize (turnaround time, sample logistics, reporting clarity) win in hospital and outpatient settings.
-
Plan M&A or licensing defensively. With moderate market concentration, opportunistic acquisitions (bolt‑on assays, distribution networks, or digital platforms) accelerate scale and improve contract leverage with payers.
Conclusion — The Strategic Value of the Full Report
For executives deciding capital allocation, portfolio prioritization, or M&A activity in 2026, the PW Consulting Prostate Cancer Diagnostics Market report translates market momentum into executable choices. Our analysis quantifies the market’s growth trajectory, interprets how regulatory and coding shifts reshape economics, profiles competitive moves that matter, and delivers practical playbooks to create durable commercial advantage. This overview demonstrates our analytic depth while preserving the granular segment and regional tables, company revenue splits, and model assumptions for the full publication. Accessing the complete report is the most efficient way to obtain the line‑level intelligence you will need to finalize 2026 strategic plans.
To obtain the full dataset, competitive scorecards, and the operational playbooks referenced here, please visit the PW Consulting report page for the Prostate Cancer Diagnostics Market.
For detailed analysis of this topic, please visit the official page: Prostate Cancer Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


