



PW Consulting: Superalloy Market Set for 6.5% CAGR Through 2032

Superalloy Market: Strategic Imperatives for 2026 — PW Consulting Briefing
As aerospace programs ramp toward next‑generation propulsion, power‑generation operators push efficiency thresholds, and additive manufacturing (AM) becomes standard for critical hot‑section components, the superalloy sector has entered a phase where strategic choices made in 2026 will disproportionately determine market leadership through the next planning cycle. Our Superalloy Market study — anchored on a 2025 base year with a historical window covering 2020–2025 and a forward projection through 2026–2032 — offers executives a decision‑grade synthesis of market trajectories, supplier dynamics, raw‑material risk, and technology inflection points.
Superalloy Market
Market snapshot (what the headline numbers mean)
-
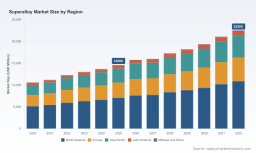
Macro growth: The global superalloy market expanded from approximately USD 10.6 billion in 2020 to USD 14.6 billion in 2025, and is modeled to reach roughly USD 22.5 billion by 2032. The forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of 6.5%.
Superalloy Market -
Concentration and structure: The market remains moderately fragmented — our competitive concentration metrics show that the top three and top five firms collectively control a meaningful but not dominant share, leaving substantial room for specialist players and regional champions to scale.
Superalloy Market -
Why the numbers matter: At a 6.5% CAGR, incremental demand and price movements translate into material shifts in EBIT for both upstream alloy producers and downstream component manufacturers. This trajectory underscores why 2026 is a pivotal planning year for capacity, sourcing, and innovation investments.
Why this study is essential for C‑suite decisioning in 2026
-
Strategic timing: 2026 is when near‑term program awards, capital budgets, and multi‑year supply agreements signed pre‑2025 begin to re‑rate. Firms that align capacity and product roadmaps now will capture disproportionately higher margin pools through 2028–2030.
-
Risk crystallization: Raw‑material volatility and new export controls that emerged in 2024–2025 introduce discrete supply‑risk scenarios. The right mix of hedging, vertical integration, and sourcing diversification reduces project execution risk and protects margins.
-
Technology arbitrage: Additive manufacturing and powder metallurgy are shifting value toward alloy formulators and powder suppliers. Firms investing in AM‑compatible chemistries and qualification playbooks will shorten time‑to‑revenue in aerospace and high‑value industrial segments.
What the PW Consulting report delivers (practical, executable outputs)
-
Decision frameworks: Portfolio prioritization matrices that map product lines against technological defensibility, margin potential, and supplier exposure to raw‑material shocks.
-
Demand scenarios and volume ramps: Three demand trajectories (conservative, baseline, and accelerated) tied to macroeconomic, regulatory, and programmatic milestones that inform capacity planning and inventory strategies.
-
Supply‑chain heatmap: A layered view of input risk — from nickel and cobalt pricing cycles to geographic concentration of melt and forging capacity — with playbooks for rapid mitigation.
-
Technology and route‑to‑market playbooks: Practical guidance for integrating AM powders, vacuum melting, investment casting, and post‑processing capabilities into existing manufacturing footprints.
-
M&A and capex pipeline: Target profiles (technology, geography, scale) and valuation benchmarks for bolt‑on acquisitions, joint ventures, and greenfield expansions, plus a prioritized list of capability gaps buyers should close in 2026–2028.
-
Commercial tools: Negotiation levers for long‑term offtake, index‑linked pricing clauses, and contract templates that align incentives across the value chain.
Macro and raw‑material dynamics shaping 2026 strategies
-
Nickel: Recent cycles showed softening in average nickel prices into 2025, driven by inventory and production moves. Increased mine production and higher refined output in key producing countries altered sellers’ pricing power and opened short‑term cost breathing room for alloy makers. For planners, the implication is twofold: (1) windows for cost‑competitive sourcing may appear intermittently and should be leveraged for long‑lead orders; (2) long‑term hedging strategies must balance price volatility with potential supply disruptions.
-
Cobalt: The sector experienced structural oversupply through 2024 and early 2025, followed by abrupt policy shocks. Government measures in producing countries created episodic export constraints that produced sharp price swings — a reminder that commodity exposure is as much a geopolitical risk as a market one. Scenario planning should include quota and export‑control cases that materially affect cobalt‑intensive grades.
-
Recycling and secondary supply: Increasingly attractive economics for reclaiming high‑value nickel and cobalt from end‑of‑life components and process scrap offer both mitigation and margin opportunities. Investments in closed‑loop recovery should be evaluated against the cost of primary metal exposure and anticipated regulatory developments.
Competitive landscape: capabilities that matter in 2026
-
Incumbent producers that combine metallurgy, semi‑finished production, and component manufacturing retain advantages in qualification speed and program integration. Firms with proven aerospace pedigrees and established qualification records continue to command premium access to blue‑chip programs.
-
Specialists focused on powders, AM readiness, and high‑temperature alloys are increasingly pivotal. Recent developments — capacity expansions in additive manufacturing and new powder introductions — are shifting where technical differentiation accrues along the value chain.
-
Notable recent moves: several tier‑one firms commissioned new AM and vacuum melting lines in 2024–2025; independent technology players launched commercial nickel‑based powders and advanced machining methods for tough alloys. Such actions compress qualification cycles and lower time‑to‑adoption for new alloys.
-
Market concentration metrics indicate meaningful headroom for consolidation and vertical integration: incumbents can pursue targeted acquisitions to plug technological gaps, while nimble specialists can scale through strategic partnerships with OEMs and AM platforms.
Five strategic imperatives for executives in 2026
-
1) Convert short‑term price relief into strategic advantage. Use transient nickel price softness to secure multi‑year supply agreements and to stabilize input costs for longer program lifecycles.
-
2) Diversify cobalt exposure. Pursue alloy substitution where performance allows, invest in recycling, and build supplier redundancy to manage policy shocks from producing countries.
-
3) Accelerate AM‑capability adoption. Prioritize investments in powder qualification, component design for additive workflows, and supply‑chain partnerships that reduce certification timelines.
-
4) Right‑size capacity with staged expansion. Favor modular, flexible capital that can be scaled in response to validated orders and evolving technology standards rather than large, single‑phase greenfield investments.
-
5) Adopt contract structures that align incentives. Index‑linked pricing, volume‑commitment floors with flexibility clauses, and collaborative R&D milestones help stabilize supplier economics and accelerate co‑development.
M&A and investment outlook
-
Consolidation will be selective and capability‑led. Expect deals that deliver either critical process technology (powder atomization, VIM/VAR melting) or specialized manufacturing (investment casting, precision forgings for hot sections), rather than scale only.
-
Private equity interest will focus on platform plays that combine technical IP with recurring revenue streams — for example, powder supply contracts tied to long‑term AM programs.
-
Deal diligence must stress raw‑material exposure, patent strength, qualification backlog, and customer concentration. Regulatory and export‑control risk are non‑trivial and should be stress‑tested in valuation models.
What we intentionally withhold here — and why you need the full report
-
We have deliberately omitted granular segment‑level revenue splits, regional and application percentages, and individual product price trajectories from this briefing. Those sub‑segment figures are core competitive intelligence and are included only in the full report, where they are presented alongside confidential supplier scorecards and a quantitative risk model.
-
If your team needs roll‑up tables that translate segmental demand into material flows, supply commitments, and EBITDA sensitivity by scenario, the complete dataset and interactive models in our full study are the only place you will find them.
Next steps for senior leaders
-
Use 2026 to convert optionality into positions: secure strategic long‑term supply where it matters, fast‑track AM qualification on prioritized platforms, and pursue targeted capability acquisitions where you lack defensibility.
-
Engage our practice for a tailored session: we will map the full report’s scenario outputs to your product portfolio, quantify margin impact across procurement and technology levers, and build a prioritised implementation roadmap for 2026–2028.
PW Consulting’s Superalloy Market study translates headline growth and technology trends into executable commercial and technical strategies. For teams preparing 2026 budgets, supply agreements, or acquisition roadmaps, the work you do now will determine your competitive position for the remainder of the decade. Contact PW Consulting to access the full report, interactive models, and bespoke advisory support.
For detailed analysis of this topic, please visit the official page: Superalloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


