



PW Consulting: Rotary Friction Welding Market to Expand at 4.75% CAGR Through 2032

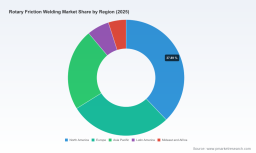
Rotary Friction Welding Market: Strategic Preview for 2026 Decision-Makers
As manufacturing leaders recalibrate capital plans and product roadmaps for 2026, rotary friction welding has moved from a niche joining technology into a strategic lever for cost, quality and sustainability across mobility, aerospace, and industrial sectors. PW Consulting’s latest Rotary Friction Welding Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers the empirical backbone executives need to translate market momentum into defensible investments. This preview outlines the study’s strategic value, highlights what corporate leaders must know today, and explains how the full report converts those insights into operational initiatives — while intentionally reserving the granular segmentation tables for the full release.
Rotary Friction Welding Market
Market Snapshot: Trajectory and Structural Signals
Our topline sizing reconciles company filings, equipment shipment data, contract-welding volumes and primary buyer surveys. The global market expanded from roughly USD 195 million (revenue, Million USD) in 2020 to approximately USD 240 million in 2025, reflecting steady adoption of solid-state joining solutions in drivetrain, e‑mobility and high-integrity assemblies. Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of 4.75% across the 2026–2032 forecast window, reaching the vicinity of USD 329.5 million by 2032. That growth path is non-linear: early forecast years show continued consolidation of incumbent applications, while mid-horizon years reflect accelerated abstraction from fusion welding in e-mobility and aerospace structural joins.
Rotary Friction Welding Market
Concentration metrics underline an industry that is neither atomized nor monopolistic: the top three suppliers command a plurality of market revenue, while the top five amplify that share further — a structure that favors scale players with integrated machine-and-service offerings but still leaves room for specialized contract welders and high-touch OEM partnerships.
Rotary Friction Welding Market
Why 2026 Is a Strategic Inflection Point
- Production vs. Prototype inflection: OEMs entering series production for electric powertrains and next‑gen transmissions require repeatable, low-variance joints. Rotary friction welding’s ability to deliver high-strength, low-porosity interfaces at cycle times favorable to automation places the technology on many 2026 procurement shortlists.
- Energy and regulatory tailwinds: Energy-efficiency mandates and lifecycle carbon accounting create preference for solid-state welding where lower process energy and reduced post-processing translate into both compliance and TCO benefits.
- Cost and labor dynamics: Persistent labor shortages and the need to shorten takt time favor machines that reduce operator intervention. Compact rotary friction systems (price ranges typically observed in the market) are becoming viable CAPEX choices for Tier‑1 suppliers and large OEM sub-assemblies.
- Commercial concentration and M&A windows: The market’s concentration profile points to attractive inorganic opportunities for companies seeking vertical control (machine + contract welding + after sales) as well as bolt‑on plays for regional contract welders with OEM relationships.
Key Demand Drivers and Risks
- Drivers
- Shift to aluminum and high-strength steel alloys in drivetrain and chassis components increases the addressable market for rotary friction welding.
- Electrification drives need for high-integrity joins in motor shafts, hubs and rotor assemblies where solid-state joining reduces thermal distortion.
- OEMs’ focus on traceability elevates suppliers that offer certified process control routes and digital quality records.
- Risks
- Raw material price volatility influences OEM make-vs-buy calculus and can squeeze margins in contract welding agreements.
- Regulatory and certification hurdles — ISO 9001:2015 compliance and downstream aerospace/defense approvals — lengthen qualification timelines for new suppliers.
- Technology substitution and internalization: major OEMs could elect to internalize friction welding capabilities, altering service-market volume.
Competitive Landscape: Players, Positioning and Recent Movements
The competitive environment blends global OEM machine builders, specialized inertia-tech providers, and vertically integrated contract welders. PW Consulting’s study profiles the strategic playbooks of the market’s core participants and their most relevant recent moves:
- Manufacturing Technology, Inc. (MTI) — A U.S.-based incumbent with a multi-modal machine portfolio (direct-drive, inertia, hybrid and low-force systems) and contract-welding capabilities. MTI’s integrated offering is attractive to OEMs seeking single-vendor responsibility for machine supply and qualification.
- American Friction Welding — North America’s largest subcontract rotary friction welder, noted for dissimilar metal assemblies and high-precision turnkey services. Their position underscores the resilience of the contract welding model for OEMs that prefer outsourcing high-complexity joins rather than capital investment.
- KUKA (including Thompson brand) — A global leader in automated friction welding, with strong penetration in automotive and aerospace. Public demonstrations of hybrid rotary friction welding technologies at trade exhibitions signal KUKA’s intent to capture e‑mobility and high‑volume automotive segments.
- Inertia Friction Welding, Inc. — Specializes in inertia-based technology and complete production lines, focused on high-force industrial manufacturing applications where inertia methods remain superior for certain large-diameter joins.
- Friction Welding Technologies Pvt. Ltd. (MTI Group affiliate) — India-based manufacturer operating on both machine supply and contract services, fitting a faster-adoption profile in cost-sensitive regional markets.
Recent industry developments — from KUKA’s product showcases to WRM’s notable machine export and multiple dedicated friction-welding sessions at TWI and IFWC events in 2026 — confirm accelerating commercialization and ecosystem activity. These events drive both technological diffusion and buyer education, shortening the adoption curve for validated use cases.
What the PW Consulting Report Delivers (Practical, Execution-Oriented)
The full report is structured specifically for boardroom and plant-floor action. Key deliverables include:
- Transparent market-sizing and a reconciled growth model (2020–2025 history; 2026–2032 forecast) with scenario variants aligned to e‑mobility and aerospace program ramps.
- Commercial playbooks for OEMs, Tier suppliers and contract welders: go-to-market priorities, pricing levers, and service models that defend margin during scale-up.
- Machine-and-process selection matrix that maps joining approach (inertia, direct-drive, hybrid) to production constraints, cost-to-serve, and qualification timelines.
- CapEx and ROI templates for greenfield and brownfield adoption, including energy-consumption sensitivity and break-even analysis informed by real-world machine pricing ranges and cycle-time benchmarks.
- Supplier shortlists and diligence checklists (technical, quality, commercial), plus an M&A screening framework tied to concentration metrics and capability gaps.
- Case studies and plant-level diagnostic tools enabling rapid pilot-to-scale decisions, including recommended KPIs for quality, throughput and lifecycle cost.
To preserve competitive value, the article above intentionally omits granular regional and application-level splits; these are enumerated and fully modeled in the deliverable so clients can run what-if scenarios against their company-specific production volume ramps.
How Executives Should Use This Research in 2026
- Prioritize investment: Use the report’s ROI templates to compare compact direct-drive units versus higher-throughput inertia or hybrid systems under your product mix and labor constraints.
- Qualification roadmap: Align certification requirements (e.g., ISO 9001:2015 and industry-specific approvals) with supplier selection and negotiate phased performance milestones into purchase and service agreements.
- Outsource vs. Insource decision-making: The report’s contract-welder scoring and cost-of-ownership modules let procurement teams quantify when to outsource complex joins versus building in-house capability.
- M&A and partnerships: Apply the market concentration and capability gap analysis to identify bolt-on targets that provide immediate access to qualified volumes, regional footprints, or proprietary process know-how.
- Service and aftermarket strategy: Build spares, predictive-maintenance contracts, and digital traceability into machine procurements to create recurring revenue and lock-in with OEMs.
Closing: Why This Report Matters for Your 2026 Playbook
Rotary friction welding is no longer an experimental niche — it is a phase-shifting production technology that reduces part rework, improves energy efficiency and shortens qualification cycles for modern metallic assemblies. For strategic leaders planning 2026 capital and sourcing decisions, the choice is not whether to engage with friction welding, but how and when to do so to secure competitive advantage. PW Consulting’s Rotary Friction Welding Market report provides the empirical, commercial and operational scaffolding to move from exploratory pilots to profitable scale without exposing your organization to unnecessary qualification or market risk.
For boards and operating committees, the report converts market growth signals (historical sizing through 2025 and a forecasted 4.75% CAGR to 2032) into actionable pathways: prioritized machine selection, supplier diligence, CapEx phasing, and M&A targeting. For procurement and plant leaders, it provides the tactical tools to implement and validate program-level returns.
Next Steps
To access the complete segmentation tables, supplier scorecards, CapEx models and the full scenario-based forecast that underpin these strategic recommendations, request the full PW Consulting Rotary Friction Welding Market report. The full intelligence package is designed so your team can run bespoke sensitivity analyses and convert the market’s momentum into measurable value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Rotary Friction Welding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


