



PW Consulting: Plastic Recycling Market Poised for 8.2% CAGR

Plastic Recycling Market — 2026 Strategic Brief
As plastic value chains confront simultaneous pressure from regulation, corporate sustainability targets, and volatile feedstock economics, corporate leaders must answer one question before committing capital in 2026: where, how fast, and to what degree will recycled plastics become a reliable commercial feedstock and profit pool? This briefing, prepared by PW Consulting’s senior strategy team, frames the answer and explains why our full Plastic Recycling Market study is essential for any executive making investment, sourcing, or M&A decisions this year.
Plastic Recycling Market
Executive snapshot
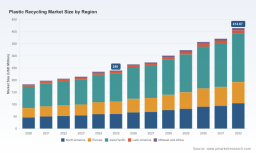
Across the historical window (2020–2025) the global plastic recycling market expanded steadily, rising from an estimated USD 183.0 Million in 2020 to USD 240.0 Million in the base year 2025. Our forecast (2026–2032) assumes a compounded annual growth rate of 8.2%, driving the market toward roughly USD 415 Million by 2032 under the base-case scenario. These headline dynamics are driven by accelerating regulatory mandates, growing OEM and brand demand for PCR content, and improving recycling technology economics — but the pace and winners differ sharply by technology, product grade, and feedstock pathway. This brief highlights the strategic vectors that matter for 2026 decisions while withholding detailed subsegment breakouts reserved for the full report.
Plastic Recycling Market
Why the 2026 decision window is pivotal
- Regulatory inflection points: 2025–26 saw a concentrated set of policy moves—national strategies, implementing acts, and labelling fixes—that materially change end‑of‑waste definitions and recycled content rules. These rules are shortening the timeline for minimum recycled-content obligations and changing compliance cost profiles for packaging-heavy sectors.
- Capacity and infrastructure visibility: Public data releases in 2025–26 improved transparency on facility locations and theoretical processing capacity. Where previously capacity was opaque, buyers and investors can now model realistic feedstock flows and identify choke points in sorting and bale quality.
- Feedstock economics are re‑anchoring supply choices: Recycled resin and bale price movements, combined with volatility in virgin polymer costs, mean procurement contracts, offtake agreements, and hedging approaches negotiated in 2026 will set margin trajectories for the next business cycle.
What the market numbers imply — strategic takeaways
The market’s movement from USD 240.0 Million in 2025 toward a projected USD 414.67 Million by 2032 at an 8.2% CAGR signals opportunity, but it also signals differentiation. A near-doubling of overall market value does not translate into uniformly distributed returns. Our granular models show outcomes concentrated where firms can reliably: (a) secure stable feedstock quality, (b) achieve food-grade or specification-compliant outputs, (c) scale sorting and preprocessing cost‑efficiently, and (d) capture premium offtake from brand owners seeking certified PCR. The market concentration metrics (CR3 ≈ 26.5%; CR5 ≈ 29.8%) underline a fragmented supplier base — implying local and regional advantages for well‑capitalized operators, and room for consolidation for strategic acquirers.
Plastic Recycling Market
Competitive landscape — who matters and why
The market comprises specialist recyclers, waste management platforms with integrated sorting networks, converters pursuing bottle‑to‑bottle capability, and regional players focused on particular waste streams. Representative companies we analyze in depth include:
- KW Plastics Inc. (St. Paul, Minnesota) — a major processor of post‑consumer HDPE into rigid containers and certified PCR pellets; a useful bellwether of HDPE feedstock-to‑food‑grade conversion economics. ( https://www.kwplastics.com)
- Plastipak Holdings, Inc. — notable for bottle‑to‑bottle PET recycling and production of food‑grade rPET; strategic partnerships with brands are central to its model.
- CarbonLite Industries LLC and Envision Plastics LLC — examples of firms focused on producing higher‑quality recycled PET and rPET streams targeting packaging customers.
- Veolia and Biffa — global/regional waste management players offering scale in sorting and feedstock logistics, often partnering or competing with specialist recyclers. ( https://www.veolia.com; https://www.biffa.co.uk)
- Regional processors and innovators — from thermoform processors in North America to pelletizers in the UK and India — that highlight the market’s operational diversity and localization dynamics.
Our competitive analysis maps these firms across capability axes (feedstock sourcing, technology readiness, food‑grade certification, downstream offtake relationships, and balance‑sheet strength) and scores likely strategic moves for 2026: capacity expansion, bolt‑on acquisitions to add feedstock capture, long‑term offtake contracts with CPGs, and technology partnerships to upgrade bale-to-resin yields.
Regulatory and policy dynamics shaping 2026 choices
Recent policy moves materially affect strategic calculus. Notable developments include national strategies and implementation acts that tighten end‑of‑waste criteria, updates to labelling and authorization transfers, and evolving Extended Producer Responsibility (EPR) fee frameworks in the U.S. and Europe. For example, recent federal and state activity in the U.S. alongside an EU package enacted in late 2025 increases both the upside for compliant recyclers and the compliance risk for companies relying on low PCR content. Our report includes a regulatory impact matrix that translates each major policy into a quantified cost/benefit for manufacturers, recyclers, and brand owners across plausible compliance timelines.
Feedstock, pricing and short‑term market signals
Quality and price of bales and pellets remain the proximate drivers of plant economics. Publicly available price snapshots in 2026 show meaningful spreads between polymer grades and bale conditions, while macro indices for recyclable plastics exhibit month‑to‑month volatility. These dynamics are central to our cost curves and sensitivity models: a few hundred dollars per ton swing in feedstock price materially alters payback periods for greenfield lines and the attractiveness of retrofit projects. The full study provides a scenario matrix that links feedstock price bands to IRR outcomes by technology and geography.
What’s inside the PW Consulting Plastic Recycling Market report
The full report is designed for executives who must translate macro signals into executable plans. Key practical deliverables include:
- Bottom‑up market sizing and forecast (2026–2032) with scenario sensitivity to feedstock, policy, and demand shocks.
- Competitive benchmarking and strategic profiles for the leading processors, converters, and waste managers.
- Investment case templates — greenfield build, brownfield retrofit, and acquisition — with standardized CAPEX/OPEX assumptions and payback visualizations.
- Supply‑chain maps and feedstock flow models by major catchment; identification of logistical chokepoints and gate‑fee arbitrage opportunities.
- Technology readiness assessments comparing mechanical, advanced (chemical) recycling, and hybrid approaches, plus vendor scorecards.
- Regulatory impact matrix tying recent and imminent policy changes to commercial outcomes and compliance costs.
- M&A heatmap and consolidation scenarios informed by concentration metrics and value‑capture potential.
- Decision frameworks for procurement (contract length, indexation clauses, quality specs) and offtake negotiation playbooks for brand partners.
- A prioritized list of 10 high‑impact near‑term actions for CPGs, converters, recyclers, and investors to pursue in 2026.
Strategic actions for 2026 — recommended plays
- Secure quality feedstock through upstream partnerships: Invest in or partner with sorting and MRF operators to capture higher‑value bales and reduce feedstock variability risk.
- Lock in offtake and premium positioning: Negotiate multi‑year offtakes with brand owners seeking certified PCR, including price‑adjustment mechanisms tied to established indices.
- Selective capacity expansion and modularity: Favor modular, staged capacity additions that preserve upside exposure while limiting near‑term capital intensity.
- Regulatory arbitrage and compliance-forward sourcing: Use our regulatory matrix to prioritize investments in jurisdictions where end‑of‑waste clarity and favourable EPR design create faster payback.
- M&A as a scale tool: Target bolt‑on acquisitions to secure feedstock or certification capabilities rather than market share alone — consolidation should be value‑accretive through integration of logistics and quality control.
Methodology and credibility
Our models combine primary interviews with operators and brand procurement leads, facility‑level capacity mapping (leveraging the latest public infrastructure datasets), price series for recyclable feedstocks and resin indices, and policy timelines. We stress‑test outcomes across three scenarios (policy‑driven acceleration, market‑led steady growth, and technology‑displacement downside) and publish sensitivity tables that allow CFOs to re‑run NPV outcomes under alternate assumptions.
Final note — what’s intentionally omitted here
This briefing is curated to establish the strategic contours and practical implications for 2026. To preserve the value of the proprietary segmentation, granular regional and application splits, and the full set of numeric scenario outputs (which underpin investment and M&A decisions), we have intentionally withheld detailed subsegment tables and the full numerical matrices. The complete PW Consulting Plastic Recycling Market report contains the full data tables, downloadable model workbooks, and an interactive dashboard that decodes which subsegments and routes produce the best returns under each scenario.
For executives who need the detailed inputs to finalize capital allocation, sourcing contracts, or M&A mandates in 2026, the full report and model access are available through PW Consulting’s market research page. Our team is also available to run a tailored workshop that applies the models directly to your asset, portfolio, or procurement footprint.
For detailed analysis of this topic, please visit the official page: Plastic Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


